Smith Douglas Homes Has Record Orders, But Margins Must Stop Sliding For Bulls
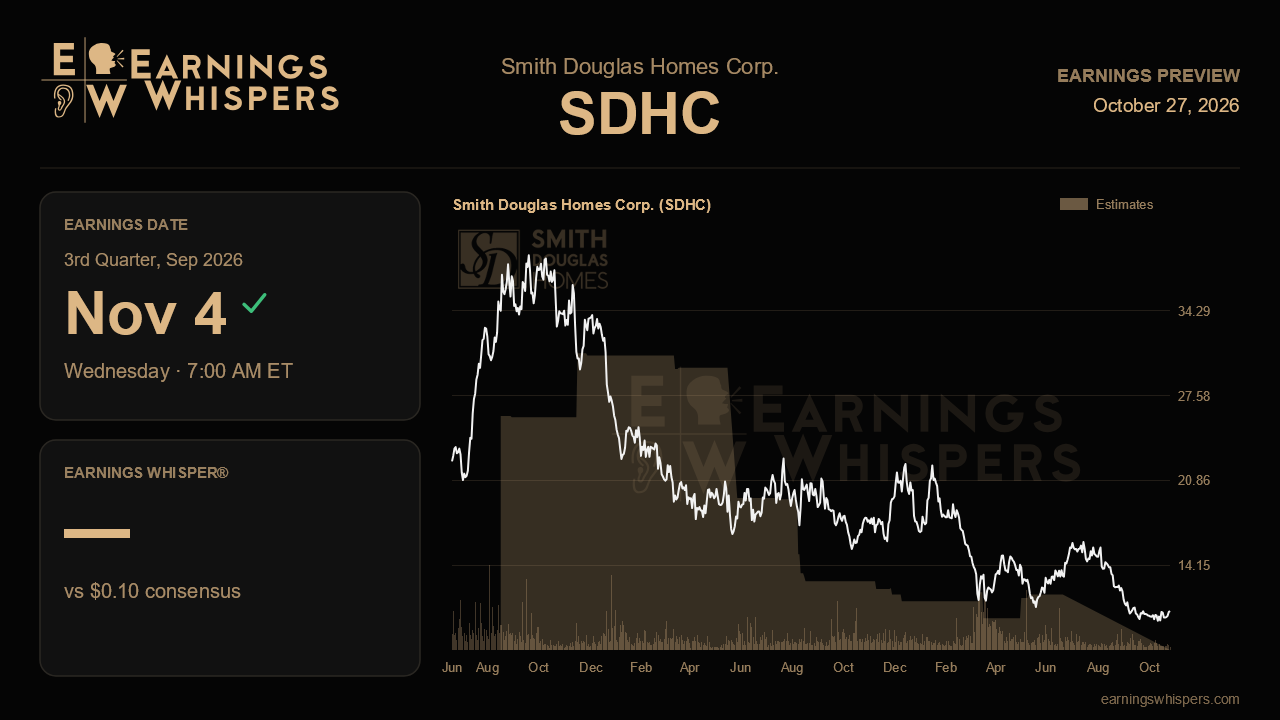
Smith Douglas Homes heads into its third-quarter report with a split story that the stock market has so far settled in favor of the skeptics. Over the past several quarters, management has described a business in which orders, community count and backlog are clearly building while margins keep getting worse. Investors have punished the shares for that second trend. The November 4 release, due before the open, is a test of whether the volume story is finally strong enough to make the margin story matter less.
The Street is looking for earnings of about $0.10 per share. That would be a sharp turnaround from the $0.12 loss in the year-ago quarter, and it explains the eye-catching growth rate of more than 180%. The sequential picture is less flattering, though. Consensus sits below the $0.16 the company earned last quarter on $273 million of revenue, so analysts already assume margins compress further even as more homes close. Management offers no full-year outlook, which it attributes to choppy demand. That leaves gross margin commentary as the only real guidepost.
That guidepost has moved in one direction. Gross margin guidance has been trimmed on each of the last three calls. It went from a range of 18.5% to 19.5%, to 17.5% to 18%, and most recently to 17% to 17.5%. Management also indicated that incentives embedded in the backlog point toward something closer to 16% to 16.5%. Incentives have climbed from roughly 6.8% of revenue to 7.8% on closed homes, and they now include outright base price cuts rather than only closing cost help and mortgage rate buydowns. Lot costs remain about a 300 basis point drag that management expects to persist for roughly two years. A gross margin at or modestly above the guided range would confirm that the floor is close. Anything near the backlog-implied 16% area, or another guide cut for the fourth quarter, would tell investors the bottom is still moving.
The volume side carries the bullish case, and it needs to keep delivering. Net orders hit a record 981 in the first quarter, up 28% from a year earlier. Community count reached 108, and by the second-quarter call backlog was growing in both segments across nearly every market. Management also said it expects backlog conversion to return to the 60% to 70% range as more buyers choose build-to-order homes. That points to a solid closings number this quarter if the claim holds. Confirmation would also include steady absorption per community, contributions from newer markets such as Dallas, Chattanooga, Greenville and the Alabama Gulf Coast, and evidence that falling competitor spec inventory is reducing the need for discounts. Management flagged softer land prices and better terms as a shift toward a buyer's market. Any detail on lower-cost land deals or the tuck-in acquisitions it has been exploring would support the idea that today's margin squeeze has an end date.
The market is not giving the company the benefit of the doubt. Shares have fallen about 29% since the last report while the S&P 500 was roughly flat. At $10.53 the stock sits well below its 200-day moving average near $13.82 and is closer to its post-earnings low of $9.71 than to its high of $15.14. It has also slipped beneath the prior quarter's trading floor. Sentiment remains bearish but slightly less so than heading into the last report. That suggests pessimism is entrenched rather than escalating, and a stabilizing margin print could meet a low bar.
In the end, the report turns on whether incentives have peaked. If incentive levels hold near 7.8%, gross margin lands within guidance, and orders and backlog keep growing on a larger community base, the growth-over-margin strategy looks like it is working. If discounting rises again and the margin outlook slips once more, rising volume will look less like a payoff and more like the cost of keeping houses moving.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-21 | |
| Aug-08 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Apr-29 | |
| Apr-28 | |
| Apr-15 | |
| Mar-11 | |
| Mar-11 | |
| Mar-04 | |
| Feb-24 | |
| Jan-26 | |
| Jan-17 |
