Smith Douglas Homes Tops A Lowered Bar, But Shrinking Margins, Falling Prices And Rising Leverage Define The Quarter
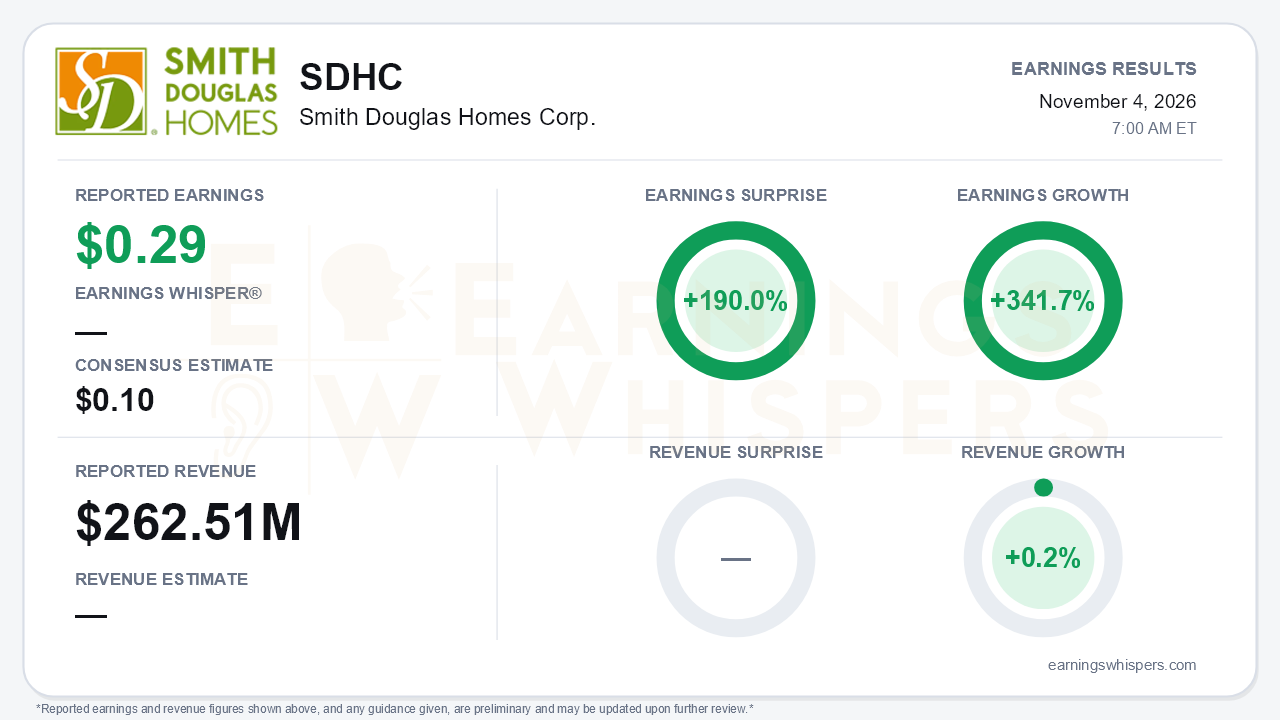
Smith Douglas Homes (NYSE: SDHC) beat a heavily discounted consensus. Earnings Whispers puts third-quarter earnings at $0.29 per share, against a $0.10 estimate, a 190.0% surprise and 341.7% year-over-year growth. Revenue of $262.51 million rose just 0.2%. Investors should read the headline carefully, because the GAAP results tell a very different story. Diluted GAAP EPS fell to $0.07 from $0.24. Pretax income dropped to $3.3 million from $17.2 million, and adjusted net income fell to $2.4 million from $13.0 million. The normalized figure sits on a different basis than the company's reported per-share result. Every profitability measure in the release moved sharply lower, so this was a beat against low expectations, not a sign of improving earnings power. That is the central tension: volume is growing while the economics of each home keep deteriorating.
The quality issues start with price and margin. Closings rose 5% to 831, but the average selling price fell to $316,000 from $333,000. That decline left revenue flat despite the extra homes. Home closing gross margin fell to 16.3% from 21.0% a year ago, from 19.6% in the first quarter and from 19.9% in the fourth quarter of 2025. On an adjusted basis, gross margin was 16.9%. SG&A rose to $40.4 million from $36.1 million as the company opened communities ahead of revenue, pushing overhead to roughly 15.4% of revenue from 13.8%. Both reportable segments earned less. Southeast segment net income fell to $12.1 million from $20.9 million. Management attributed the pressure to higher mortgage rates and affordability.
The conference call showed demand weakening more than the order count suggests:
- Net orders rose 13%, a clear slowdown from 28% growth in the first quarter.
- Absorption fell to roughly 2.3 sales per community per month, versus 4.0 in March.
- The September slowdown carried into October. Management described a "very inelastic" market that is not responding to incentives, a sharp change from the "encouraging price elasticity" it cited in the first quarter.
- Incentives eased only slightly, to 740 basis points from 780 in the second quarter, and are expected to rise in the fourth quarter to clear spec homes.
- Sales lagged production, so homes under construction swelled to 1,514 from 1,098 a year ago, and fourth-quarter starts will be minimized.
- Third-quarter closings landed at the low end of guidance, the first time the company has finished toward the bottom of its range.
The guidance cuts follow the same pattern. The fourth-quarter gross margin guide of 15.5-16.5% is the fourth straight step down, following guides of 17.5-18%, 17-17.5% and 16-16.5% earlier in the year, and the range is now wider. The ASP guide fell to $310,000-$320,000 from $330,000-$335,000 in the first quarter. Closings guidance of 800-875 homes is higher, but that growth comes from opening communities, not from stronger demand at existing ones. Backlog shows the same mix: units rose 25% to 947, but contract value rose only 18%, and the gain was concentrated in the Southeast while Central backlog slipped 2%.
The balance sheet has become a real constraint. Cash fell to $5.9 million, notes payable rose to $101.4 million with $99 million drawn on the revolver, and net debt-to-net book capitalization climbed to 17.9% from 6.6% at year-end. Operating cash use was $28.5 million through nine months. The company also spent $9.8 million on buybacks year to date, though only $0.3 million in the third quarter. Management outlined some offsets:
- A preliminary 2027 framework calling for 15-20% organic growth in both community count and volume, with five newer divisions expected to reach roughly 200 closings each.
- Active renegotiation with land partners on lot prices and takedown timing.
- Lower 10-year yields reducing forward commitment costs, plus softer horizontal development costs.
- A planned fourth-quarter inventory reduction to generate cash.
Bears still have legitimate ammunition: lots are stacking up against demand, further option abandonments are possible, and immigration-related labor shortages are lifting costs in some markets.
The market had already priced in much of this. Shares have fallen 31.2% since the open after the August report and trade 24.6% below the 200-day moving average. They sit 5% above the 52-week low of $9.71 set on October 14 and 32.6% below the post-report high of $15.14. Price and AVWAP trend readings remain negative. Investor sentiment improved slightly, to -0.28 from -0.31, but remains firmly negative, a modest change rather than a reversal.
The bottom line is that Smith Douglas beat a lowered consensus while nearly every underlying profitability measure deteriorated. Volume growth from new communities remains credible, and the 2027 framework gives the story a long-term anchor. However, falling prices, a fourth straight margin guide cut, slowing absorption and rising leverage mean the burden of proof now rests on proving those new communities can earn adequate margins in a market that is no longer responding to incentives.
Read our earnings preview for Smith Douglas Homes Corp.: https://www.earningswhispers.com/article/SDHC/21737
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Aug-08 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Apr-29 | |
| Apr-28 | |
| Apr-15 | |
| Mar-11 | |
| Mar-11 | |
| Mar-04 | |
| Feb-24 |
