Trex Faces A Margin Test As Revenue Estimates Crowd The Top Of Its Guidance
Trex heads into its third-quarter report with its demand story largely back on track, which shifts attention to a harder question: can the company turn a volume rebound into better profitability? Last quarter's sales surge showed customers are buying again. This quarter has to show that the cost of meeting that demand is starting to fade.
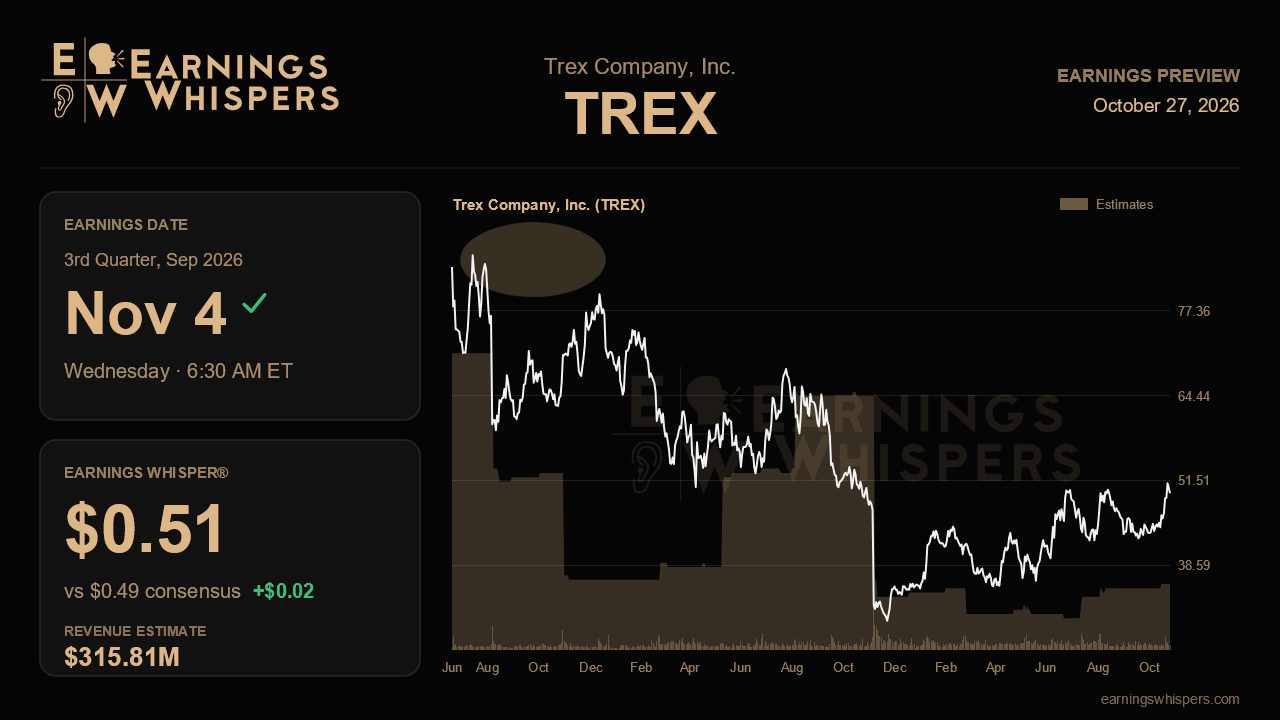
Wall Street expects earnings of $0.49 per share on revenue of $315.8 million when Trex reports before the open on November 4. That revenue figure would be up 10.7% from a year ago, a solid growth rate, yet earnings are projected to slip about 3.9% from last year's $0.51. That gap between top-line growth and bottom-line contraction is the heart of the setup. The Earnings Whisper sits at $0.51, slightly above consensus and level with last year's result, suggesting some investors think Trex can at least hold earnings flat. Management guided third-quarter revenue to $305 million to $320 million and reaffirmed full-year sales of $1.215 billion to $1.25 billion. Consensus once sat near $302 million, below the range, but has since climbed to the upper end, leaving less room for an easy upside surprise.
The previous call marked a clear change in tone. After a defensive stretch that included a revenue shortfall and a guidance cut a year earlier, Trex reported second-quarter sales well ahead of plan, said demand strengthened through May and June and carried into the third quarter, and lifted its full-year adjusted EBITDA outlook to $335 million to $350 million. Rolling sell-in growth accelerated to 9% and sell-out to 7%. Railing returned to double-digit growth, and entry-level Enhanced Basic decking posted its first real gain in years, which management framed as proof that its push to convert wood deck buyers is working. Evidence that these trends held through the summer selling season would validate the turnaround narrative.
The weak spot was gross margin, which fell to 37.9% from 40.5% in the first quarter. Management blamed a mix shift toward lower-margin railing and entry-level boards, startup depreciation at the new Little Rock plant, and roughly 100 basis points of temporary inefficiency from overtime and line changeovers. It described those inefficiencies as transient and noted that June's exit rate was well above the quarterly average. With the full-year adjusted gross margin target raised to about 38%, a third-quarter figure meaningfully above 38% would support that claim. A reading stuck near the second-quarter level would suggest mix pressure is more structural than advertised, especially if the entry-level products driving growth keep gaining share.
Two newer catalysts also deserve scrutiny. The distribution overhaul announced in July, which added partners such as Coastal and BlueLinx and opened what management sized as a more than $100 million conversion opportunity, takes effect in this quarter. Investors should look for signs that new partners are stocking shelves without inflating sell-in at the expense of later quarters, a relevant concern given that the guidance implies fourth-quarter revenue roughly flat to down year over year. Updates on the accelerated Little Rock ramp, targeted at about half its lines producing by year-end, and on the pace of the expanded $150 million buyback will round out the picture.
Sentiment has swung from modestly bearish before the last report to clearly bullish now, and the stock has gained 9.5% since then against a nearly flat S&P 500. At $49.57, shares trade well above their 200-day moving average and sit just below the post-earnings high of $51.10, putting a breakout within reach if the results cooperate. That also means a fair amount of optimism is already reflected in the price. The central issue is whether Trex can show that margin pressure peaked in the second quarter while demand stays firm. If both hold, the turnaround narrative remains intact; if growth arrives only at the cost of margins, the rally may need to pause.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-06 | |
| Sep-16 | |
| Sep-03 | |
| Sep-02 | |
| Aug-27 | |
| Aug-24 | |
| Aug-17 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 |
