Solstice Must Prove Its Raised Outlook Holds As Refrigerant Margins Face A Second-Half Test
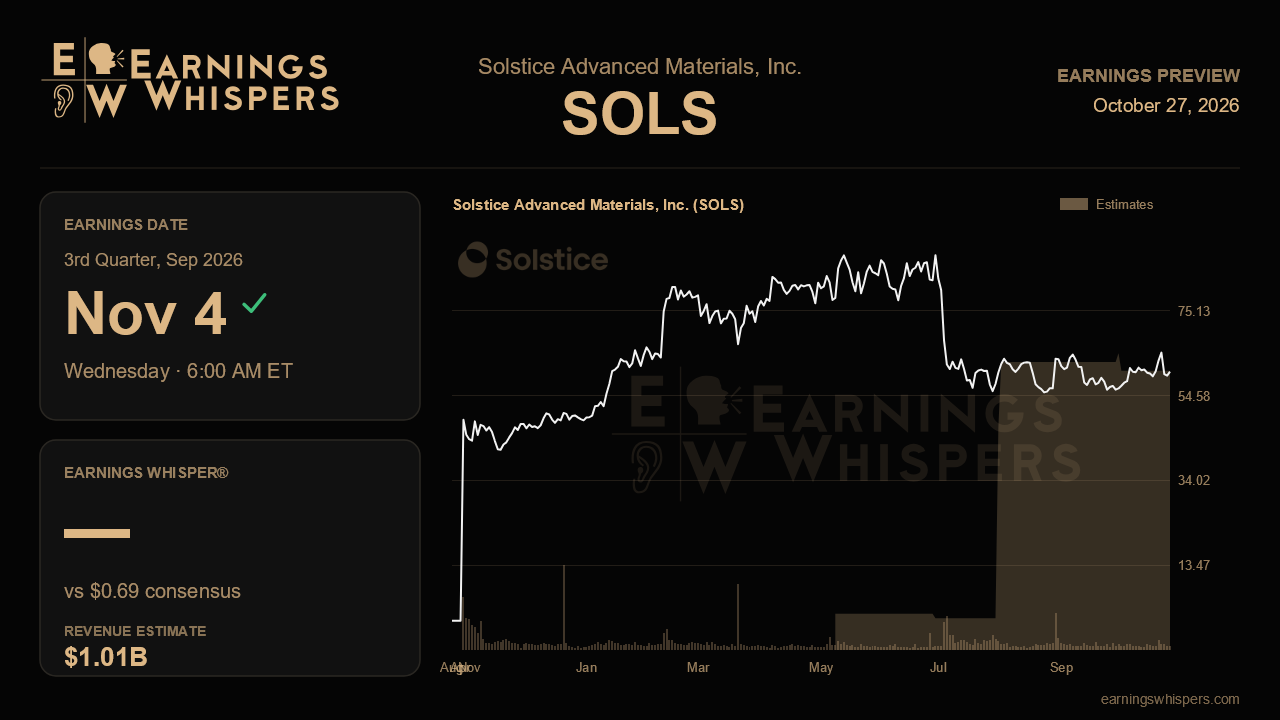
Three months ago Solstice Advanced Materials moved from proving it could stand on its own to arguing it could accelerate, raising full-year guidance for the first time since its spin and agreeing to buy Element Solutions. The stock has not followed that confidence. Shares sit near $60, well below the 200-day moving average of roughly $70 and far from the $90 peak of the prior quarter's range. The third-quarter report on November 4 is the first chance to show that the guidance raise reflected durable demand rather than a strong spring.
Wall Street expects earnings of $0.69 per share on revenue of about $1.01 billion. That is a clear step down from the second quarter's $0.88 and $1.15 billion, but the decline was largely anticipated. Management signaled flat to lower sequential revenue and an adjusted EBITDA margin only in the low 25% range. Plant turnaround timing and the absence of prior-year production incentive credits explain much of that. The full-year consensus of $2.87 per share sits in the upper half of the reaffirmed $2.75 to $2.95 range, a reasonable but not conservative bar. The Street's annual revenue estimate of $4.33 billion runs above the guided $4.125 billion to $4.185 billion. That gap suggests some forecasts reach beyond the current outlook and leaves little room for top-line slippage.
Refrigerants matter most. Second-quarter sales in the business rose 13% on the shift to lower-emission HFO products and strong data center cooling orders. Margin, however, fell to 32.9%, down more than six points from a year earlier. Management said it expects margins to return to the mid-30s in the second half. That is a specific, testable promise, and progress toward it in the third quarter would support the view that the margin dip was about timing. A margin stuck near 33%, especially if management cites sulfur and other raw material inflation, would raise doubts about how much of the full-year EBITDA guidance of $1.035 billion to $1.055 billion depends on a strong fourth quarter.
The growth engines also need to stay on pace. Electronic materials grew 15% last quarter, with segment margin climbing for several straight quarters to 21.6%. Continued strength there would support both the accelerated Spokane capacity spending and the logic behind Element Solutions. Healthcare packaging, up 24% after last year's destocking, should show whether that recovery reflects lasting demand or a one-time restocking bounce. Nuclear has been growing at 27% or better, but management flagged roughly $30 million of second-half revenue pressure from final product loan returns, weighted toward the fourth quarter. A softer nuclear number this quarter would therefore be expected. More telling would be updates on the three new small modular reactor supply agreements and the Metropolis debottlenecking review. Building solutions, down 1% on weak construction, is the drag most likely to linger.
Sentiment has improved modestly, moving from mildly bearish before the last report to slightly bullish now. The stock has gained about 3.9% since then, essentially matching the S&P 500. In effect, the market has accepted the raised outlook without rewarding it. The shares sit roughly midway between their post-earnings low of $54.56 and high of $67.50. Investors also have to weigh the debt that will fund Element. Management has pointed to current net leverage of 1.3 times and a path back below 3 times within 18 months of closing, and any refinement of that plan will draw scrutiny.
The central question is whether third-quarter margins show the turn management promised. If refrigerant profitability moves toward the mid-30s and the full-year range holds with consensus in its upper half, the acceleration story stays intact. If margins stall while costs rise, the guidance raise may start to look more like timing than trajectory.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-09 | |
| Oct-01 | |
| Sep-29 | |
| Sep-16 | |
| Aug-28 | |
| Aug-27 | |
| Aug-27 |
Solstice Advanced Materials, Element Solutions Cancel Deal After Shareholder Feedback
SOLS SOLS +12.76%
The Wall Street Journal
|
| Aug-27 | |
| Aug-14 | |
| Aug-04 |
