Solstice Beats And Raises Again, But Narrowing Growth And A Soft Fourth-Quarter Outlook Temper The Story
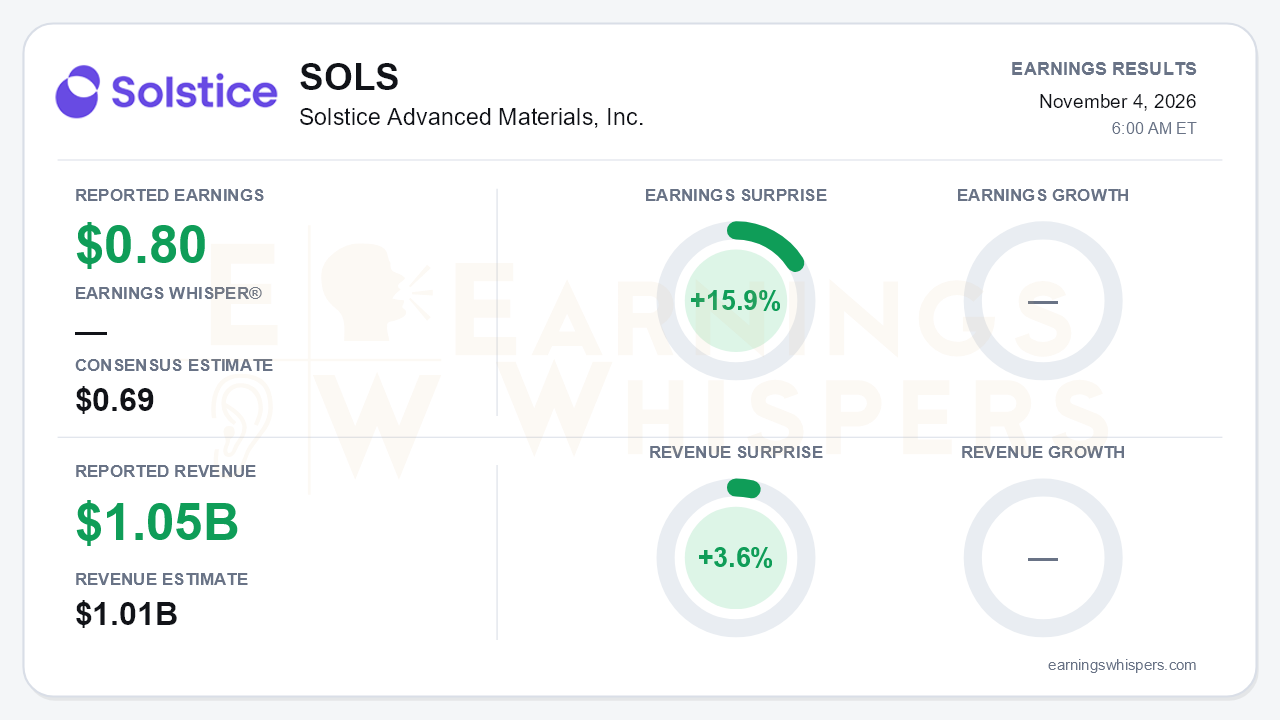
Solstice Advanced Materials (NASDAQ: SOLS) delivered a clean third-quarter beat. Adjusted EPS of $0.80 topped the $0.69 consensus by 15.9%, and revenue of $1.046 billion beat the $1.01 billion estimate by 3.6%. Sales also cleared the top of management's own guidance range, and full-year guidance was raised for a second straight quarter. The central tension is that the beat rests on a narrowing base. Electronic Materials is accelerating sharply. Meanwhile consolidated growth, refrigerants, and nuclear are all slowing, and the implied fourth-quarter outlook steps down meaningfully. Earnings Whispers characterizes that outlook as below estimates.
The quality of the quarter is better than the GAAP figures suggest. GAAP diluted EPS was $0.50, compared with a $0.22 loss a year ago. That swing mostly reflects the absence of last year's spin-related frictional taxes, which pushed the prior-year effective tax rate to 105%. The roughly $0.30 gap between GAAP and adjusted EPS this quarter comes chiefly from two items. The first is $34 million of written-off bridge-loan and backstop fees tied to the terminated Element Solutions merger. The second is $31 million of transaction costs. Investors should note the higher recurring interest burden of a standalone balance sheet. Interest and financial charges were $60 million, versus $2 million a year ago, even excluding the fee write-off from the comparison. Operationally, adjusted EBITDA rose 13% to $265 million, and margin expanded 109 basis points to 25.3%. That is a marked improvement from the roughly 2% EBITDA growth posted in the second quarter.
Beneath the headline, the two segments are moving in different directions.
Electronic & Specialty Materials posted record sales of $320 million, up 13%. Segment EBITDA jumped 44%, and margin widened 453 basis points to 21.2%. Electronic Materials drove that result, growing 31% on demand for sputtering targets and thermal solutions in memory and AI applications. That is up from 15% growth in the second quarter.
Refrigerants & Applied Solutions is losing momentum:
- Refrigerants growth slowed to 8%, from 13% and 19% in the prior two quarters, as residential 454B destocking persists. Management does not expect normalization until 2027.
- Nuclear grew just 4%, down from 27%, partly because of roughly $30 million in product loan returns.
- Building Solutions fell 5% on soft construction markets.
- RAS margin of 34.5% was down 82 basis points year over year on higher R&D. It recovered 160 basis points sequentially but only partly delivered the "mid-30s" second-half target.
Overall, organic sales growth of 8% compares with 11% and 10% in the first two quarters.
The forward-looking catalysts are substantive:
- **Nuclear backlog** rose to $2.6 billion from $2.2 billion, with contracts extending to 2039. Multiple conditional customer agreements were signed for a large conversion expansion, and Metropolis debottlenecking offers another 1-2kT of capacity at limited capex.
- **AI and data center exposure** was quantified for the first time at roughly 6% of 2026 revenue, up more than 50%.
- **Spokane** capex is being pulled forward to add sputtering-target capacity.
Bears still have legitimate ammunition. Spokane is effectively sold out until expansion volumes arrive, mostly in 2028, which caps near-term upside in the company's fastest-growing business. The large nuclear expansion has not reached its roughly 80% customer-commitment threshold. Management also expects nuclear to decline in the fourth quarter on order lumpiness and final loan returns. The fourth-quarter guide of $0.57-$0.62 in adjusted EPS and $246-$256 million in EBITDA sits well below third-quarter levels. With Element terminated and transformational M&A ruled out, the growth story is now entirely organic.
Capital returns provide a cushion:
- $100 million of the new $500 million buyback was executed in the quarter, with the remainder to be substantially completed by the end of the first quarter of 2027.
- Year-to-date free cash flow reached $368 million despite a 31% increase in capex.
- Net leverage stands at about 1.3x.
Investor sentiment barely moved, edging from -0.116 to -0.105. It remains mildly negative despite consecutive guidance raises. The stock entered the report at $61.74, up 6.3% since the open after the July report. The inter-earnings path was volatile. Shares hit a low of $54.56 on August 24, then rallied to a high of $67.50 on August 28, around the buyback announcement. They have since given back about half of that move and remain 12% below the 200-day moving average of $70.14. Momentum and AVWAP trend readings are positive, but the broader price picture shows a market that has not yet re-rated the stock.
The bottom line is that Solstice produced a high-quality beat-and-raise driven by a genuinely accelerating electronics franchise and a growing nuclear backlog. Those positives are offset by decelerating refrigerant and nuclear revenue, a capacity-limited growth engine, and a fourth-quarter outlook that appears to trail expectations. The beat-and-raise sequence is credible, but the next leg depends on RAS stabilizing and on Spokane and nuclear capacity converting into revenue.
Read our earnings preview for Solstice Advanced Materials, Inc.: https://www.earningswhispers.com/article/SOLS/21744
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-09 | |
| Oct-01 | |
| Sep-29 | |
| Sep-16 |
