XPEL Faces A Low Bar On Sales As Factory Costs And Margins Take Center Stage
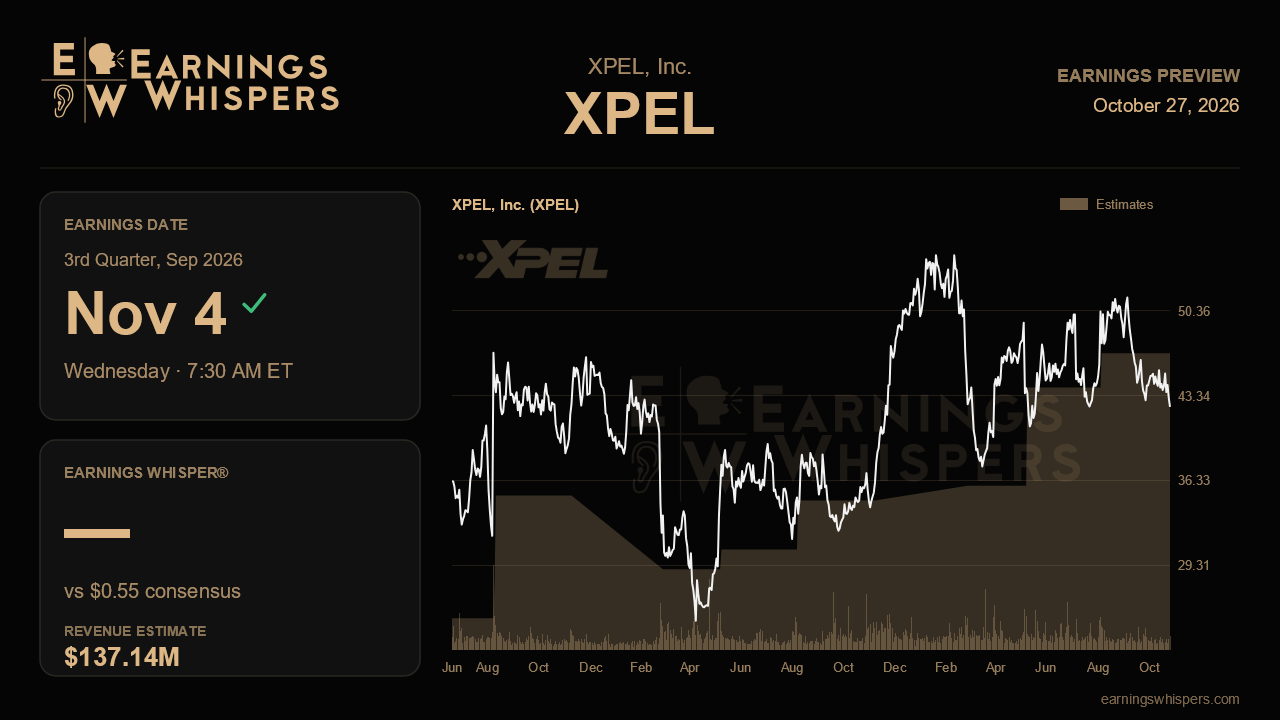
XPEL heads into its third-quarter report with an unusual mismatch. Management sounded more confident last quarter than it had in a year, raised its revenue outlook, posted record operating cash flow and finally laid out a concrete roughly $110 million manufacturing plan. The stock has fallen 13.5% since then, trailing the S&P 500 by about 12 percentage points. The Nov. 4 premarket release is a test of whether the market is right to discount that story, or whether a modest bar leaves room for a pleasant surprise.
Wall Street expects earnings of $0.55 a share on revenue of $137.1 million. That would be revenue growth of 9.4% and earnings growth of about 17%, solid but a clear step down from the 14% first-half sales pace and from the $0.68 and $143.1 million posted in the second quarter. Management guided to $137 million to $139 million, and consensus has drifted from well above that range to its very bottom. That is a conservative setup. XPEL guided the second quarter to $135 million to $137 million and then cleared the top by roughly $6 million, so a print at the low end of guidance would be a disappointment relative to the company's own track record, even if it technically meets the Street.
The second-quarter beat came with caveats that matter now. Canada rebounded nearly 11% partly because distributor timing that hurt the first quarter flipped into a tailwind, and that kind of swing tends not to repeat. Europe slipped on distribution timing and OEM production cadence, India and the Middle East fell 5% as the Iran conflict squeezed vehicle availability, and China's domestic car market was running about 20% below last year. Strength in the U.S., which hit a record, and in window film, which grew 16%, carried the quarter. Continued double-digit gains in those two areas would validate the idea that XPEL's core can outgrow a soft global backdrop. A slowdown there would suggest the second quarter flattered the trend.
Margins are the more important storyline. Gross margin has climbed from below 42% a year ago to 44.1%, helped by selling through higher-cost inventory from the China acquisition. Management also flagged oil-linked raw material pressure and pushed through modest price increases this quarter. Holding or extending that margin would show pricing is covering costs. A step backward would raise doubts about how much of the improvement was a one-time inventory effect. The earnings estimate also has to absorb manufacturing startup costs that management put at $0.03 to $0.04 a share, up from about $0.03 in the second quarter. Investors should look for any revision to that figure and any update on the timeline toward a mid-20s operating margin exiting 2028, with benefits starting in mid-2027.
The balance sheet deserves equal attention. Second-quarter capital spending jumped to $65.1 million including real estate, and XPEL added a $44.8 million term loan. After a record $30.8 million in operating cash flow last quarter, another strong cash quarter would ease concerns about funding the largest project in the company's history. A reversion toward the weak collections seen in the first quarter would sharpen them.
Sentiment has improved, with bearish readings easing to 43.2% from 52.8% a quarter ago, but the stock tells a gloomier story. At $42.40, shares sit below the 200-day average of $46.44 and are pinned against the post-earnings low of $42.32, near last quarter's floor of $39.83. That positioning implies modest expectations. Ultimately, the report will turn on whether XPEL can again beat its own guidance while keeping gross margin near 44% despite rising factory startup costs. If it does, the manufacturing bet looks like a margin story worth funding. If it doesn't, the market will likely keep treating it as an expensive one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-23 | |
| Oct-21 | |
| Sep-10 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| May-19 | |
| May-14 | |
| May-06 | |
| Apr-23 | |
| Apr-22 | |
| Mar-31 | |
| Feb-26 |
