XPEL Beats On Record Margins, But A Q4 Revenue Guide Near 2-4% Growth Exposes A Slowing Top Line
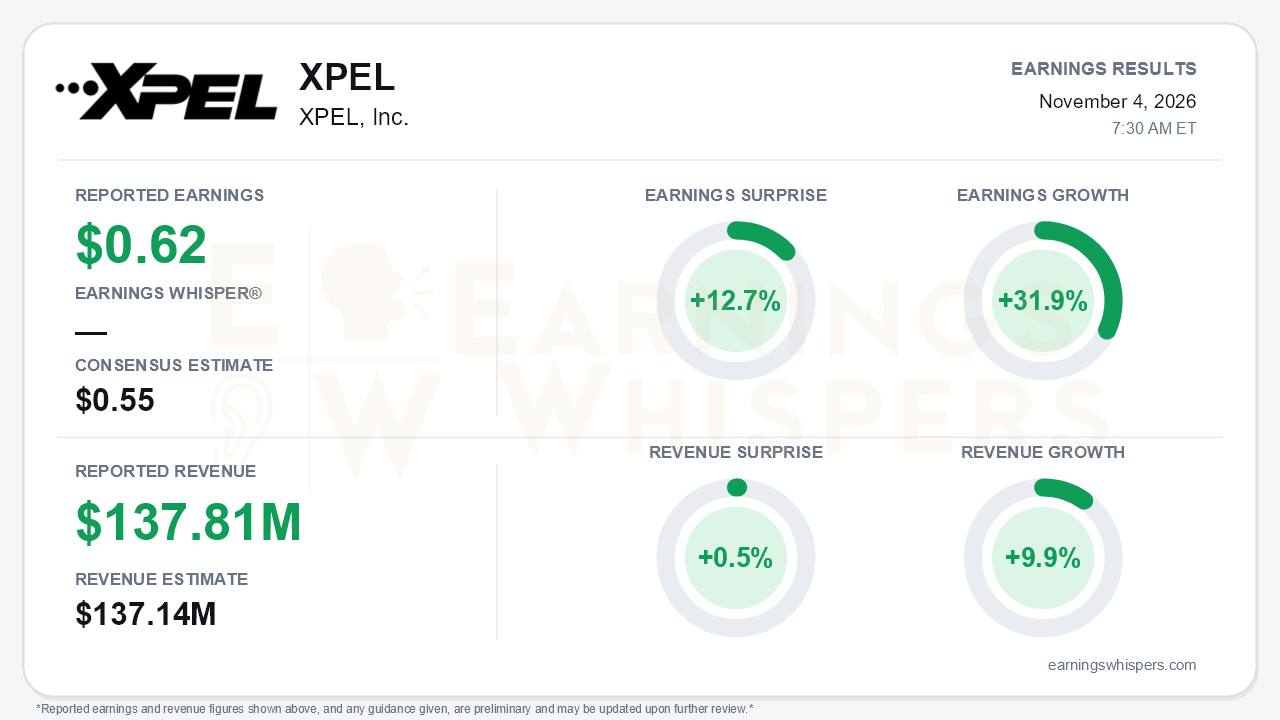
XPEL delivered a clean earnings beat for the third quarter, but the quarter's real message is that its margin engine is running faster than its sales engine. Adjusted EPS of $0.62 topped the $0.55 consensus by 12.7% and grew 31.9% year over year, while revenue of $137.81 million edged past expectations by 0.5% and grew 9.9%. The forward view tempers that headline. Management guided fourth-quarter revenue to $125-$127 million, below estimates and implying only about 2-4% growth against roughly $122 million a year ago. That is the central tension: profitability is improving quarter after quarter just as demand in several of XPEL's most important channels weakens.
The beat itself was earned largely through gross margin. Gross margin reached 44.6%, up from 41.8% a year ago and the third straight sequential gain after 41.9% in Q4 FY25, 43.7% in Q1 and 44.1% in Q2. On the call, management attributed the improvement to capturing distributor margin in China and to bill-of-materials cost reductions. Pricing contributed about 1% or less because input-cost pressure was milder than feared. GAAP EPS rose to $0.59 from $0.47. The $0.03 gap to the adjusted figure reflects start-up costs at the San Antonio manufacturing plant, an expense management expects to run at $0.03-$0.04 per share with no offsetting benefit until mid-2027. Operating expenses grew 13.3%, faster than revenue, although management said SG&A excluding China grew only about 4%.
Cash generation was weaker. Operating cash flow fell to $21.1 million from $33.2 million a year earlier and from a record $30.8 million in Q2. Rising receivables and $7.6 million in cash taxes accounted for much of the drop. The balance sheet has also changed. Property and equipment jumped to $95.1 million from $15.8 million at year-end on $76.7 million of year-to-date capital spending, funded in part by $42.6 million of new long-term debt. XPEL still bought back about $3 million of stock in the quarter.
The call showed clear deceleration beneath the headline. Total growth slowed from about 14% in the first half to 9.9%, and revenue landed toward the low end of the $137-$139 million guide. U.S. growth slowed to 7% from 11.7% in Q2, and the Q4 outlook assumes low single digits. The dealer channel was flat as FTC scrutiny combined with California's CARS Act, which took effect October 1. That is a sharp reversal from Q1's 27% global dealership install growth, and management expects dealer trends to worsen incrementally in Q4. The U.S. aftermarket also softened late in the quarter amid signs of consumer weakness. Overseas, the Middle East deteriorated instead of improving, with India and Middle East revenue down 16.6%, and EU/UK/Africa slipped 2.1%. China's 52.4% growth reflected the final inorganic comparison before XPEL laps the acquisition, while domestic Chinese car sales are down more than 20%. Canada was the standout, accelerating to 17.9% from 10.8%. Management's tone shifted noticeably, conceding the headwinds have been "larger and lasted longer than we might have hoped."
The longer-term catalysts are real but mostly dated to 2027 or later:
- a substantial OEM contract in India expected to contribute from 2027;
- the Visco OEM graphics tuck-in, which adds new major-OEM relationships;
- a direct operation in Brazil;
- an OEM pipeline described as roughly twice the company's cumulative history;
- plans to use the China plant for export markets in the first half of 2027.
Management also reaffirmed its target of a mid-20s operating margin exiting 2028. FTC guidance is bringing more clarity to dealer add-on rules, but national consolidators are also consolidating vendors, which lengthens sales cycles.
Investor sentiment remains negative but improved, rising from -0.53 to -0.39 ahead of the report. Price action has been harsher. Shares closed at $42.49 on November 3, down 13.3% since the open after the August report and 7.9% below the 200-day moving average. They sat just 1.7% above an inter-earnings low set that same day, and 18.4% below the $52.05 high reached right after the prior report. The Earnings Whispers trend readings are mixed, with momentum positive but price and AVWAP trends negative. In other words, the market had already priced in a good deal of the slowdown before the guide arrived.
The bottom line is that XPEL's quarter showed a business improving its economics faster than it is growing its sales. The margin expansion and EPS beat are credible and structurally driven, and the 2027 catalyst list is longer than it was a quarter ago. However, the Q4 guide, the flat dealer channel, softer U.S. consumers and overseas weakness give bears legitimate ammunition on the top line. Until revenue growth stabilizes, margin gains alone may struggle to lift a stock trading near its lows.
Read our earnings preview for XPEL, Inc.: https://www.earningswhispers.com/article/XPEL/21762
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-23 | |
| Oct-21 | |
| Sep-10 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| May-19 | |
| May-14 | |
| May-06 | |
| Apr-23 |
