Vishay Precision Must Prove Record Sensor Bookings And Humanoid Hopes Can Lift Thin Margins
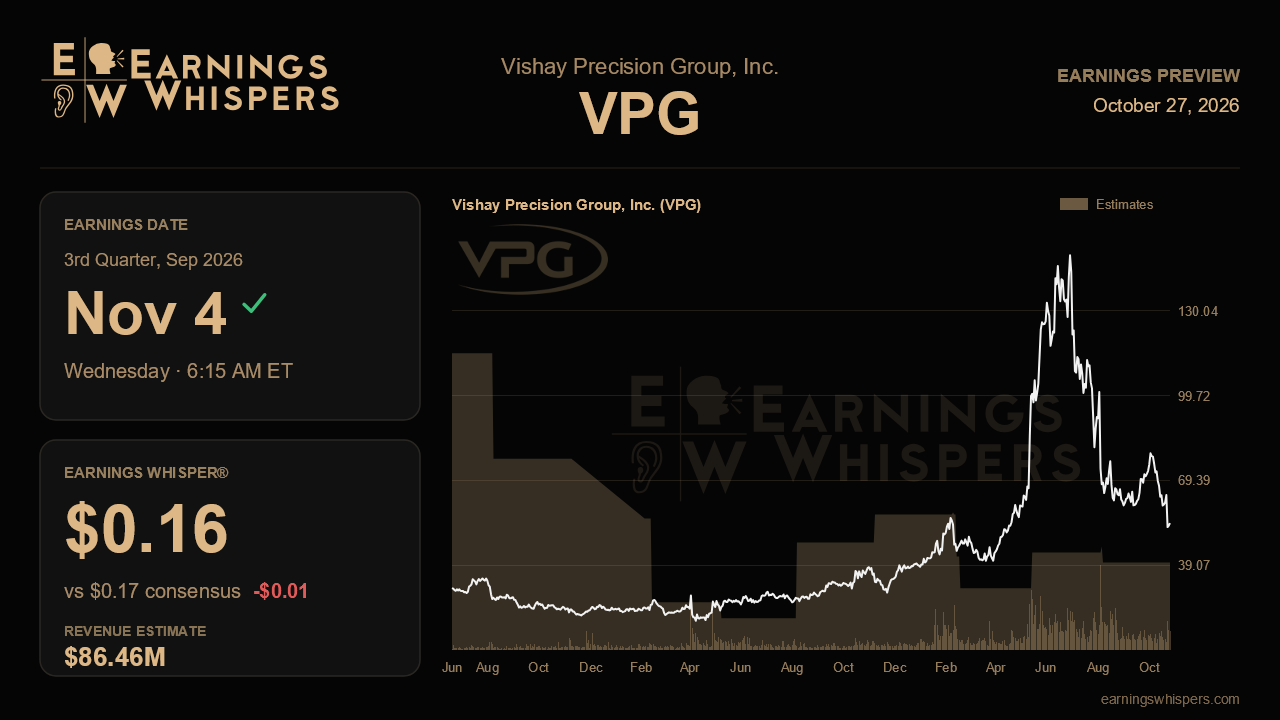
Vishay Precision Group heads into its third-quarter report with a striking disconnect. Last quarter management described a business with accelerating demand, record sensor bookings and a formal vendor nomination from its first humanoid robotics customer. Yet the stock has fallen about 21% since that report while the S&P 500 slipped just over 1%. The upcoming release, due before the open on November 4, needs to show that the order strength is turning into revenue and, more importantly, into profit.
The bar is modest on the top line and low on the bottom line. Analysts expect earnings of $0.17 a share on revenue of $86.5 million. That revenue figure sits exactly at the midpoint of management's $84 million to $89 million guidance, and it is below the roughly $88 million the Street carried when the range was issued. Analysts have pulled back toward the company's own view rather than leaning on it. Revenue growth of about 8% from a year ago would be respectable, but earnings are expected to fall roughly 35% from $0.26. That gap captures the core problem: sales are growing, but margins have not kept up. The Earnings Whisper of $0.16 sits a penny below consensus, a small difference that still suggests no one is braced for an upside surprise.
The swing factor is margins, especially in sensors. Sensors gross margin fell to 31.5% last quarter from 34.8%, and management blamed currency, material costs and the labor drag from hiring and training new workers. Consolidated GAAP operating margin was slightly negative, and the adjusted figure was under 2%. Management pointed to selective price increases, which should start helping in the second half, and to a cost program targeting about $6 million of savings this year after roughly $1.6 million in the first half. A sequential rebound in sensors margin, combined with visible savings, would back the argument that last quarter's squeeze was temporary. Another quarter of compression, especially if currency effects keep growing, would raise doubts about how much of the record backlog will actually reach earnings.
Demand trends also need to stay consistent. Sensors bookings reached a record $48.1 million with a book-to-bill of 1.44, the second straight record, and consolidated backlog climbed to $135.8 million. Weighing solutions orders slipped below a 1.0 book-to-bill, however, and measurement systems orders fell about 22% on project timing and a weak steel market. Management also raised its full-year organic growth outlook above its 8% to 10% model. Holding that outlook, rather than quietly walking it back, would be the clearest sign that confidence in the business is intact. Investors should also watch for progress in clearing the roughly $3 million of shipments delayed by the new ERP system, which management expects to land in the fourth quarter.
The humanoid opportunity is the newest catalyst and the one the market seems most skeptical of. Management expected the first customer to ramp in the second half from tens of robots a week toward hundreds or thousands. This report is the first real checkpoint on that timeline. Updates on production volumes, prototypes at customers three and four, and whether the second customer has finished revising its designs will show whether this is a business line or still a promise.
The stock's chart reflects plenty of doubt. Shares at about $54 sit well below the 200-day average near $73 and only about 5% above the post-earnings low. That is a steep fall from a prior-quarter range that topped $150. Sentiment remains mildly bearish and essentially unchanged from last quarter. The central question is simple: can Vishay Precision show that record bookings, price increases and cost cuts are finally lifting margins? If it can, the recent selloff looks overdone. If not, the growth story may stay stuck at the order line.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-08 | |
| Sep-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-15 | |
| Jun-30 | |
| Jun-29 | |
| Jun-18 | |
| May-28 | |
| May-19 | |
| May-12 | |
| May-12 | |
| May-12 |
