Vishay Precision Group Misses On Taxes And Tariff Optics, But Record Sensor Orders And A 10-12% 2027 Framework Change The Story
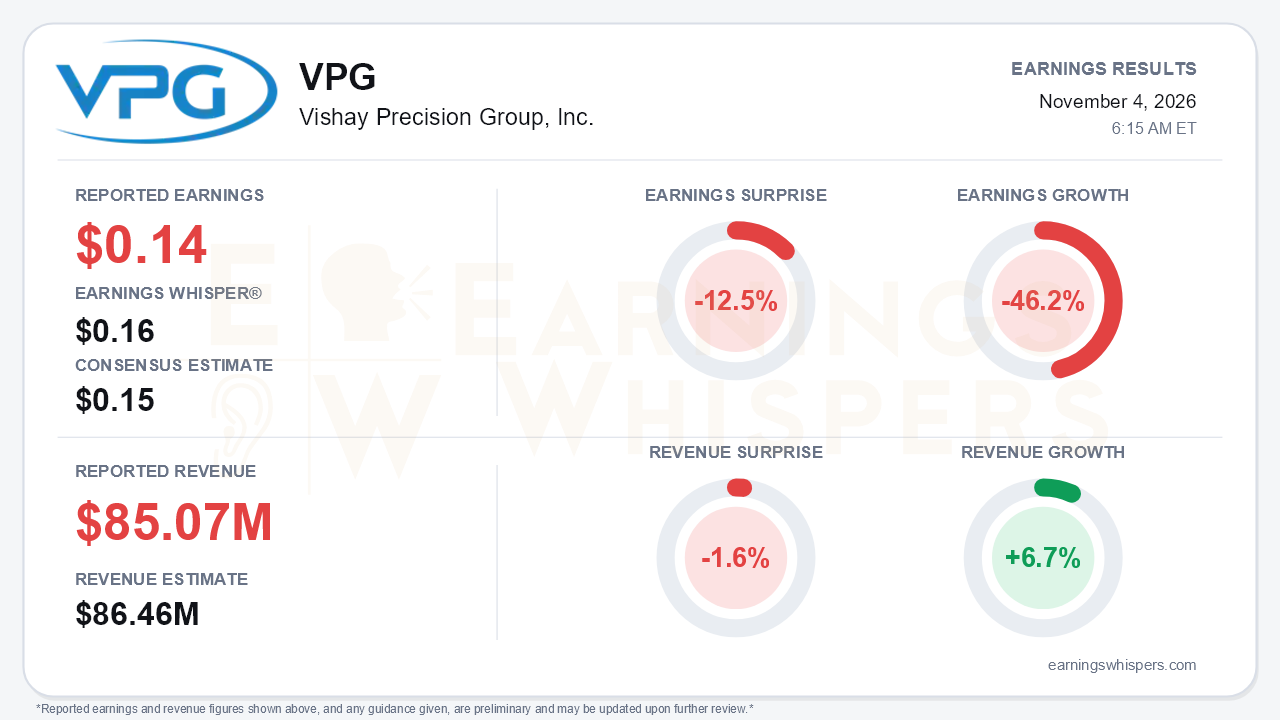
Vishay Precision Group (NYSE: VPG) reported third-quarter adjusted earnings of $0.14 per share, short of the $0.15 consensus and the $0.16 Earnings Whisper number, a 12.5% negative surprise. Earnings fell 46.2% from a year ago. Reported revenue of $85.07 million missed the $86.46 million consensus by 1.6%, though it still grew 6.7% year over year. On the surface, this was a miss on both lines. Underneath, it was one of VPG's better operating quarters in some time. The gap between those two readings is the central tension in the report.
The quality of the miss deserves scrutiny because much of it came from items outside core operations. GAAP revenue was reduced by $2.3 million of U.S. tariff refunds passed through to customers, with no effect on gross profit. Adjusted revenue of $87.4 million rose 4.1% sequentially and 9.6% year over year, which marks an acceleration from the $83.9 million and $84.4 million posted in the prior two quarters. That figure sits above the consensus revenue estimate, and it landed within management's prior $84-89 million guide.
On earnings, a shift in the geographic mix of income pushed the adjusted tax rate to 48%. Management said that shift cost $0.03 per share, more than the entire shortfall against the whisper. Currency was another drag, reducing operating income by $3.4 million versus last year. The GAAP comparison looks far worse, $0.04 versus $0.59, but the prior-year quarter included a $5.5 million gain on the sale of the Kent, Washington facility. That gain was worth $0.42 per share.
The sequential trajectory is what changed. Adjusted gross margin improved to 39.3% from 38.6% in the second quarter. Adjusted EBITDA jumped to $8.2 million (9.4% margin) from $5.5 million (6.5%). Free cash flow swung to a positive $5.5 million from negative figures in each of the first two quarters. Orders topped $103 million for a 1.17 book-to-bill, the eighth straight quarter at or above 1.0. Backlog climbed to $151 million from $135.8 million.
Sensors carried the quarter. Bookings reached a second consecutive record of $51.7 million (book-to-bill 1.35), and revenue rose 14.8% sequentially to $38.4 million. Management attributed the strength to AI-driven demand for precision resistors in semiconductor equipment, data center, and fiber-optic applications, along with aerospace and defense. Measurement Systems was the other bright spot, with revenue up 9.7% sequentially and gross margin expanding to 56.5% from 52.5%. Weighing Solutions was the weak link. Adjusted revenue fell 11.3% sequentially on European seasonality, and adjusted gross margin slid to 34.6% from 37.3%.
The call added the forward-looking piece the release lacked. Management introduced an initial 2027 framework of 10-12% revenue growth, above its 8-10% three-year plan, and pointed to first-quarter 2027 revenue of $90 million or better. That continues a steady upward progression in tone across the last several calls. The humanoid robotics opportunity also gained substance. VPG's first humanoid customer invested in the company to fund capacity expansion, and the second customer's opportunity was described as potentially larger than previously thought.
Bears have legitimate ammunition, however. The initial customer's humanoid ramp slipped to the fourth quarter. Humanoid bookings fell to roughly $0.2 million from $0.5 million, so the program remains a promise rather than a revenue line. The fourth-quarter guide of $84-91 million is unusually wide, partly because of humanoid supply-chain volatility, and its midpoint is essentially flat with third-quarter adjusted revenue. Other headwinds include:
- The operational tax-rate assumption rose to about 45% from about 30%.
- Capex guidance moved up to $14-16 million from $10-12 million.
- Sensors face capacity and lead-time constraints.
- Adjusted operating margin of 4.9% remains far below the 14.5-15.5% target model.
The market had already turned hard against the stock heading into the report. Shares opened at $68.22 after the August release and closed at $54.24 on the eve of this report, down 20.5%. That decline masks a sharp round trip. The stock hit an inter-earnings high of $80.24 on October 2, then collapsed to a low of $51.36 by October 23. It now sits only 5.6% above that low and 26.5% below its $73.80 200-day moving average. Price trend and AVWAP readings remain negative. Investor sentiment, already negative, slipped modestly from -0.20 to -0.24, a sign of incremental caution rather than capitulation.
The bottom line is that VPG's headline miss was driven largely by taxes, currency, and tariff pass-through accounting, not by a weakening business. Orders, backlog, sensor demand, EBITDA, and cash flow all moved in the right direction, and the 2027 framework raises the growth bar. The obstacles are timing and conversion. Humanoid revenue keeps sliding to the right, the fourth-quarter guide implies a pause, and margins remain a long way from the target model. With shares sitting near their quarterly lows, investors are pricing those execution doubts more heavily than the improving order book.
Read our earnings preview for Vishay Precision Group, Inc.: https://www.earningswhispers.com/article/VPG/21757
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-08 | |
| Sep-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-15 | |
| Jun-30 | |
| Jun-29 | |
| Jun-18 | |
| May-28 | |
| May-19 |
