Enact's Telegraphed Delinquency Uptick Puts Its Raised Capital-Return Story To The Test
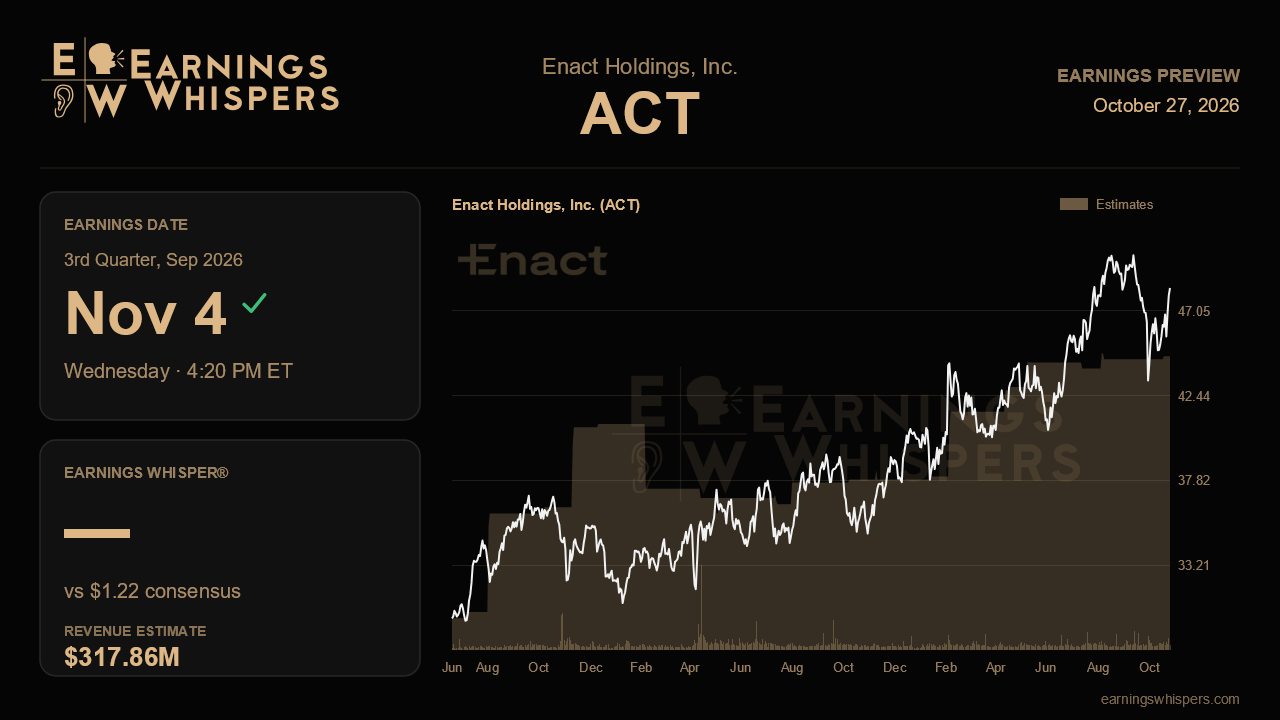
Enact Holdings enters its third-quarter report having done something mortgage insurers rarely do mid-year: it told investors it would hand back more money and spend less to run the business, while also warning that credit would look a little worse in the back half. That combination makes this report a test of whether the bad news management pre-announced stays as mild as promised, and whether the good news holds up once it does.
Wall Street expects earnings of $1.22 per share on revenue of about $317.9 million. That EPS figure would be roughly 9% above the $1.12 earned a year ago but a step down from the $1.26 posted last quarter, and revenue growth of about 2% essentially describes a flat top line versus the second quarter's $317.3 million. In other words, the Street has already penciled in some sequential slippage. For a business whose premium base grows slowly, the earnings line is driven largely by losses, reserve releases, expenses and investment income, which is exactly where the action was last quarter.
The second-quarter call delivered the clearest improvement in tone in a year. Management lifted its 2026 capital return target to $550 million to $600 million, up from the $500 million it had held for two quarters, which itself was a step up from $400 million. It also trimmed its full-year operating expense outlook to $205 million to $210 million from $215 million to $220 million. With expenses lower and investment income rising, helped by a book yield that climbed to 4.6%, the cost and income side of the ledger should provide support. The real swing factor is credit. New delinquencies fell to 12,300 last quarter and the loss ratio improved to 14%, but management explicitly guided to a seasonal rise in the delinquency rate during the second half. It also cautioned that 2022 and later purchase-heavy vintages, with less home price appreciation cushioning them and higher loan-to-value and debt-to-income profiles, will produce more delinquencies as they season.
That warning sets up the key distinction for this report. A moderate increase in new delinquencies paired with a loss ratio that drifts up only modestly would validate management's framing that this is normal seasoning rather than deterioration. A sharper jump, particularly one concentrated in recent vintages, would challenge it. Reserve releases deserve equal attention, since they have shrunk from $48 million a year ago to $37 million last quarter, and further fading would mean less prior-period padding beneath earnings. Beyond credit, investors should look for the base premium rate, which has slid from 39.6 to 39.1 basis points over three quarters, to stabilize in line with management's broadly flat full-year view. Persistency, which eased to 80%, and new insurance written after the spring-driven $15 billion quarter will indicate whether the insured portfolio keeps growing. Any early read on the Ella AI underwriting tool or the VantageScore 4 rollout would be a bonus, though management called the latter immaterial so far.
Sentiment has warmed noticeably, with bearishness roughly halving from the prior quarter, though it still leans negative. The stock has edged up about half a percent since the last report, modestly ahead of a slightly lower S&P 500, and at $48.29 it sits comfortably above its 200-day moving average and in the upper part of a post-earnings range that has shifted higher than the previous quarter's. It remains about 4.5% below its recent high, so this is not a breakout setup, but the market has clearly given the raised guidance some credit.
Ultimately, this quarter hinges on whether the delinquency uptick arrives at the gentle pace management described. If credit seasoning stays orderly and the company reaffirms its larger capital return plan, the improving narrative from last quarter remains intact. If losses climb faster than expected, the generous buyback story starts to look more fragile.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-23 | |
| Oct-08 | |
| Oct-08 | |
| Oct-01 | |
| Sep-22 | |
| Sep-18 | |
| Sep-15 | |
| Sep-03 | |
| Sep-02 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-09 | |
| Jul-09 |
