Acadia's Turnaround Faces A Proof Test As New Hospitals Ramp And Legal Costs Linger
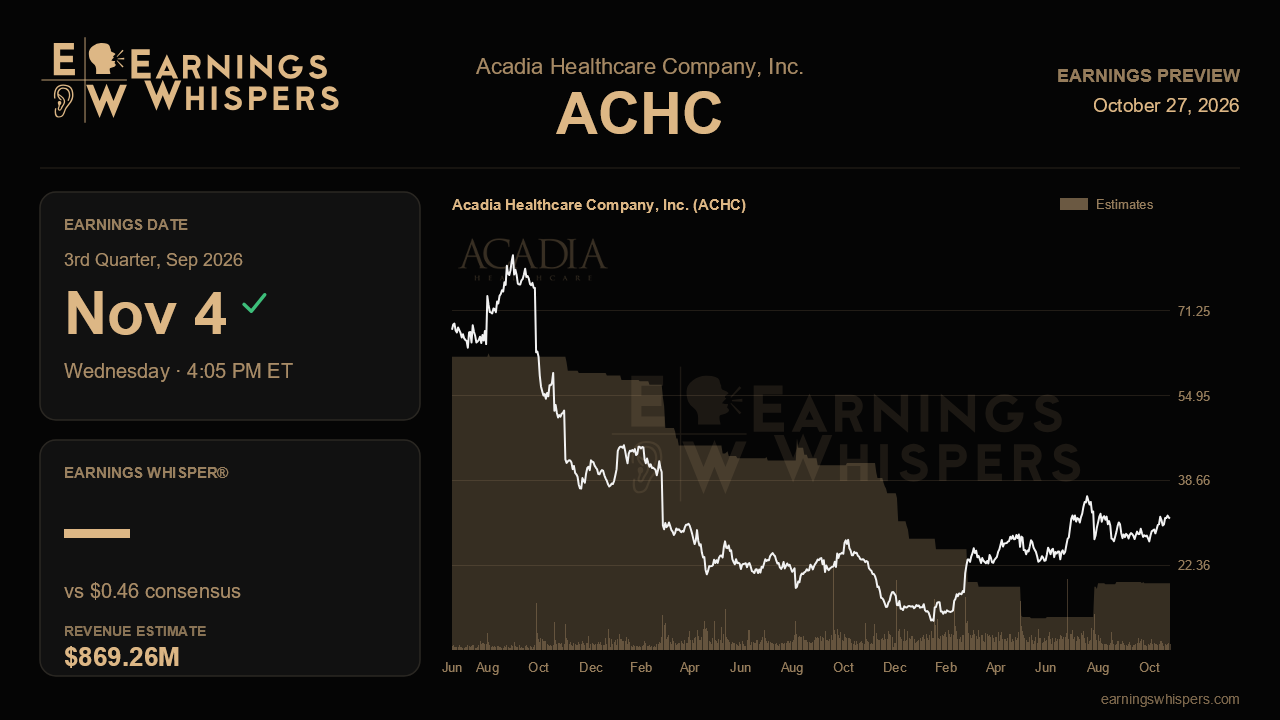
Acadia Healthcare enters its third-quarter report with a turnaround story that has gained credibility on paper but has yet to win over the market. Management has raised its full-year profit outlook three times, free cash flow has swung sharply positive, and the newest facilities are filling faster than planned. Yet the stock has slipped 4.8% since the last report while the S&P 500 gained 3.4%. That gap suggests investors want more evidence before they pay for the recovery.
The headline numbers look soft. Analysts expect earnings of $0.46 per share, down about 36% from $0.72 a year ago, on revenue of $869.3 million, up a modest 2.1%. That is essentially flat with the $865.8 million booked last quarter, though the per-share figure would be a step up from the prior quarter's $0.38. Management's full-year guidance of $1.45 to $1.60 per share sits around a $1.50 consensus, which is the lower half of the range. On revenue, the Street's $3.40 billion estimate sits at the bottom of the $3.40 billion to $3.45 billion outlook. In other words, analysts are not assuming management hits the upper end. That leaves room for an upside surprise if the operating trends from last quarter hold.
The most important of those trends is the class of facilities opened from 2023 through 2026. Revenue and facility-level profit from this group beat internal plans for two straight quarters. Startup losses also ran lighter than expected, and management grew more confident in its target of $200 million in added EBITDA from the cohort. The company opened two acute joint-venture hospitals on schedule last quarter, in Orlando and in Iowa, and planned a de novo facility near Jacksonville for the third quarter. Early occupancy at those sites, and continued filling at Coachella Valley, which was already above 90%, would support the thesis that growth is shifting from construction to profitable operations. Same-facility revenue growth of only 3.2% on a normalized basis was a weak point last quarter. A pickup there would show the core business is contributing, not just the new buildings.
The swing factor that could muddy the picture is professional and general liability expense. A $28.6 million reserve increase tied to prior-year cases pushed current-year costs toward roughly $135 million, well above the $100 million to $110 million the company considers normal. Last quarter, a $26.1 million Florida supplemental payment largely offset that hit. Another reserve top-up without a similar cushion would revive concerns that the legal environment is a structural drag rather than a one-time problem. The opioid treatment clinics, whose revenue was flat and slightly behind plan, also need to show signs of life. New York Medicaid changes still trim about a point from same-facility growth. Any update on Florida and Ohio supplemental programs, which management said could add more than $20 million in EBITDA, would help offset those pressures.
Sentiment has turned noticeably. It moved from moderately bearish before the last report to moderately bullish now. That shift raises the bar somewhat, even if the stock's lagging performance suggests the optimism is not fully priced in. Shares trade at $31.34, comfortably above the 200-day moving average near $25.39 and in the upper half of the $26.62 to $33.00 post-earnings range. That range is far narrower than the previous quarter's swing between $21.60 and $35.83, a sign the volatility has calmed.
The central question is whether Acadia can deliver a clean quarter, one where the new-facility ramp, cash generation and the trend toward lower debt shine through without another reserve charge overwhelming them. Reaffirming or nudging up the $590 million to $615 million EBITDA outlook would keep the turnaround narrative intact. Investors will also want to hear how management plans to sustain growth with no new projects slated for late 2026 or early 2027.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Oct-13 | |
| Sep-28 | |
| Sep-25 | |
| Sep-09 | |
| Aug-12 | |
| Jul-31 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-09 | |
| Jun-03 | |
| May-13 |
