Acadia Healthcare Beats Big And Raises Guidance Again, But A Florida Windfall And Weak Commercial Mix Temper The Quality Of The Quarter
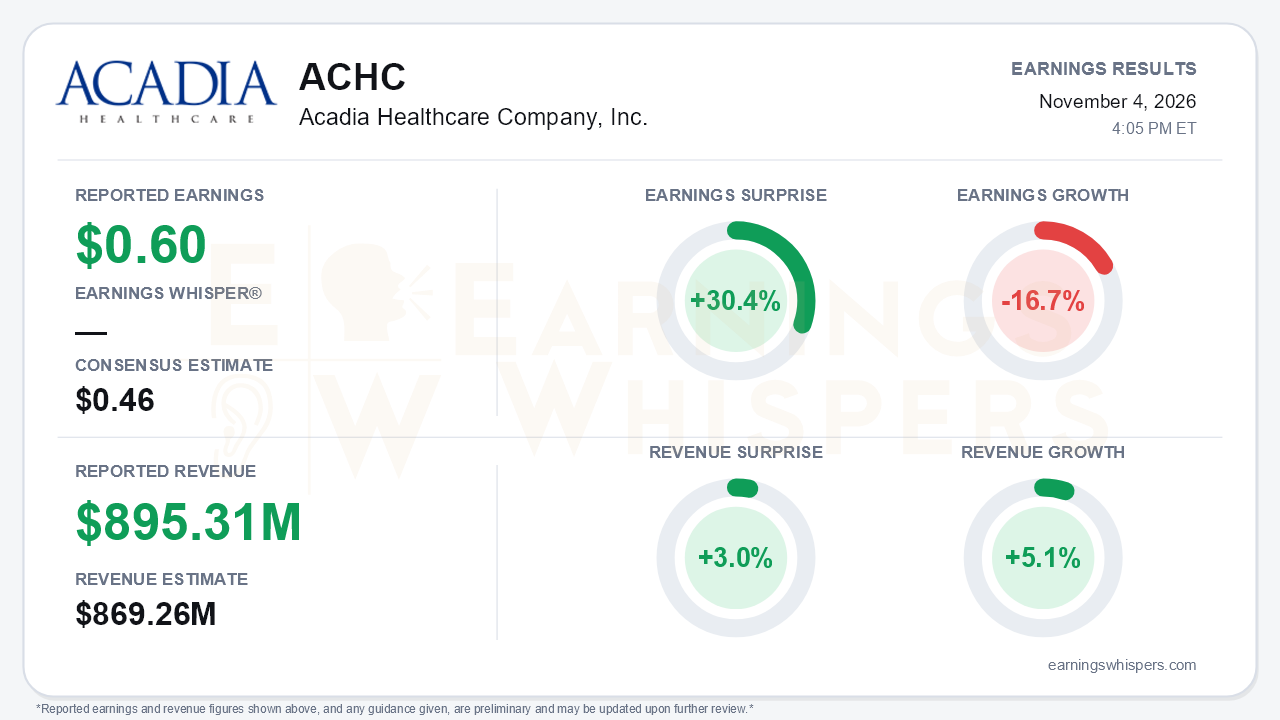
Acadia Healthcare delivered a convincing headline beat in the third quarter. Adjusted earnings of $0.60 per share topped the $0.46 consensus by 30.4%, and revenue of $895.3 million beat expectations by 3.0% while growing 5.1% year over year. Management also raised full-year guidance for the third consecutive quarter and put a number on its 2027 opportunity for the first time. The central tension is that the beat was larger than the underlying improvement. Adjusted EPS still fell 16.7% from $0.72 a year ago, GAAP EPS slipped to $0.38 from $0.40, and a meaningful part of the upside came from a state supplemental payment accrual rather than core operations.
The quality of the beat deserves scrutiny. Third-quarter adjusted EBITDA of $176.4 million included a $13.4 million accrual from Florida's supplemental payment program, compared with the $5.6 million the company had assumed in guidance. Without that roughly $7.8 million surplus, adjusted EBITDA would have been about flat with the prior year's $173.0 million. The year-over-year EPS decline also reflects a higher tax burden: the tax rate applied to adjustments rose to 24.8% from 19.8%, and the GAAP tax provision jumped to $17.8 million from $1.7 million. On a nine-month basis, adjusted EBITDA is still down to $469.9 million from $509.1 million. Acadia is recovering, but it has not yet returned to its 2025 earnings power.
Beneath the headline, the operating trends did improve. Same-facility revenue grew 5.2%, a clear acceleration from flat reported growth, or 3.2% normalized, in the second quarter. Revenue per patient day rose 4.0%, and same-facility admissions climbed 6.6%. Same-facility adjusted EBITDA increased 6.1% to $228.8 million, outpacing same-facility labor cost growth of 4.3%. The acute segment is doing the heavy lifting: revenue rose 11.3% to $524.8 million and volumes grew 7.5% as new capacity filled. Total adjusted EBITDA grew only 2%, and the gap between those two figures is the de novo drag. Losses at new, acquired, and closed facilities widened to $12.6 million from $4.8 million a year earlier.
That drag is also the core of the forward story. Management now expects about $60 million of incremental EBITDA in 2027 from the 16 acute facilities opened since 2023, with startup losses falling from roughly $45 million to about $10 million. All planned facilities are now open, including the 144-bed Jacksonville-area de novo. Management also said licensure timelines have been shortened, which should speed the ramp. Full-year adjusted EBITDA guidance moved to $615-$625 million from $590-$615 million, and adjusted EPS guidance rose to $1.70-$1.80 from $1.45-$1.60. Capital expenditure guidance was cut again, to $210-$230 million, and net leverage eased to 3.9x from 4.1x. Management said more than $20 million of Florida and Ohio supplemental upside remains excluded from guidance.
Bears still have legitimate ammunition:
- **Commercial payer mix:** fell to 20.9%, about 400 basis points lower year over year and more than 10 points below 2022 levels.
- **Weak segments:** CTC revenue was stuck at $141 million for a second straight quarter, and specialty revenue fell 8.2% on Pennsylvania pressure and closures. The call also cited a New York Medicaid drag.
- **Cash flow:** free cash flow dropped to $47 million from $124 million in the second quarter.
- **Legal overhangs:** government-investigation costs ran about $18 million and the DOJ/SEC matter remains unresolved. A professional and general liability actuarial review is pending in the fourth quarter.
- **Leadership and policy:** the CFO role remains interim, and Medicaid work requirements begin in 2027.
- **Tough 2027 comparisons:** out-of-period supplemental payments of $11 million and $26 million earlier this year will be hard to lap.
Investor sentiment shifted meaningfully, moving from -0.24 at the prior report to +0.12, a swing from mildly negative to modestly positive. Price action has been more restrained. At $32.25, shares are down 2.0% since the open following the July report, though they sit about 24% above the $26.00 200-day moving average. Momentum and AVWAP trend readings are positive while the price trend is neutral. That pattern is consistent with a stock that rerated earlier and has since been consolidating rather than chasing each guidance raise.
The bottom line is that Acadia's quarter strengthened the credibility of its new-facility ramp and same-store recovery, and repeated guidance raises show momentum in execution. However, the size of the beat overstates the improvement: supplemental payments, a weakening commercial mix, and lingering legal and leadership questions mean 2027 still has to prove that the earnings recovery is durable.
Read our earnings preview for Acadia Healthcare Company, Inc.: https://www.earningswhispers.com/article/ACHC/21766
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-13 | |
| Oct-13 | |
| Sep-28 | |
| Sep-25 | |
| Sep-09 | |
| Aug-12 | |
| Jul-31 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 |
