Albemarle Faces A Planned Q3 Step Down As Its Shares Retest The Lows
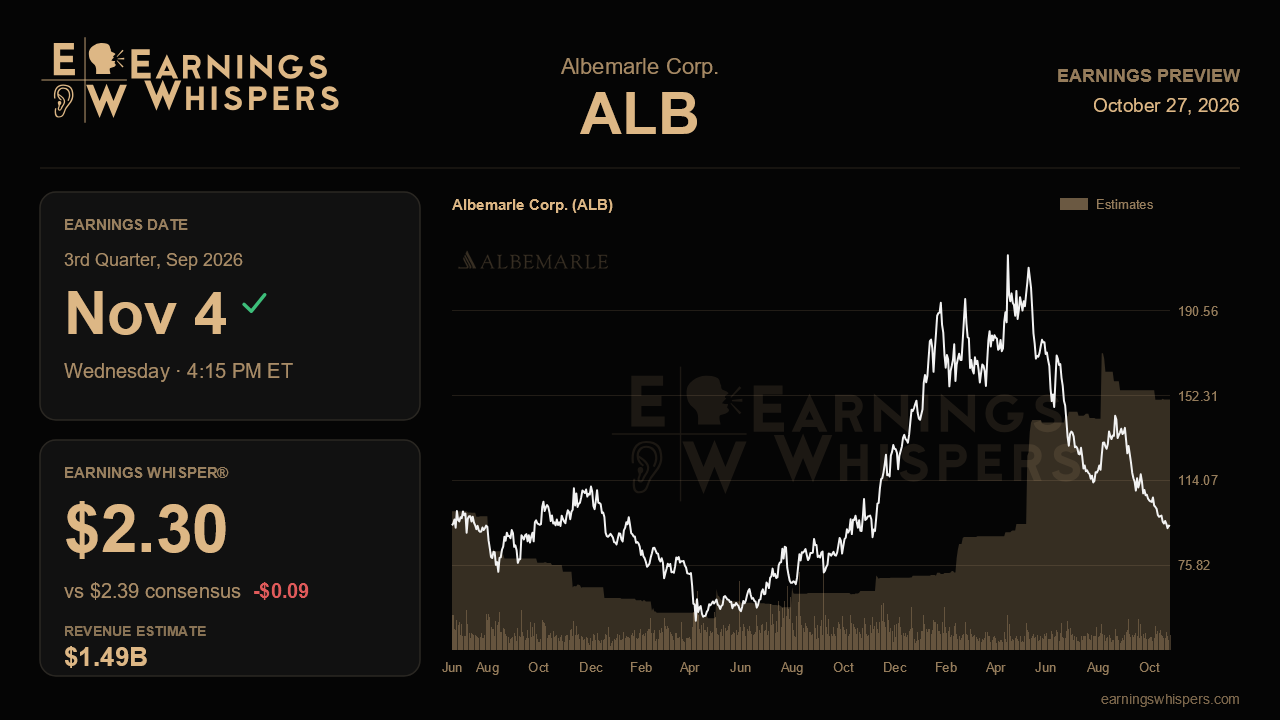
Albemarle heads into its third-quarter report with an unusual setup. Management told investors three months ago that this quarter would be weaker, and the market seems to have treated that warning as something worse than a routine sequential dip. The shares have fallen nearly 27% since the last report, while the S&P 500 was roughly flat. The question for the November 4 release, due after the close, is whether the softness looks like the contained, well-telegraphed pause management described or the start of a broader unwind of the record margins posted in the spring.
The Street expects earnings of $2.39 a share on revenue of about $1.49 billion. Compared with a year ago, when Albemarle lost 19 cents a share on $1.31 billion in sales, that looks like a dramatic turnaround, with revenue up nearly 14%. The more telling comparison is sequential. Last quarter the company earned $3.75 a share on $1.74 billion in revenue, so analysts are already modeling a drop of more than a third in per-share profit. The Earnings Whisper of $2.30 sits slightly below consensus, which suggests that the more skeptical expectations are leaning toward a modest shortfall rather than a beat.
That expected decline lines up with what management laid out. Energy storage revenue, EBITDA and margins were all guided lower for the third quarter. The reasons were lower volumes after the June 9 fire at the Greenbushes CGP3 plant, spot lithium pricing near $20 a kilogram, and a spodumene inventory lag that becomes a drag when prices fall. Specialties were also flagged for a sequential step down as bromine pricing came off its April peak. The CGP3 plant restarted August 1, but full run-rate production is not expected until the first quarter of 2027. Energy storage volume guidance for the year was trimmed to 225,000 to 235,000 tons of LCE. Any update on the ramp, and whether Wodgina's outperformance on ore availability and recoveries is still offsetting the lost tonnage, will show how much of the volume hit has already been absorbed.
The bull case from last quarter rested on more than price. Specialties guidance was raised twice in a row, to $275 million to $325 million of adjusted EBITDA for the year. Cost and productivity savings were tracking toward the high end of the $100 million to $150 million target. Free cash flow reached $638 million, with operating cash conversion above 80%. Management also lifted its demand forecasts for stationary storage and for lithium overall, noting that global consumption was running 45% ahead of the prior year. Continued strong cash conversion, specialties holding near the raised range, and reaffirmed demand estimates would support that story even with weaker headline earnings. A cut to specialties, slipping cost savings, or a larger hit from the $70 million to $90 million of unmitigated Middle East supply chain costs would challenge it. So would a retreat from management's stated expectation of landing at the high end of its $20 per kilogram scenario. Progress on the Salar de Atacama direct lithium extraction permit is a longer-term item, but it gives management a growth story that does not depend on spot prices.
Sentiment has shifted only slightly, from mildly bearish before the last report to essentially neutral now, so the stock's slide reflects price-driven selling more than a change in conviction. At $93.42, the shares sit near their post-earnings low of $91. They trade far below the 200-day moving average of about $152 and well under last quarter's $111.55 floor. A break below that low would signal that the market is pricing in more than the guided softness.
In the end, this report is a credibility test. Albemarle does not need a strong third quarter. It needs one that matches the decline it guided to, along with steady cash generation and an intact full-year framework. If it delivers that, the recent selloff looks like an overreaction to lithium prices. If it cannot, the record second quarter starts to look like the peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| Oct-26 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-11 | |
| Oct-06 | |
| Oct-01 | |
| Sep-17 | |
| Sep-11 | |
| Sep-03 |
