Albemarle Beats A Lowered Bar As Specialties And Cash Shine, But Lithium Earnings Are Already Rolling Over
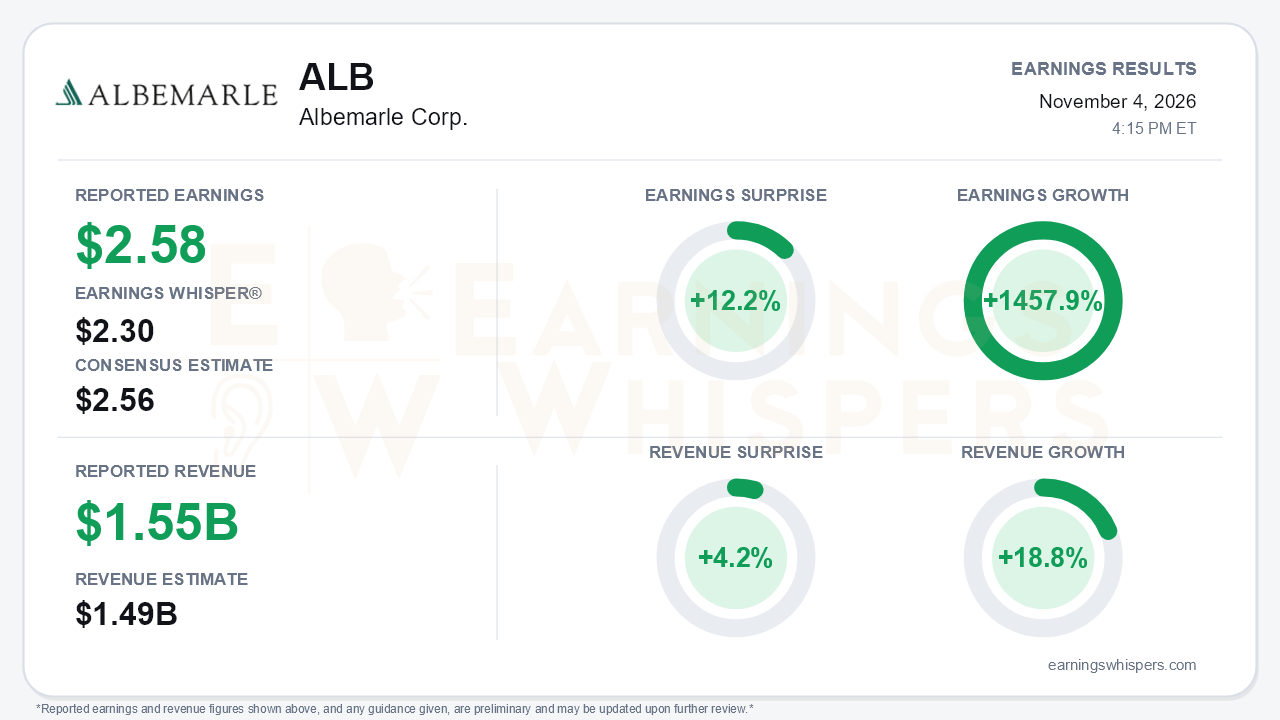
Albemarle (NYSE: ALB) reported adjusted earnings of $2.58 per share on revenue of $1.553 billion for the third quarter. That narrowly topped the $2.56 consensus and cleared the $2.30 Earnings Whisper number, a 12.2% surprise. Revenue beat the $1.49 billion consensus by 4.2% and grew 18.8% year over year. Earnings grew 1457.9%, reflecting a swing from an adjusted loss of $0.19 a year ago, when lithium averaged about $10/kg. The headline is unambiguously strong. The direction is not. Adjusted EBITDA of $646 million was up 186% year over year but down from $858 million in the second quarter. Management guided fourth-quarter Energy Storage sales, EBITDA and margins lower again. That is the central tension: Albemarle beat a quarter that already looks like it sits on the downslope of the lithium price cycle.
The quality of the beat deserves some scrutiny. GAAP diluted EPS was $2.15. The adjusted figure excludes $0.41 of items, including $0.11 of discrete tax charges, $0.08 of consulting costs tied to the cost-savings program, and $0.06 of restructuring connected to idling Kemerton Train 1. The adjusted tax rate was just 5.8%, versus 16.4% reported, which flattered the bottom line. Equity income of $205 million, largely from the Talison joint venture, did much of the work. Energy Storage itself told a price-over-volume story. The realized price nearly doubled to $20.02/kg while volumes fell to 56 kt from a record 69 kt. Margin pressure is already visible: the 41.6% adjusted EBITDA margin trailed the 45.9% nine-month figure. Management attributed the squeeze to high-priced spodumene inventory moving through cost of goods and to higher Chilean commissions.
The call showed the improvements are real, but they sit mostly outside lithium pricing. Specialties adjusted EBITDA guidance was raised for a third straight time, to $350-$375 million. That outlook stood at $170-$230 million at the start of the year. The drivers were bromine pricing and volume, record production at the Jordan Bromine Company joint venture, and cost and productivity savings that now exceed $150 million, the top of the target range. Capital spending guidance was cut again, to $300-$350 million from roughly $500 million and an original $550-$600 million. Some of that comes from resequencing projects rather than pure efficiency. Cash generation was the other standout. Year-to-date free cash flow reached $1.2 billion, debt has fallen to $1.9 billion from more than $3.1 billion at year-end, and net leverage sits near 0.3 times. Management explicitly floated buybacks if growth spending slips.
The forward picture is harder to read. On demand, management noted that global lithium consumption growth accelerated to 48% year to date. Stationary storage now accounts for roughly 30% of demand, and the CGP3 ramp at Greenbushes reached 30 days at nameplate earlier than assumed, keeping the 2027 volume outlook of 240-260 kt intact. Yet spot lithium has slipped to about $14/kg, according to the Q&A, against roughly $20 year to date. Management called that weakness surprising given a tight physical market. The company says the full-year outlook is trending toward the high end of its $20/kg scenario. However, the 2026 volume range of 225-235 kt was merely reaffirmed, and that reaffirmation came in below estimates. Year-end contract renewals with a drift toward Chinese spot business, $70-$90 million of Middle East cost pressure that could carry into 2027, and partly geopolitical bromine pricing give bears legitimate ammunition. So does a leadership change: this was Kent Masters' last call before Rag Udd takes over as CEO on February 1.
The market has been pricing the downslope rather than the beat. Shares have fallen 25.6% since the open after the August report, to $94.97, and trade 36.2% below the 200-day moving average of $148.93. Investor sentiment slipped further into negative territory, from -0.05 to -0.13. That is a moderate deterioration, not a capitulation. The Earnings Whispers trend readings are mixed: momentum is positive, while price and AVWAP trends remain negative.
The bottom line is that Albemarle delivered a clean beat, a fortress-like balance sheet and another Specialties upgrade. The earnings engine, however, is lithium price, and that price is falling while expensive spodumene works through the cost base. Self-help has lowered the company's break-even and improved its optionality. Until spot pricing stabilizes, investors are likely to keep weighing sequential decline more heavily than year-over-year growth.
Read our earnings preview for Albemarle Corp.: https://www.earningswhispers.com/article/ALB/21773
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-01 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-11 | |
| Oct-06 |
