Aflac Heads Into Third Quarter Needing Benefit Ratios To Back Up Its Capital Story
Aflac enters its third-quarter report with two stories pulling in opposite directions. Its balance sheet narrative has rarely looked better, with expanded reinsurance capacity, a portfolio repositioning that should lift investment income and steady buybacks. The insurance engine underneath, however, softened last quarter. US premium growth guidance slipped, Japan's benefit ratio outlook moved to the high end of its range, and a spike in group disability claims pushed US margins the wrong way. This report will show whether those were one-quarter bumps or the start of a slower grind.
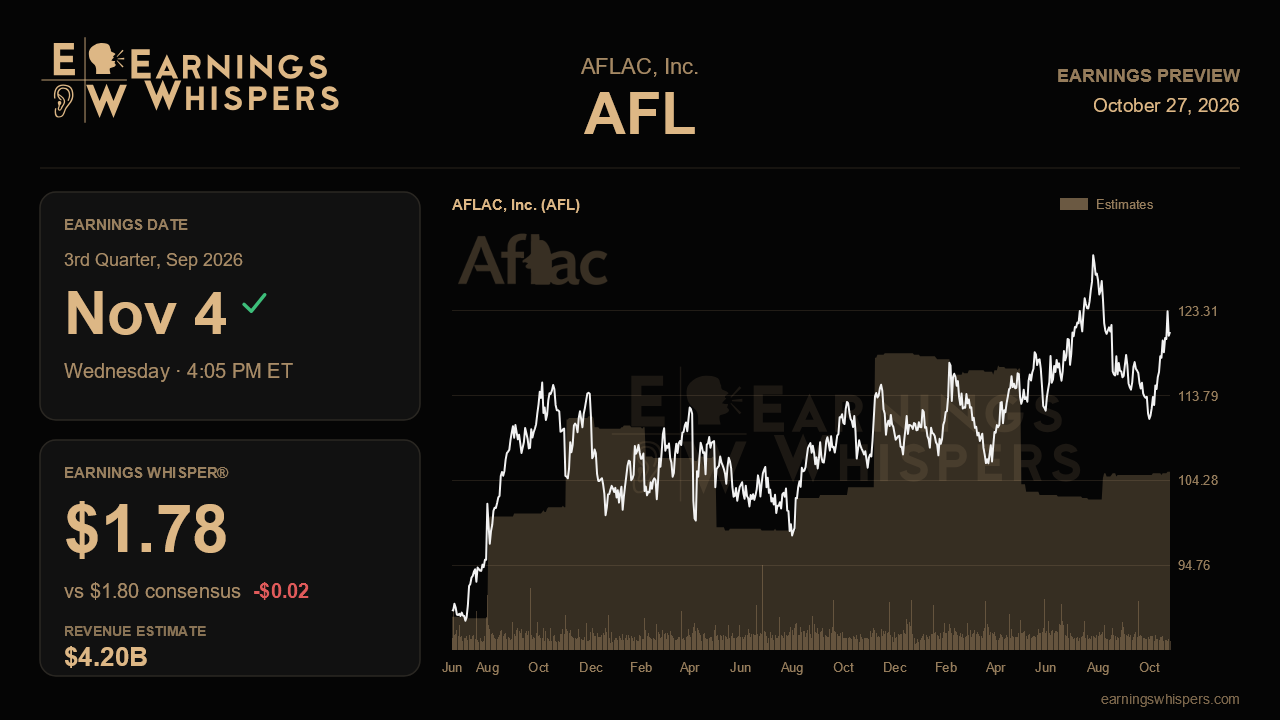
The Street expects earnings of $1.80 a share on revenue of about $4.20 billion. Those figures imply steep year-over-year declines of roughly 28% in earnings and 11% in revenue against a year-ago quarter of $2.49 and $4.74 billion. Readers should be careful with those comparisons, though. Revenue at a Japan-heavy insurer swings with the yen and investment results, and the sequential picture is more useful. Against last quarter's $1.75 and $4.12 billion, the consensus calls for modest improvement rather than deterioration. The Earnings Whisper sits at $1.78, a hair under consensus. That suggests the more informed expectations bar is not elevated, though the gap is too small to read much into.
The most important numbers will be the benefit ratios. In the US, the ratio jumped to 49.5% in the second quarter from 47.2% in the first, driven by higher group disability claims. If the ratio drifts back toward the first-quarter level, management can credibly call that spike noise. Another reading near 50% would raise harder questions about pricing and underwriting in the group book, which has been the fastest-growing part of the US business. In Japan, management now expects the full-year benefit ratio near the top of its 60% to 63% range. The reason is that lapses have shifted from older policies, which release reserves when they end, to newer ones that do not. A third-quarter figure that pushes past the range would signal that persistency pressure is building faster than expected.
Growth deserves equal scrutiny. Management cut its 2026 US net earned premium outlook to just below its 3% to 6% range after earlier pointing to the low end. A second consecutive downgrade would weaken confidence in the US franchise, so holding that framing would count as a win. Strong group and dental and vision sales help, but they need to show up in earned premium. In Japan, sales fell about 6% last quarter against a tough comparison with a major product launch a year earlier. Management described its roughly 80 billion yen full-year sales goal as still possible but clearly a stretch. Any update that quietly retires that goal would be telling.
The offsets are real and should start to become visible. The $4.8 billion switch trade is expected to add more than $50 million in annual net investment income, and early evidence of that lift would support the earnings trajectory. Updates on how much capital the larger internal reinsurance limit can free, and on the growth of external deals like the Japan Post block, could reshape how investors value Aflac's capital generation. Japan's 34.3% pre-tax margin and disciplined expense ratios give the company a cushion if claims stay elevated.
The market has not been generous. Shares are down about 4.5% since the last report, trailing the S&P 500 by nearly four percentage points, though sentiment has improved to modestly bullish from barely positive a quarter ago. At about $121, the stock sits above its 200-day moving average and in the upper half of its post-earnings range, but still roughly 5% below the $127 high. Ultimately, the report will turn on whether underwriting margins stabilize. If they do, the capital story can carry the stock. If they slip again, buybacks and reinsurance creativity will struggle to mask a slowing core business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-06 | |
| Sep-30 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 | |
| Sep-16 | |
| Sep-10 | |
| Sep-09 | |
| Sep-05 |
