Aflac's 36.5% Beat Leans On A $0.71 Assumption Unlock As Margin Guidance Rises But Japan Sales And Capital Buffers Soften
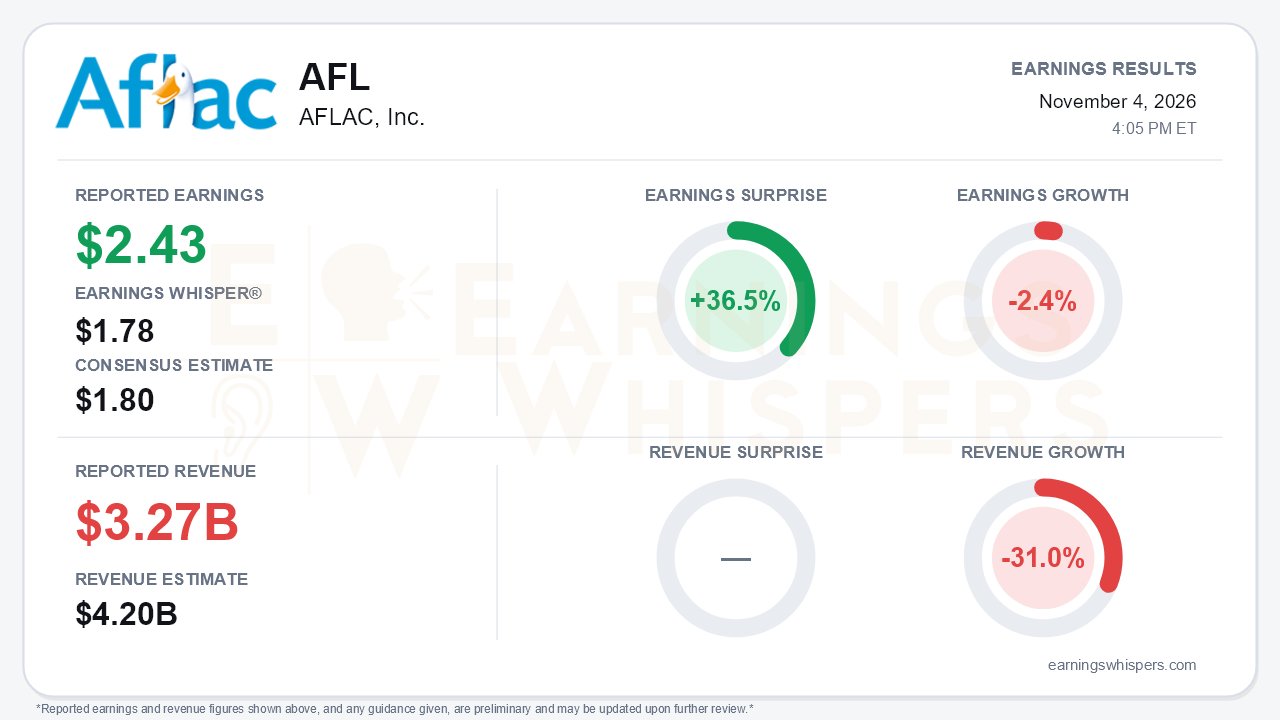
Aflac (NYSE: AFL) posted adjusted earnings of $2.43 per share for the third quarter, far above the $1.80 consensus and the $1.78 Earnings Whisper number, a 36.5% surprise. Even so, earnings fell 2.4% from a year ago, and revenue of $3.271 billion missed the $4.20 billion consensus by 22.1% and dropped 31.0% year over year. The size of the beat matters less than its source. Management said the annual actuarial assumption unlock added $447 million pre-tax, or $0.71 per share. Remove that, and the underlying run-rate looks roughly in line with expectations rather than far ahead of them. The quality of the beat deserves scrutiny. The more durable news is that the unlock lowers future net premium ratios, and management raised margin guidance in both major segments.
The GAAP picture looks very different. Net earnings fell to $0.61 per share from $3.08. The main cause was $1.1 billion of net investment losses, including $842 million from sales and redemptions tied to a strategic portfolio repositioning and $102 million of credit-loss provisions. Results also included a $51 million tax valuation allowance. Those realized losses run through total revenue, which explains the steep revenue decline and miss. They are not a collapse in premiums. Underlying growth, however, is clearly fading. Adjusted EPS excluding currency fell 1.2%, after rising 1.1% in the second quarter and 6.6% in the first. Buybacks are doing much of the per-share work: Aflac repurchased $804 million of stock, and shares outstanding are down 5.7% from a year ago.
The two segments are moving in opposite directions:
- **Aflac U.S.** had its strongest operating quarter of the year. Net earned premiums rose 3.3%, up from 2.3% in the second quarter. Sales grew 3.5%, with dental and vision sales up 67%. Persistency improved to 79.7%, and the pretax margin widened to 27.7% from 21.7%, helped by higher remeasurement gains and lower expenses.
- **Aflac Japan** told a weaker story. Yen premiums fell 2.0%, reflecting both external and internal reinsurance transactions and paid-up policies. Pretax adjusted earnings fell 15.2% in yen. The benefit ratio jumped to 49.2% from 39.3% as prior-year remeasurement gains were not repeated. A cybersecurity incident cost $40 million, or $0.06 per share, added about 180 basis points to the expense ratio, and forced a pause in direct mail and outbound calling.
- **Japan sales** fell 4%. Year-to-date growth slowed to 3%, from 7% at midyear and 25.5% in the first quarter. Management also dropped the ¥80 billion sales aspiration it had cited earlier in the year and now commits only to exceeding 2025.
The forward catalysts are real and largely self-generated:
- **Japan guidance:** the pretax margin is now expected above the 33%–36% range, with the benefit ratio slightly below 60%–63%. In the second quarter, management had pointed to the high end of that range.
- **U.S. guidance:** the benefit ratio is expected below 48%–52% and the pretax margin above 17%–20%.
- **Reinsurance cession:** Aflac Japan ceded roughly ¥500 billion of FSA reserves to Aflac Re Bermuda, raising the share ceded to 15% and releasing about $1 billion of capital. Management's target remains 30%.
- **Investment income:** another $2.3 billion switch into Japanese government bonds should add more than $30 million of net investment income.
- **Tsumitasu:** management sounded more emphatic about significantly growing the savings-type product as yen rates rise.
Bears have legitimate ammunition, though:
- Unencumbered liquidity fell to $2.7 billion from $3.3 billion.
- Combined RBC slipped to about 575% from above 600%.
- Adjusted book value excluding currency fell 6.4% to $40.73 per share.
- Reserve builds continued on commercial real estate and middle-market loans.
- Management conceded that future switch trades will be harder to replicate.
Investors were not leaning heavily either way before the release. Earnings Whispers sentiment remained modestly positive but eased slightly, from 0.10 to 0.08. The shares, at $125.30, are down 1.1% from the open after the August report, so the stock has essentially gone sideways over the quarter. It still trades about 8% above its 200-day moving average of $116.07. Price and AVWAP trend readings remain positive, while sequential growth and momentum are neutral. That fits a business whose margins are improving faster than its top line.
The bottom line is that Aflac delivered a headline beat built largely on actuarial and capital engineering rather than on accelerating demand. The unlock, the higher margin guidance and the Bermuda cession credibly support profitability and capital deployment. The U.S. business is quietly gaining momentum. Against that, Japan sales have stalled, currency-neutral EPS growth has turned negative, and liquidity and capital ratios have tightened. The setup now hinges on whether Japan sales recover after the cyber disruption and whether margin gains can keep outrunning a shrinking premium base.
Read our earnings preview for AFLAC, Inc.: https://www.earningswhispers.com/article/AFL/21771
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-06 | |
| Sep-30 | |
| Sep-23 | |
| Sep-22 |
