Ardent Health's Self-Help Story Faces A Volume Test As New CEO Defends EBITDA Guide
Ardent Health enters its third-quarter report with a simple but uncomfortable question hanging over it: can cost cuts and better payer contracts keep covering for softer patient demand? Last quarter, management held its full-year adjusted EBITDA outlook of $485 million to $535 million even as surgeries and admissions slipped. That was only possible because savings and pricing wins plugged a roughly $25 million volume hole. This report will show whether that patch is holding or whether demand has to recover on its own.
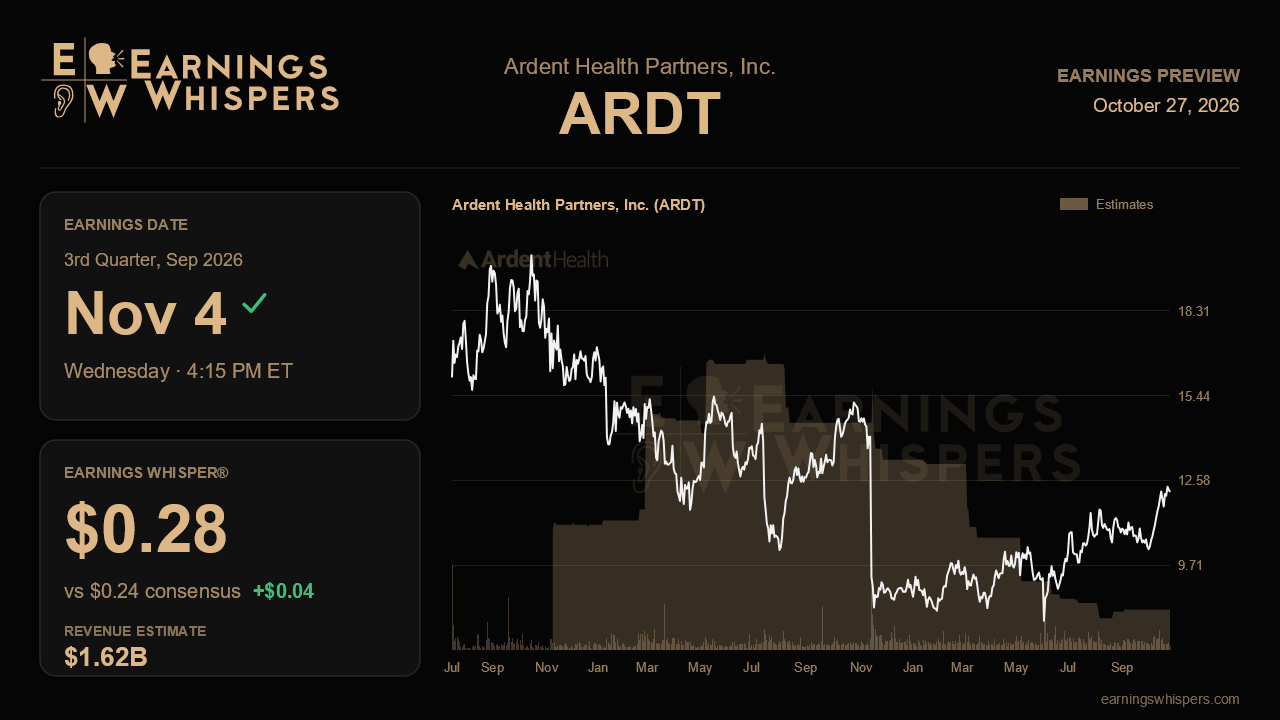
The Street is braced for a sharply lower bottom line. Consensus calls for earnings of $0.24 per share, down about 54% from $0.52 a year ago, on revenue of $1.62 billion, up a modest 2.7%. The year-ago quarter carried unusual items, including a large New Mexico malpractice reserve and a revenue accounting change, so the headline decline overstates the deterioration. Still, revenue flat with the prior quarter's $1.62 billion signals a business treading water on the top line. The Earnings Whisper of $0.28 sits above consensus, a hint that some investors expect the cost program to deliver a little more than published models assume. The full-year revenue consensus of $6.46 billion sits near the bottom of management's reaffirmed $6.4 billion to $6.7 billion range. That matches the company's own signal last quarter that revenue was leaning toward the low end.
The EBITDA math frames the stakes. Ardent generated $124 million in the first quarter and $115 million in the second, so reaching even the low end of guidance requires roughly $123 million per quarter in the back half, and the midpoint implies closer to $135 million. A third-quarter figure that rebounds above the second quarter would validate the self-help narrative. Another step down would put pressure on the guide heading into the final quarter.
Volume is the swing factor. Surgeries fell 2.9% and admissions 1.0% in the second quarter, with April and May notably weak before a June and July recovery. Management conceded that July still trailed original plans. Investors need evidence that the rebound carried through September, particularly in inpatient surgery, which declined more steeply. Exchange admissions, down 8% with patients drifting toward self-pay, are another pressure point, and the company has already flagged a $35 million exchange headwind. Further erosion in high-deductible and exchange populations would suggest the consumer pressure is broadening rather than fading. Revenue per adjusted admission, which fell 3.9% on lower acuity, also needs to stabilize.
On the controllables side, the bar is high because management keeps raising it. The impact savings target has climbed from $40 million to $55 million to more than $70 million, helped by a mid-year delayering expected to save $15 million to $20 million this year. Confirmation that those savings are showing up in salaries and benefits, alongside continued restraint in contract labor, would reinforce new CEO Dave Caspers' execution message. Updates on the June 1 payer renewal, which management said adds $5 million to $10 million this year, and on whether similar deals are lining up in other markets, would matter for 2027 as well.
The market has leaned optimistic in price if not in mood. Shares are up 5.8% since the last report, beating the S&P 500 by more than seven points, and at $12.18 they sit well above the 200-day average and within about 2% of the post-earnings high of $12.47, testing a breakout. Sentiment, however, has turned more bearish than it was before the prior report. That split leaves room for a reaction in either direction. Ultimately, the narrative stays intact if volumes show a durable recovery while savings accumulate; if demand stays soft and cost cuts are again doing all the work, the reaffirmed EBITDA range will look increasingly hard to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Sep-29 | |
| Sep-15 | |
| Sep-14 | |
| Sep-02 | |
| Aug-27 | |
| Aug-11 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-23 | |
| Jul-17 | |
| Jun-04 |
