Ardent Health Beats On Cost Discipline And Lifts EBITDA Floor, But Flat Pricing And Soft Surgeries Keep Revenue Pinned Low
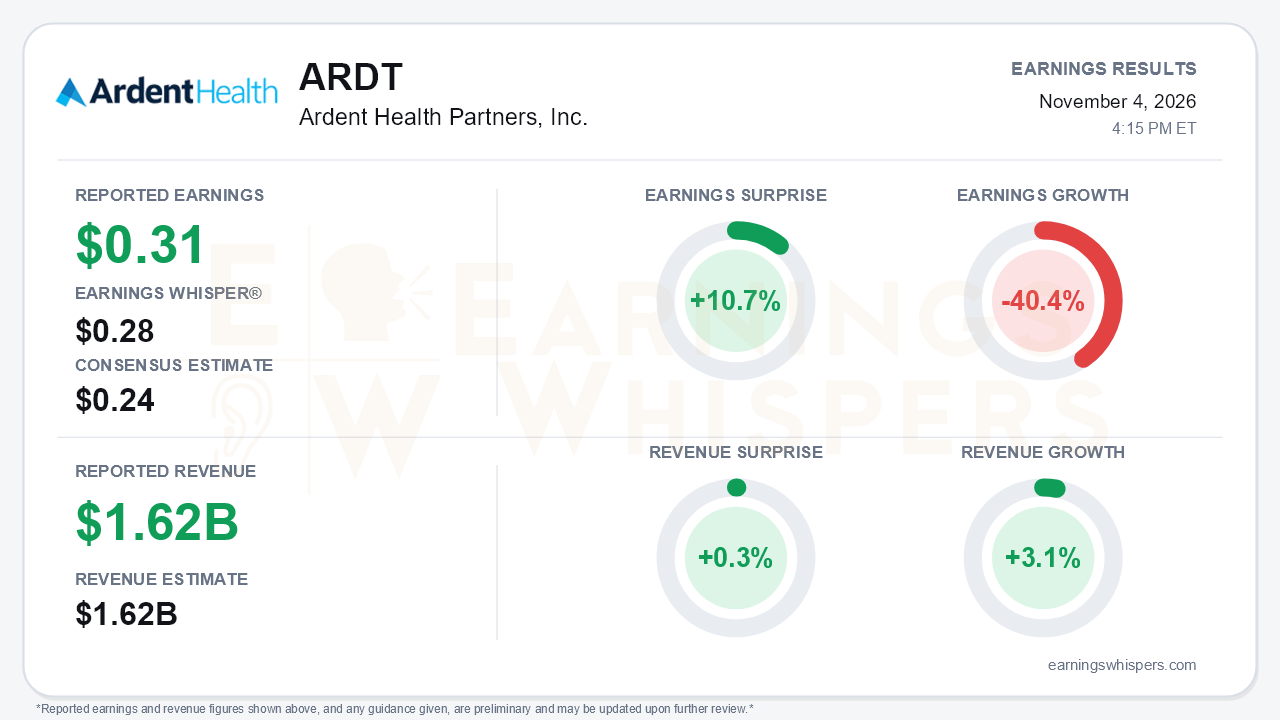
Ardent Health delivered the quarter it needed to shift its narrative from defending guidance to raising it. The hospital operator earned $0.31 per share on revenue of $1.625 billion, ahead of the $0.24 consensus and the $0.28 Earnings Whisper number for a 10.7% earnings surprise. Revenue edged past the $1.62 billion consensus by 0.3% and grew 3.1% year over year. Earnings Whispers' normalized comparison shows earnings down 40.4% year over year. That differs sharply from the GAAP presentation, where Ardent swung from a net loss of $23 million, or $0.17 per share, to net income of $45 million. Investors should note that the two figures rest on different comparison bases. The central takeaway is that this was a cost story far more than a revenue story. Management raised the low end of 2026 adjusted EBITDA guidance to $500 million from $485 million while again steering revenue toward the bottom of its $6.4-$6.7 billion range.
The quality of the beat deserves scrutiny, and it largely holds up. Adjusted EBITDA reached $138 million, up from $124 million in Q1 and $115 million in Q2, and it topped the prior guide to 'approach' $124 million. The year-over-year jump from $45 million looks dramatic, but the 2.9% margin in last year's third quarter was a depressed comparison. The more telling numbers sit in the expense lines. Salaries and benefits fell 4.3% to 39.9% of revenue, a 300-basis-point improvement, after rising 0.7% in Q2. Contract labor dropped 45%, and other operating expenses fell to $163 million from $199 million. Professional fees remain a drag, still growing 7.4%, though that rate slowed from 12.9% in Q1 and 10.4% in Q2. The IMPACT efficiency program, whose target has been raised from $40 million to $55 million to at least $70 million over successive calls, is clearly doing the heavy lifting. Restructuring and ERP conversion costs of roughly $11 million were excluded from adjusted EBITDA.
Volumes improved, but the headline masks a weaker underlying mix. Adjusted admissions rose 2.9%, accelerating from 2.5% in Q2. Emergency room visits grew 1.7% after declining in the first half, and admissions turned slightly positive. Surgeries, however, still fell 1.9%, and inpatient surgeries declined 5.0%. Management attributed about half of the surgical decline to service-line rationalization. Exchange admissions fell 7%, non-exchange commercial volume remains down, and denials stay elevated. Net patient service revenue per adjusted admission rose just 0.7%. That pricing performance explains why better volumes and a guidance raise still leave revenue biased low. A delayed $37 million New Mexico supplemental payment adds to the revenue uncertainty.
The forward catalysts are more concrete than they were a quarter ago. Ardent agreed to transfer its Kansas hospital to its joint venture partner at roughly 11 times EBITDA. The deal is expected to close in the fourth quarter and add about 40 basis points of margin. Management quantified a $20-$25 million IMPACT wrap into 2027 and said payer contracts are 85% complete for 2027 and 75% for 2028. It also called the finalized OPPS rule a modest tailwind and described a growing list of distressed acquisition targets. GAAP EPS guidance rose to $0.93-$1.18 from $0.78-$1.15. Capex guidance was trimmed by $15 million, and the buyback authorization was increased by $25 million. Bears have legitimate ammunition, though. Management flagged Medicaid work requirements and continued exchange attrition as 2027 headwinds without quantifying either. It also acknowledged more contentious payer negotiations and potential friction with JV partners over the pace of cost cuts. New CEO Dave Caspers' answers were often qualitative.
Sentiment and price action suggest investors have begun to give the turnaround some credit without embracing it. Earnings Whispers investor sentiment remained negative but improved meaningfully, rising to -0.14 from -0.25 at the prior report. Shares at $12.99 are up 12.9% since the open following the August report and sit roughly 29.5% above the 200-day moving average of $10.03. Price and AVWAP trend readings are positive, while sequential growth and momentum are neutral. That pattern fits a stock that has re-rated on execution while the growth picture remains unresolved.
The bottom line is that Ardent proved it can expand margins through cost discipline even with soft pricing and negative surgical volume. The raised EBITDA floor, the accretive Kansas exit and the quantified 2027 cost carryover make the earnings story more credible than it was in August. The open question is revenue quality. With commercial and exchange pressure persisting and 2027 policy headwinds unquantified, the next leg depends on whether volume gains begin translating into pricing rather than just cost savings.
Read our earnings preview for Ardent Health Partners, Inc.: https://www.earningswhispers.com/article/ARDT/21784
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Sep-29 | |
| Sep-15 | |
| Sep-14 | |
| Sep-02 | |
| Aug-27 | |
| Aug-11 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-23 |
