APA Nears Breakout As Q3 Tests Whether Its Leaner Permian Machine Holds Up
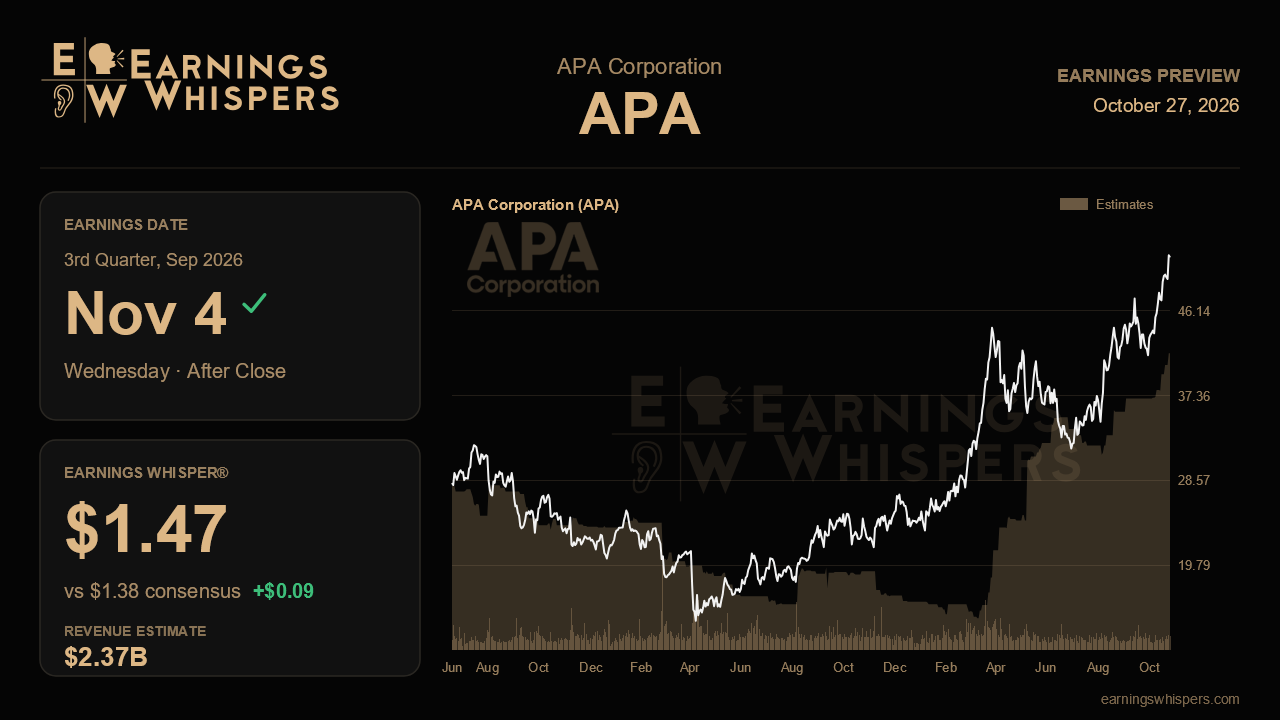
APA heads into its third-quarter report with a stock that has nearly matched its operating momentum. Shares have climbed more than 41% since the last report while the S&P 500 slipped slightly. Last quarter management raised guidance across production, costs and free cash flow, and settled the question of how much cash would go back to shareholders. The question now is whether the first quarter of a four-rig Permian program shows that the efficiency story is real, or whether the market has paid in advance for results that still have to arrive.
Wall Street expects earnings of $1.38 per share on revenue of about $2.37 billion. That would be a 48% jump in earnings from a year ago and 17% revenue growth, which is strong by any measure. The sequential picture is less flattering. Revenue is expected to hold roughly steady with the second quarter's $2.40 billion, yet the EPS estimate sits well below last quarter's $1.89. One reason may be the higher deferred tax expense management flagged as U.S. net operating losses get used up faster. That charge is non-cash, but it can still weigh on reported earnings. The whisper number of $1.47 sits meaningfully above consensus, which suggests the people closest to the stock expect another clean beat rather than a simple match.
The operating test starts in the Permian. Management lifted its oil target to 123,000 barrels per day, the third straight increase, while cutting the rig count to four for the second half and holding the $1.3 billion budget. For context, the company once assumed it would need eight rigs and $1.7 billion to sustain about 120,000 barrels a day. Volumes holding near 123,000 with fewer rigs would confirm the capital-efficiency story. Any softness would suggest the rig cut went a step too far. The same logic applies to costs. The run-rate savings target has risen in stages from roughly $400 million to $500 million exiting 2026, and full-year lease operating expense guidance was trimmed to $1.5 billion. Unit costs should show that progress even as diesel and service inflation eat into part of the savings.
Cash is where the narrative either compounds or stalls. First-half free cash flow topped $1.2 billion, more than any prior full year, and the full-year outlook rose to about $2.3 billion. Management promised significant buybacks in the second half under its pledge to return at least 60% of free cash flow, with net debt heading toward $3.3 billion by year-end and the $3 billion target pulled into 2027. A visible step-up in repurchases this quarter would show the commitment is being kept. On the softer side, gas-trading cash flow guidance eased to about $950 million because of tighter Waha spreads, and Egypt gas was trimmed to 535 million cubic feet a day. Management says both effects are largely neutral for free cash flow. Further cuts in either would test that claim.
Sentiment has drifted slightly more bearish than before the last report, an odd backdrop for a stock trading about 39% above its 200-day moving average. The shares sit within about 1.5% of their post-earnings high of $52.39, so they are effectively testing a breakout. A rally of this size leaves little room for an ordinary quarter, even if the numbers themselves are fine.
The central issue is whether APA can show that 123,000 barrels a day, lower costs and accelerating buybacks can all happen at once with only four rigs running. If it can, the steady stream of guidance raises looks durable and the 2027 exploration program in Alaska, Suriname and Uruguay becomes upside rather than a distraction. If production or shareholder returns lag, investors may decide the stock got ahead of the story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-23 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 | |
| Sep-23 | |
| Sep-18 | |
| Sep-16 | |
| Sep-15 | |
| Sep-01 | |
| Aug-25 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 |
