APA Beats Big And Raises Guidance For A Third Straight Quarter, But A Heavier 2027 Spending Plan Tests The Cash-Return Story
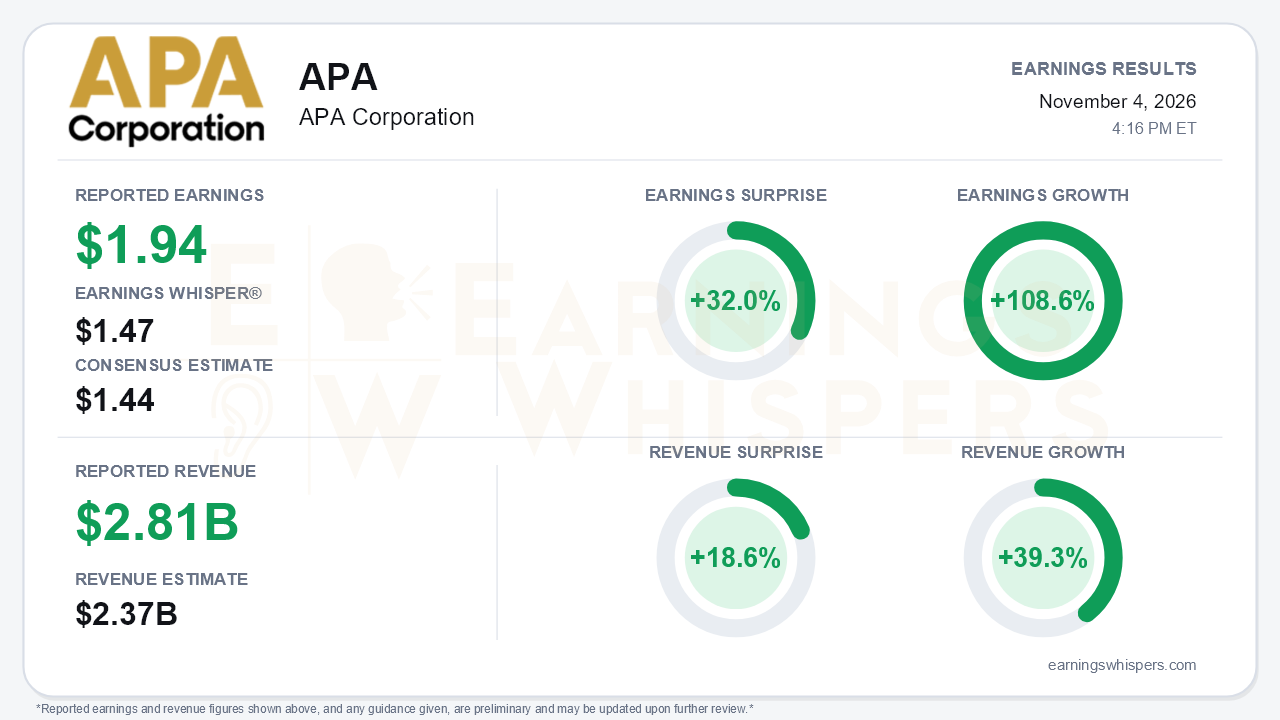
APA Corporation delivered a clear beat in the third quarter. Earnings of $1.94 per share topped the $1.44 consensus by 32.0% and cleared the $1.47 Earnings Whisper number by a wide margin. Revenue of $2.812 billion beat the $2.37 billion estimate by 18.6%. Year-over-year growth was strong, with earnings up 108.6% and revenue up 39.3%. The more important development is that management raised guidance for the third consecutive quarter, turning APA from a cost-cutting story into a cash-return story. The central tension is that the preliminary 2027 plan asks investors to fund more spending and more exploration for production that is only flat.
The press release itself contained no financial detail; it simply directed investors to the company's website ahead of the November 5 call. The substance came from the call, and the quality of the quarter holds up under scrutiny:
- Full-year 2026 free cash flow guidance rose to $2.9 billion, up from $2.3 billion last quarter and $2.2 billion in Q1.
- Third-quarter free cash flow was $699 million, bringing the year-to-date total above $1.9 billion.
- U.S. oil production came in at 128 Mb/d, ahead of guidance, and full-year U.S. oil guidance moved up again to 124 Mb/d.
- Egypt gross gas reached 542 MMcf/d, above the 535 target that had been lowered in Q2, and realizations rose to $4.34/Mcf.
- Gas trading pre-tax cash flow guidance for 2026 was lifted to about $1.1 billion.
- Cumulative annualized savings rose to roughly $680 million including interest, and the company remains on track for a $500 million run-rate exit.
Capital allocation is where the quarter changed most visibly. Shareholder returns jumped to $537 million in Q3, compared with $189 million in Q2 and $88 million in Q1. Management expects roughly $650 million more in buybacks by year-end and says the share count is down about 5%. Net debt fell to $3.2 billion from $4.1 billion at Q1. As a result, the $3 billion net debt target now looks reachable around year-end 2026 rather than in 2027, as suggested on the Q2 call, and management set a new $2 billion goal. Accelerating buybacks while pulling forward deleveraging is a combination that turnaround skeptics were not positioned for.
The forward picture is more nuanced, and bears have legitimate ammunition:
- **Capex is rising without volume growth.** Preliminary 2027 upstream capex of roughly $2.5 billion compares with about $2.1 billion for 2026. It embeds mid-single-digit Permian cost inflation, while U.S. and Egypt production are guided only flat.
- **Gas trading is expected to step down.** The 2027 outlook of about $950 million is far above the roughly $400 million view given in Q1, but it is lower than 2026. Management noted that current prices point to the mid-to-high $800 millions as Waha basis tightens.
- **Smaller cost items moved the wrong way.** LOE guidance rose $25 million on stock-based compensation, G&A ran at $112 million, and 2026 capex rose $30 million to fund Permian frac acceleration.
- **Egypt carries both contract and geopolitical risk.** Adjusted volumes ran slightly below guidance because higher oil prices reduce APA's share under its production-sharing contracts, and Middle East and Red Sea exposure persists.
The offset is an exploration slate that has moved from planning to execution. Exploration returns to 10-15% of upstream capital, and the program includes:
- four cost-recoverable Suriname wells inside the Grand Morgue development area, with potential to extend plateau or support a second development;
- the Hungry Horse appraisal and Chinook exploration wells in Alaska this winter;
- a contracted Noble rig for Uruguay's OFF-6, spudding in late 2027 with ENI carrying most of the cost.
In the Permian, APA is adding two rigs around the turn of the year and tilting activity toward the Delaware.
The market had already rewarded much of this improvement before the call. Shares closed at $44.49 on report day, up 21.7% from the $36.56 open following the August report and 17.1% above the $37.98 200-day moving average. Investor sentiment, however, stayed negative and slipped modestly, from -0.08 to -0.14. Investors are participating in the rally without fully embracing it, likely reflecting skepticism about commodity-driven upside and the durability of gas trading income. The Earnings Whispers trend readings are mostly positive on price, momentum and AVWAP, though the sequential-growth trend remains negative. That mix fits a stock where cash generation is strong but forward growth is less clear.
The bottom line is that APA delivered a high-quality beat backed by real balance-sheet and buyback progress, and management credibly raised nearly every cash-flow metric that matters for 2026. The debate now shifts to 2027. Higher capex, Permian inflation, flat production and lower gas trading income mean the next leg of the story depends on exploration results and cost discipline rather than continued guidance raises. With shares well above their 200-day average and sentiment still cautious, the setup is more complicated than the 32% surprise implies.
Read our earnings preview for APA Corporation: https://www.earningswhispers.com/article/APA/21781
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-27 | |
| Oct-23 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 | |
| Sep-23 | |
| Sep-18 | |
| Sep-16 | |
| Sep-15 |
