Amplitude's 70% Rally Raises The Bar For AI Momentum And Margin Discipline
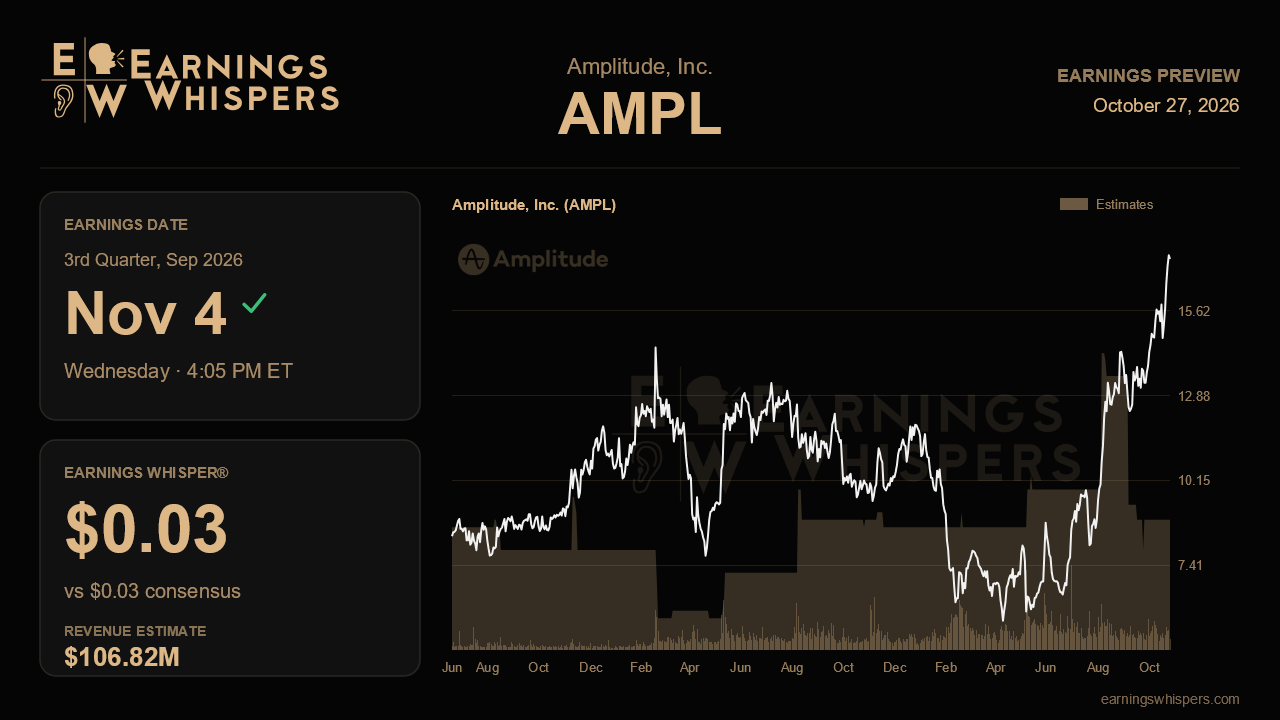
Amplitude enters its third-quarter report with something it has not had in a while: a market that believes the turnaround. Shares have climbed roughly 70% since the company last reported, while the S&P 500 slipped slightly, as investors embraced accelerating growth, a second straight guidance raise and a sharper AI-native pitch. That rally changes the assignment. Last quarter Amplitude had to prove it could grow faster. This quarter it has to show the acceleration is durable enough to justify a stock that now trades nearly double its 200-day moving average.
The Street is looking for non-GAAP earnings of $0.03 a share on revenue of about $106.8 million, which would be growth of roughly 20.6% from the year-ago quarter. That sits squarely at the midpoint of management's $105.6 million to $108.0 million revenue range, while the EPS estimate lines up with the top of the $0.02 to $0.03 guide. The Earnings Whisper matches consensus at $0.03, so there is no hidden bar above the published numbers. Still, analysts are not leaning on the company here. Amplitude has typically cleared its own targets, and a revenue print merely in line with the midpoint would likely feel underwhelming after the run in the shares.
The growth rate itself is the first thing to examine. Second-quarter revenue rose 21%, up from 17% in each of the prior few quarters, helped by the Statsig acquisition, and annual recurring revenue reached $410 million, up 22%. Holding growth near that level in the third quarter would confirm the step-up is real rather than a one-quarter lift. Management's full-year outlook of $407.2 million to $411.2 million already implies some deceleration in the fourth quarter, so commentary on whether that cushion is conservative will matter as much as the quarter itself. Remaining performance obligations, which grew 35% last quarter with longer-dated commitments up 47%, offer a useful read on whether new pricing is extending contract duration as claimed.
The less comfortable part of the story is gross margin. It fell to 71% last quarter from 75% in the first quarter and the high 70s before that, as AI inference costs rose and Statsig's lower-margin hosting entered the mix. Management did not promise a rebound; it said margins should settle in the low 70s and argued that leaner sales, marketing and administrative spending would compensate. That makes operating expenses the real test. Evidence that the company is tracking toward its raised operating income guide of $6.3 million to $9.3 million would validate the trade. Another leg down in gross margin, or opex that fails to shrink as a share of revenue, would challenge it directly.
Expansion within the existing base is the other swing factor. Pro forma net dollar retention slipped to 105% from 106%, far below the company's long-term 115% goal, and the chief executive admitted that sales teams have been slow to make customers aware of Statsig, the Wave recommendation engine and other new modules. Improvement in retention, further growth in the 28% of ARR on new pricing, and progress in the cohort of more than 40 AI-native customers paying over $100,000 annually would suggest those enablement gaps are closing.
Sentiment has warmed markedly, moving from modestly bullish ahead of the last report to clearly bullish now, and the stock sits just below its post-earnings high of $17.72, testing a potential breakout. That combination leaves little room for a muddled quarter. The central question is whether Amplitude can sustain roughly 20% growth while proving that its lower gross margin structure still produces expanding profits. If both hold, the rally has a foundation. If either cracks, the market may decide it paid too early.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Oct-14 | |
| Sep-28 | |
| Sep-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Jul-15 | |
| May-27 | |
| May-24 | |
| May-12 |
