Amplitude Accelerates To 25% Growth And Raises Guidance Again, But AI Costs Keep Squeezing Gross Margin
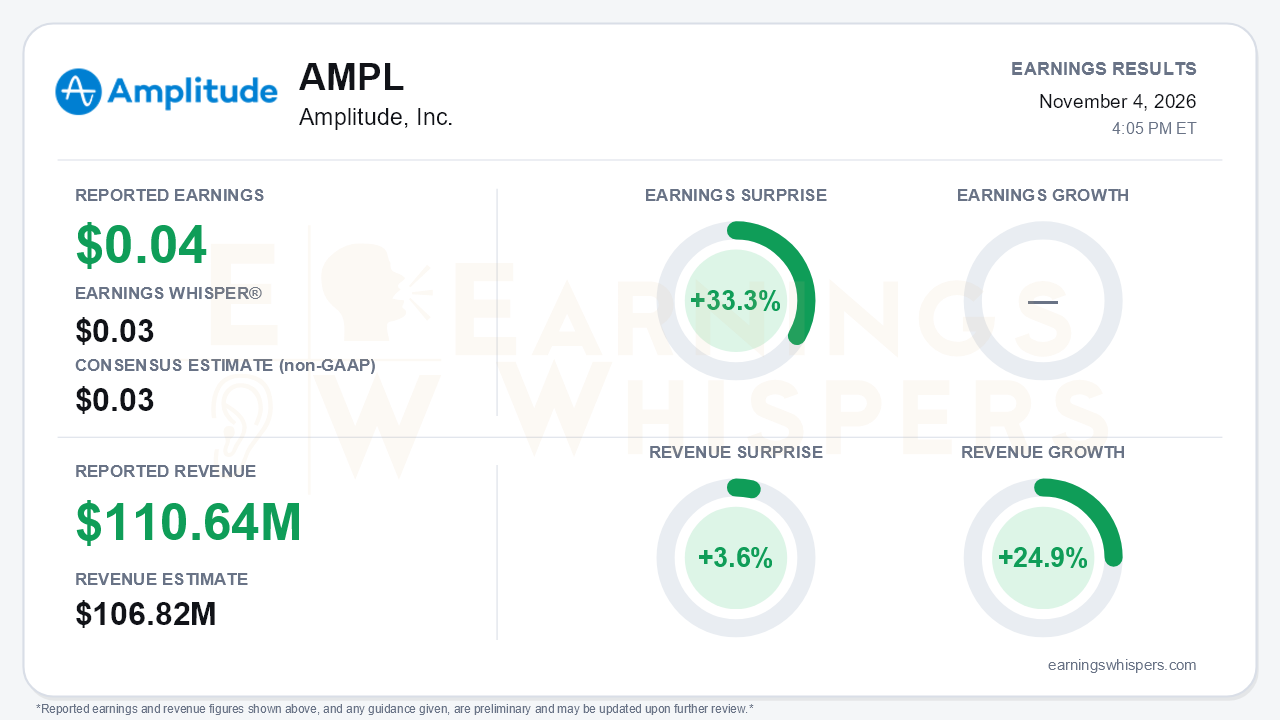
Amplitude (NASDAQ: AMPL) delivered the kind of quarter that changes how a stock is perceived. Non-GAAP earnings of $0.04 per share beat the $0.03 consensus and the $0.03 Earnings Whisper number by 33.3%, doubling the $0.02 earned a year earlier. Revenue of $110.64 million topped the $106.82 million consensus by 3.6% and grew 24.9% year over year. The more important story is acceleration. Revenue growth has stepped up from 17% in the fourth quarter of 2025 and the first quarter to 21% in the second quarter and 25% now. ARR growth followed the same path, reaching 24% at $431 million. Management also raised its full-year revenue outlook for the fourth time, to $415.8 million to $418.2 million. The central tension is that growth is being bought partly with gross margin, because the AI products driving the reacceleration cost more to run.
The operating leverage is real, but it does not come from the cost of delivering the product. Non-GAAP operating income reached a record $5.7 million, a 5.1% margin, up from 0.6% a year ago and well above the $2.5 million to $4.5 million guide. That improvement came almost entirely from sales and marketing. Non-GAAP S&M spending was essentially flat year over year in dollars and fell to 33.8% of revenue from 42.9%. Meanwhile, cost of revenue jumped from $23.1 million to $36.3 million. Non-GAAP gross margin fell to 69.6% from 75.9% a year ago, extending a slide that began at roughly 77% in the fourth quarter of 2025. On a GAAP basis, the net loss widened slightly to $(0.19) per share from $(0.18), helped by a lower share count after $89.5 million of buybacks this year. Stock-based compensation of $28.8 million still dwarfs non-GAAP profit, so the quality of the profitability inflection deserves some scrutiny.
The call supported a credible demand story:
- **Organic ARR adds:** Net new ARR was $21 million, of which $15 million was organic, the strongest organic add management cited. That compares with roughly $19 million in the second quarter and $9 million in the first.
- **Large customers:** Customers paying $100,000 or more rose 31% to 855.
- **Multi-product adoption:** Multi-product customers now represent 81% of ARR.
- **Upsell:** Management said upsell has turned positive as utilization exceeds 90% of entitlements.
- **New pricing:** Over 90% of third-quarter transactions closed on the new pricing, which already covers 38% of ARR and is expected to exceed 50% by year-end.
- **Sales capacity:** The CFO is weighing additions to sales capacity for fiscal 2027 for the first time, because pipeline is outrunning the team.
The catalyst slate is unusually dense. Agent Analytics, generally available since August, gathered more than 125 customers in roughly a month. Wave launches broadly the week after the call, and management suggested it could lift existing contracts by 50% to 100%. Investors should treat that range as aspiration rather than forecast, since management acknowledged Wave requires a hands-on, go-deep adoption motion and monetization timing is uncertain. Statsig founder Vijay Raji, now CTO of Applications at OpenAI, joins the board. A long-term Google hosting contract for the Statsig environment is meant to ease gross-margin pressure.
Bears still have legitimate ammunition:
- **Retention:** Reported NRR is stuck at 103%, and pro forma NRR has held at 105% for a second quarter. That makes the expansion narrative look more promised than proven.
- **Backlog:** RPO growth slowed to 27% from 35%, and long-term RPO growth slowed to 24% from 47%.
- **Q4 deceleration:** The fourth-quarter revenue guide of $110.8 million to $113.2 million implies growth easing to about 23%.
- **Visibility:** Discontinuing the Statsig ARR breakout will reduce transparency.
- **Cash flow:** Free cash flow of $5.8 million was down sharply from $23.7 million in the second quarter, though that is likely seasonal.
- **Security:** Customer scrutiny of security is rising after recent supply-chain incidents.
The market setup is more complicated than the surprise implies, because investors had already priced in a lot. Shares rose 65.7% from the $10.16 open after the August report to $16.84 heading into this release. That leaves the stock about 73% above its 200-day moving average and just 5.6% below the 52-week high of $17.84 set on October 28. Earnings Whispers investor sentiment rose meaningfully, from 0.17 to 0.41, moving from mildly positive to clearly constructive. Most of the internal trend readings, including price, momentum and sequential growth, are positive. The stock enters the post-report period near the top of its range with expectations reset higher.
The bottom line is that Amplitude produced genuine reacceleration, a fourth guidance raise and a record operating margin, with a pipeline strong enough that management is considering adding sales capacity. The open question is whether AI-driven demand can be monetized without gross margin sliding further. With the stock already up two-thirds since the last report, flat retention metrics, slowing RPO and a modest fourth-quarter deceleration will draw more attention than they would have three months ago.
Read our earnings preview for Amplitude, Inc.: https://www.earningswhispers.com/article/AMPL/21780
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Oct-14 | |
| Sep-28 | |
| Sep-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Jul-15 | |
| May-27 |
