Beyond Meat's Cost Turnaround Meets A Sales Guide That Points Lower Again
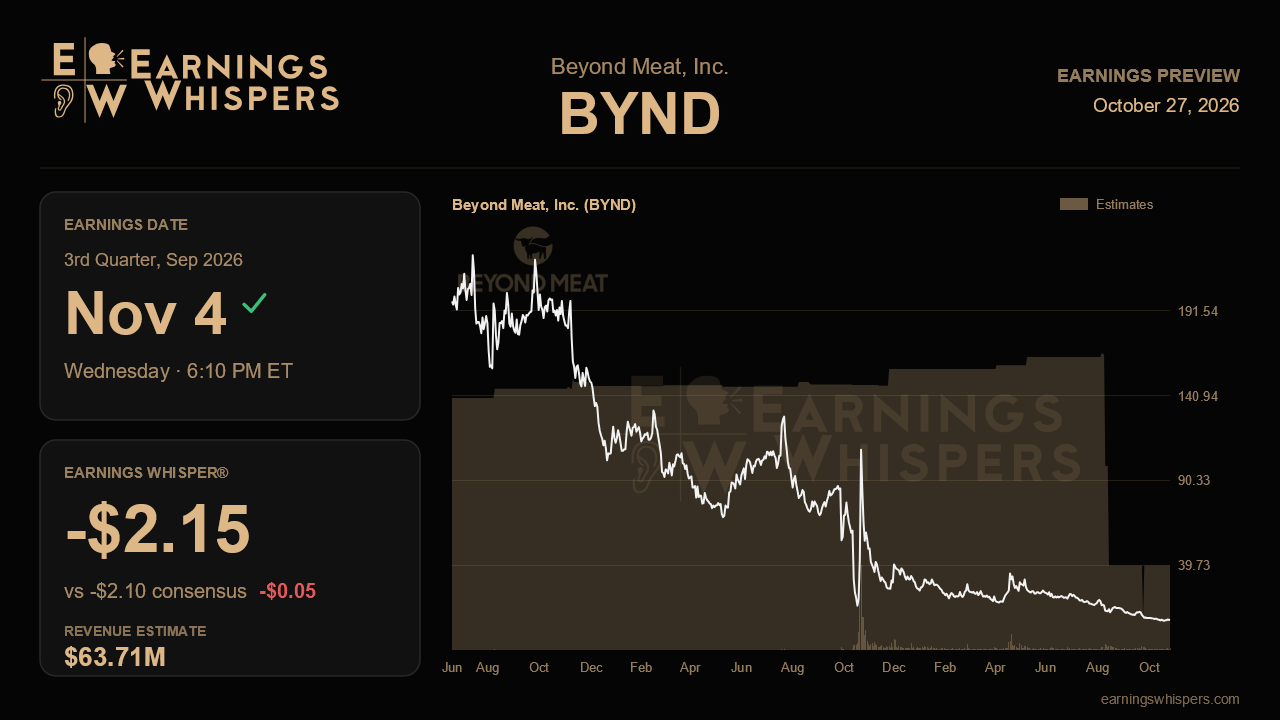
Beyond Meat heads into its third-quarter report on November 4 with an awkward split personality. The cost side of the business has been steadily repaired, with gross margin turning positive, operating expenses cut and cash burn shrinking to its lowest level in more than two years. Yet the top line keeps sliding, and management's latest outlook implies sales will step down again from the second quarter. The question this report must answer is whether the company can keep squeezing losses and cash use even as revenue shrinks, or whether the margin progress stalls once volume stops cooperating.
Wall Street expects a loss of $2.10 per share on revenue of $63.7 million, which would be a 9.3% decline from the $70.2 million reported a year ago. The per-share comparison looks dramatic on paper, with the expected loss implying a roughly 347% deterioration, but the share base has been reshaped by convertible debt turning into stock, so revenue, gross margin and cash use are cleaner yardsticks. The Earnings Whisper sits at a loss of $2.15, a touch worse than consensus, suggesting the informal bar is slightly lower but not meaningfully different.
Management guided third-quarter revenue to $60 million to $65 million, below where analysts had been. Consensus has since drifted down but still sits in the upper half of that range, above the $62.5 million midpoint. That matters because the same $60 million to $65 million range was offered for the second quarter, and the company cleared it comfortably with $68.8 million. Repeating the identical range after beating it implies an expected sequential decline, which reads as either conservatism or a genuine warning about food service and category softness. A result near or above the top of the range would support the conservatism theory; anything near $60 million would suggest demand is weakening faster than the improving narrative allows.
The most detailed commentary from recent calls framed the company as digging out. Management pointed to roughly 8% lower cost of goods from conversion-cost work, operating expenses about $14 million lower year over year, and a debt exchange that removed most of its leverage. The weak spots were equally clear. U.S. food service fell nearly 30% and international food service about 26% in the first quarter on lost quick-service restaurant business, with no recovery flagged, and category demand stayed soft in the U.S. and key European markets. Encouragingly, the pace of revenue decline has been easing, from double-digit drops to roughly 8% last quarter. Validation this time would mean declines staying in single digits, retail holding up on the new Kroger, Sprouts and Whole Foods placements, and early signs that the Beyond Immerse functional beverage launch in New York is gaining distribution. Progress on the China exit and asset sales, slated to be largely finished by year-end, would also help clean up the cost base.
The market has been unforgiving. Shares have fallen about 62% since the last report against a roughly flat S&P 500, and at $6.86 the stock trades far below its 200-day average of $19.21 and only modestly above its post-earnings low of $6.49, after touching $18 earlier in the period. Sentiment, oddly, has warmed considerably, with bullish readings jumping from about 11% last quarter to roughly 47%. That combination suggests some investors see the selloff as overdone, though optimism of this kind can evaporate quickly if the numbers disappoint.
Ultimately, this report hinges on whether gross margin and cash burn keep improving on a smaller revenue base. If Beyond Meat can show positive and rising margins with quarterly cash use still near the low levels it reached earlier this year, the turnaround story survives a shrinking top line. If margins slip back as volume falls, the cost gains will look less like structural repair and more like a temporary reprieve.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-22 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Sep-24 | |
| Sep-15 | |
| Sep-11 | |
| Sep-10 | |
| Sep-09 | |
| Sep-03 | |
| Aug-26 | |
| Aug-24 | |
| Aug-14 |
