Beyond Meat Narrowly Misses As Margin Repair Collides With Shrinking Volumes And A Lower Q4 Outlook
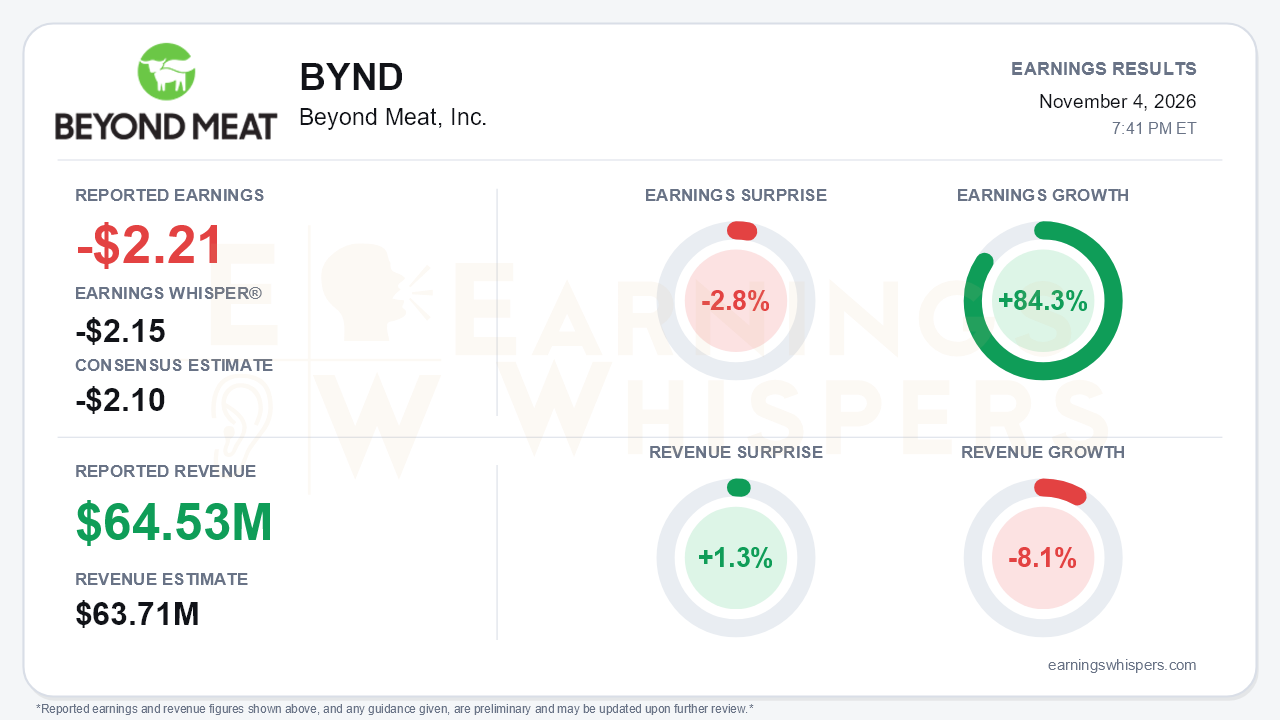
Beyond Meat's third quarter was a split decision. The company reported an adjusted loss of $2.21 per share, missing the consensus estimate of -$2.10 by 2.8% and falling short of the -$2.15 Earnings Whisper number. Revenue of $64.53 million beat the $63.71 million consensus by 1.3% and landed near the top of the $60-65 million guidance range, but it still fell 8.1% from a year ago. Per-share earnings improved 84.3% year over year, though that figure flatters the business. Weighted average shares rose from about 2.6 million to 19.2 million after the 2025 exchange offer, so most of the per-share improvement comes from dilution. In dollar terms, the adjusted net loss narrowed only modestly, to $42.2 million from $48.2 million. The central tension is that unit economics have improved sharply while the revenue base keeps shrinking, and fourth-quarter guidance implies that contraction is getting worse.
The margin story is real and is the best thing in the report. Gross margin reached 19.3%, up from a restated 7.4% a year ago and roughly 3.4% in the first quarter. It was the company's highest gross margin since 2021. Cost of goods sold per pound fell 10.1% to $3.90, a five-year low, helped by lower manufacturing, depreciation, inventory provision and logistics costs. Net revenue per pound rose 3.2% on better price realization and lighter trade spending. The adjusted EBITDA loss narrowed to $24.6 million, or 38.1% of revenue, from $33.5 million, or 47.7%. GAAP results need more careful reading. A $57.1 million impairment and $20.8 million of accelerated rent on the campus headquarters were partly offset by a $21.8 million litigation-accrual reversal and a $13.3 million derivative remeasurement gain. That produced a GAAP net loss of $82.8 million, or $4.32 per share. The company also noted that the impairment was triggered partly by a significant decline in its market capitalization.
Beneath the margin repair, demand is still eroding. Total volume fell 10.9%. U.S. retail revenue declined 13.2% as volume dropped 20.8%, reflecting lost club and breakfast sausage distribution and weak category demand. International foodservice fell 19.4% on lower QSR burger sales, and U.S. foodservice slipped 9.7%. International retail was the lone growth engine, rising 13.3% on European burger and ground beef sales. That was its third straight quarter of growth and an acceleration from 8.1% in the first quarter. Management's tone was noticeably more upbeat, with CEO Ethan Brown calling the quarter "measurable progress." On the call, however, both management and analysts acknowledged that operating expenses remain far too high for a business generating roughly $250 million in annual revenue.
The forward-looking evidence is mixed. On the positive side, Beyond Steak Filet has moved from direct-to-consumer sales into retailers including Wegmans, HEB, Meijer and Sprouts. The Beyond Immerse protein beverage grew sequentially, and the company is entering powders and bars. A new COO was hired with a mandate to cut operating expenses, and the partial campus lease termination reduces long-term obligations. The balance sheet also improved on paper: debt fell to $313.9 million from $411.6 million in the first quarter as notes were converted to equity. Bears have legitimate ammunition, however. Fourth-quarter revenue guidance of $54-59 million is below both the third-quarter result and last year's $60-65 million fourth-quarter guide. Cash fell to $169.3 million from $205.8 million in the first quarter, and quarterly cash use rose to $16.9 million from $11.8 million. Another $14.5 million of 2027 notes matures in March, stockholders' equity is in deficit, and the company cannot currently use its at-the-market offering program. Further note-for-equity exchanges would add dilution on top of the August 1-for-30 reverse split.
The market setup is more complicated than the narrow miss implies. Shares opened at $18.00 after the August report and closed at $7.27 on the day before this release, a 59.6% decline. The stock sits about 61% below its 200-day moving average of $18.43 and only 12% above its October 20 low of $6.49. Even so, investor sentiment rose meaningfully ahead of the report, climbing from 0.11 to 0.47. That suggests at least some investors were positioning for evidence of a turnaround despite the collapse in price. The Earnings Whispers trend signals remain mostly negative, with price, sequential growth and AVWAP all deteriorating.
The bottom line is that Beyond Meat delivered genuine operational progress, with record-high recent gross margins, a narrower EBITDA loss and sharply lower cash burn for the year to date. Those gains are not yet translating into a stable business. Volumes are falling across most channels, the fourth-quarter outlook steps down again, and per-share improvements are largely a product of dilution. Until U.S. revenue stabilizes and operating costs come down to match a smaller revenue base, better margins on fewer pounds are not enough to resolve the liquidity and dilution questions that drove the stock to its lows.
Read our earnings preview for Beyond Meat, Inc.: https://www.earningswhispers.com/article/BYND/21797
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Sep-24 | |
| Sep-15 | |
| Sep-11 | |
| Sep-10 | |
| Sep-09 |
