Compass Diversified's Consumer Engine Faces Pull-Forward Test As Altor Drags And Shares Slide
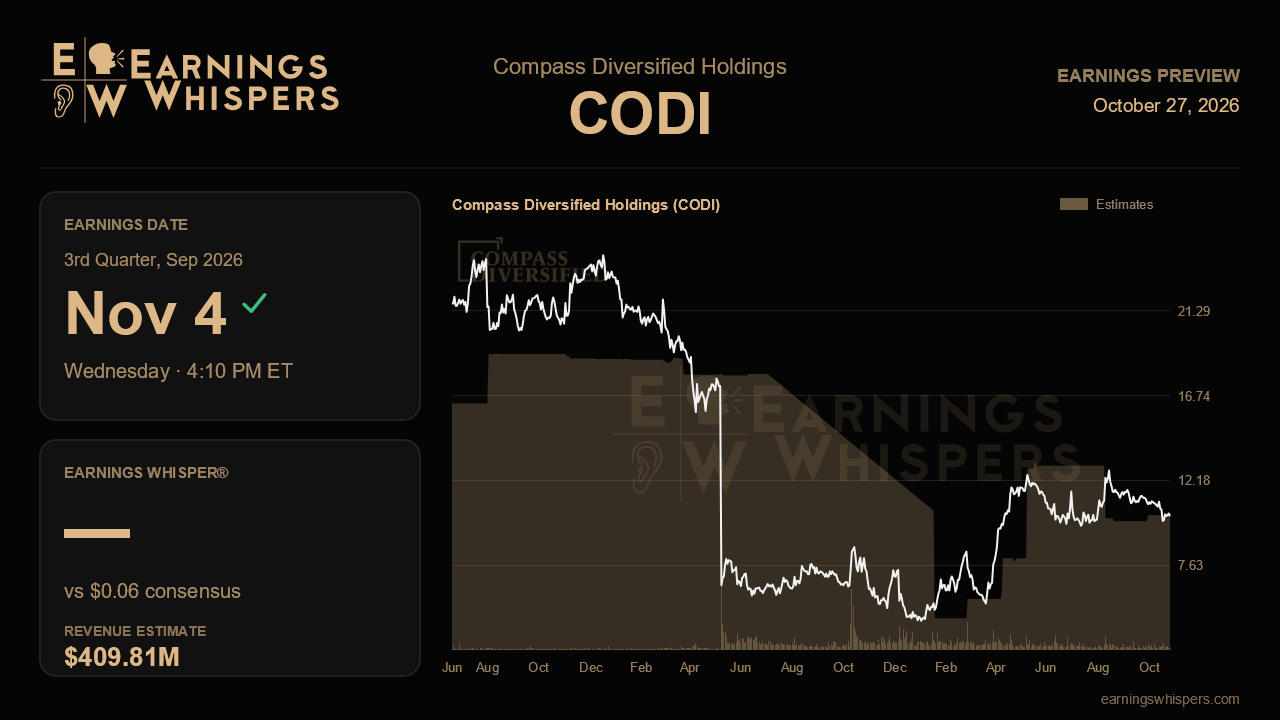
Compass Diversified heads into its third-quarter report with a story that looks better on paper than it does on the stock chart. Last quarter management reaffirmed its full-year subsidiary EBITDA target, raised its consumer outlook, cut leverage meaningfully and trimmed the management fee its external manager collects. The market answered by knocking the shares down about 16% since that report, roughly 15 percentage points worse than the S&P 500. Thursday's release after the close on November 4 needs to show whether the improving balance-sheet narrative can outrun the problems at Altor and the payback from consumer orders that arrived early.
The Street is looking for earnings of $0.06 per share on revenue of about $409.8 million. The revenue figure implies a 13.3% decline from a year ago, but that drop mostly reflects a smaller portfolio after the Sterno food service sale closed in May rather than a collapse in demand. Earnings, by contrast, are expected to swing sharply from a loss of $0.98 a year ago and a loss of $0.13 last quarter, an improvement that hinges on lower interest costs from roughly $300 million of debt paydown and on fading one-time expenses tied to the Lugano fallout. Those costs ran about $12 million in the second quarter, with only around $2 million recovered from insurers so far this year, so any lingering drag could easily wipe out a thin $0.06 estimate.
The central operating question is the consumer business. Branded consumer EBITDA jumped about 24% in the second quarter, led by Honeypot, BOA, a resurgent Primaloft and margin expansion at 5.11, prompting management to lift its segment outlook to $235 million to $270 million. Yet management also conceded that some BOA and Primaloft strength came from customers pulling orders forward around the Iran conflict, and that Rimports would see lower second-half volume from a large customer. A softer third quarter in those units would therefore be expected. What would validate the raised outlook is evidence that the underlying brands, particularly 5.11 and Honeypot, kept growing and holding their margin gains despite that timing noise. A sharp deceleration across the board would suggest the second quarter flattered the trend.
Industrial is the other half of the equation, and the trajectory there has been one-directional. The segment outlook has been cut twice, from $125 million to $135 million at the start of the year to $85 million to $95 million now, with Altor's EBITDA roughly halved last quarter on tariff-hit appliance packaging demand, weaker cold-chain volumes, higher oil-based input costs and execution that management itself called inadequate. Recovery was pushed out four to five quarters. Arnold's rare-earth magnet business, which surged on demand for non-China supply and its Thailand ramp, is the offset. The key test is whether Altor has stabilized or whether a third cut is coming, because the reaffirmed $320 million to $365 million total target depends on consumer gains continuing to cover industrial shortfalls.
Balance-sheet progress is the narrative investors can most easily verify. Covenant leverage fell to 4.8 times from 5.3 times, and management expected roughly $20 million from the Lugano settlement by early fall, all earmarked for debt reduction. Movement toward the 4 times threshold matters because management tied future buybacks or dividends to that level. The pending CEO handoff from Elias Sabo to Zach Sawtelle at year-end adds a layer of uncertainty to how that capital plan evolves.
Sentiment has cooled from moderately bullish before last quarter to essentially neutral, a slightly bearish reading. The shares, at $10.26, sit above their 200-day average of $9.65 but much closer to the post-earnings low of $9.79 than the $13.25 high, suggesting expectations are muted. The verdict likely rests on one thing: whether total subsidiary EBITDA guidance holds once consumer timing reverses and Altor reports another quarter. If it does, the deleveraging story remains intact and looks underappreciated. If it slips, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-22 | |
| Oct-01 | |
| Aug-24 | |
| Aug-11 | |
| Aug-10 | |
| Jul-27 | |
| Jul-13 | |
| Jul-01 | |
| Jun-24 | |
| Jun-11 | |
| May-06 | |
| May-04 | |
| Apr-21 | |
| Apr-01 |
