Compass Diversified Beats On Consumer Strength And Faster Deleveraging, But A Third Industrial Cut And A Cooler M&A Tone Hold The Outlook Flat
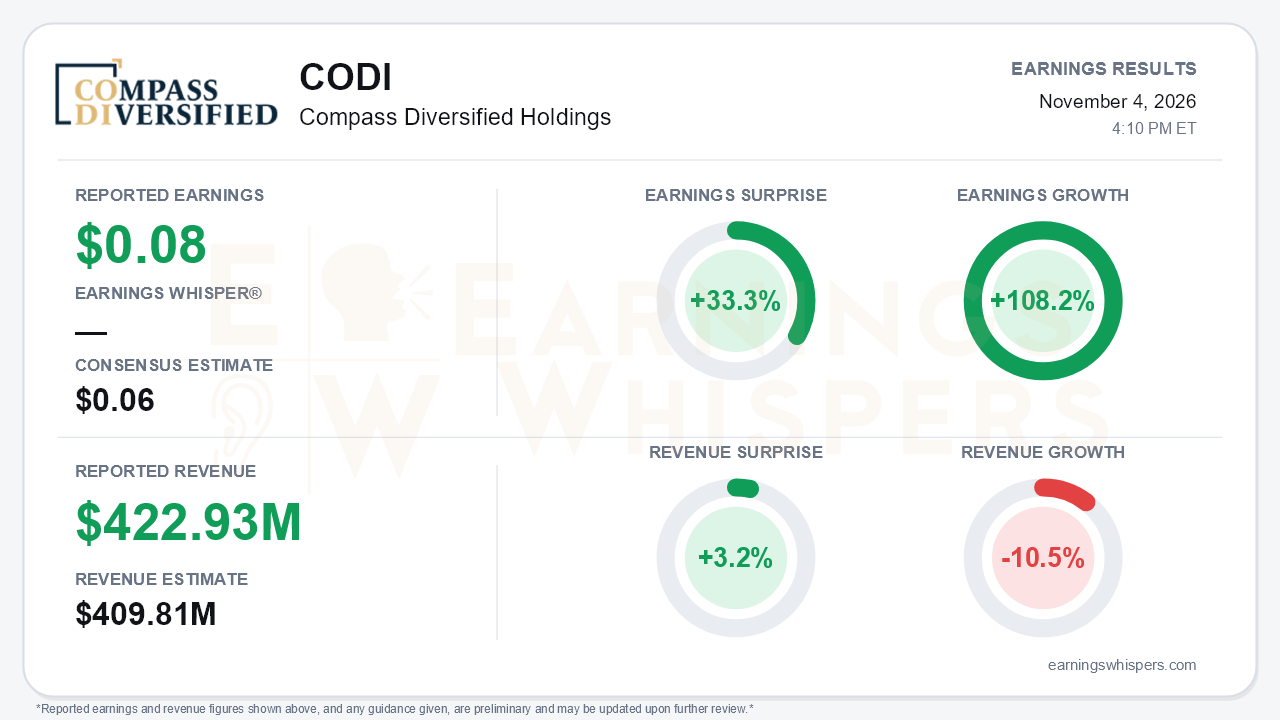
Compass Diversified delivered a cleaner quarter than its recent history might suggest. Earnings Whispers puts adjusted earnings at $0.08 per share, 33.3% above the $0.06 consensus and up 108.2% from a year ago. Revenue of $422.9 million beat the $409.8 million consensus by 3.2%, even though it fell 10.5% year over year. On a GAAP basis, CODI swung to income from continuing operations of $23.2 million from a loss of $86.7 million. Net income attributable to Holdings was $0.06 per share, compared with a $1.21 loss, so readers should note that the GAAP per-share figure sits below the normalized $0.08. The central tension is that the beat and the balance-sheet progress are real, yet full-year guidance did not rise. Branded Consumer strength is still being offset, almost dollar for dollar, by a deteriorating Industrial segment.
The quality of the GAAP turnaround deserves scrutiny. Pre-tax income from continuing operations was only $3.1 million, and a $20.1 million tax benefit did most of the work to reach the $23.2 million bottom line. The underlying improvement is mostly structural. Net interest expense fell to $21.8 million from $66.7 million as total debt dropped to $1.57 billion from $1.89 billion at year-end. Corporate expense was cut to $21.9 million from $47.3 million. Lugano's losses are also gone. The 10.5% revenue decline reflects the Lugano deconsolidation and the May sale of Sterno's Food Service Business. Stripping those out, comparable revenue rose just 0.8%, while comparable subsidiary adjusted EBITDA climbed 12.9% to $89.7 million. That is a margin story, not a volume story, and management acknowledged that roughly $7 million of tariff refunds and some order pull-forward helped the quarter.
Beneath the consolidated figures, the portfolio is splitting in two. Branded Consumer EBITDA rose 27.5% to $69.8 million, continuing an acceleration from about 12% in Q1 and 24% in Q2:
- The Honey Pot more than doubled.
- PrimaLoft grew 28%.
- BOA grew 22%.
There are cracks even here. Branded Consumer sales growth slowed to about 4% from about 7% in Q2. 5.11 swung to a roughly 2% EBITDA decline after a 14% gain last quarter, as direct-to-consumer demand from price-sensitive shoppers softened. Industrial EBITDA fell 19.6% to $19.8 million. Altor's contribution was more than halved to $7.0 million, and management expects its recovery to take several quarters. Rimports is subdued as a large customer reduces its reliance on it. Arnold was the exception, with EBITDA more than doubling on a rising backlog, though rare earth supply constraints cap how fast it can grow.
The guidance change captures the split precisely. CODI tightened 2026 subsidiary adjusted EBITDA to $330-$355 million, keeping the midpoint unchanged. The Branded Consumer range rose for a third straight time to $250-$270 million. The Industrial range was cut for a third straight call to $80-$85 million, down from $85-$95 million in Q2 and $95-$105 million in Q1. The more encouraging news was on deleveraging:
- Covenant leverage fell to about 4.5x from 4.8x in Q2 and 5.47x at year-end, reaching the organic year-end target early.
- The Lugano liquidation returned about $30 million, versus roughly $20 million expected, and the proceeds went to the term loan.
- Excess cash available for debt paydown is now framed at about $70 million, up from about $50 million.
- Year-to-date operating cash flow topped $100 million, versus an outflow a year ago.
The risk side shifted, too. Management called the M&A market "increasingly uncertain," citing a 24-year high in the 10-year Treasury yield, oil near $100 and firming inflation. It declined to put a timeline on a divestiture, a notable retreat from earlier confidence that a sale would happen this year. That matters because divestitures are a core lever for further debt reduction and eventual capital returns. This was also Elias Sabo's final call, with COO Zach Sawtelle succeeding him as CEO.
Investors had already cooled ahead of the print. Earnings Whispers sentiment remained positive but weakened meaningfully, falling from 0.24 to 0.08. The stock tells a similar story of an exhausted rally. Shares hit a 52-week high of $13.25 just after the prior report, slid to $9.79 in mid-October, and recovered to $12.02 heading into earnings. That leaves them 1.8% below the open following the last release, 9.3% under the high and about 22% above the 200-day moving average. The Earnings Whispers trend readings lean negative, with sequential growth and AVWAP both negative while price and momentum are neutral.
The bottom line is that CODI is executing well on what it controls: consumer brands, costs, cash generation and debt reduction. However, this quarter's beat leaned on a tax benefit, tariff refunds and pull-forward, and the full-year midpoint did not budge. Bears have legitimate ammunition in the repeated Industrial cuts, a slowing 5.11 and a stalled divestiture path. Bulls can point to leverage falling faster than planned and a consumer engine that keeps accelerating. Until Industrial stabilizes or a sale closes, the setup looks more balanced than the headline surprise implies.
Read our earnings preview for Compass Diversified Holdings: https://www.earningswhispers.com/article/CODI/21807
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-22 | |
| Oct-01 | |
| Aug-24 | |
| Aug-11 | |
| Aug-10 | |
| Jul-27 | |
| Jul-13 | |
| Jul-01 | |
| Jun-24 | |
| Jun-11 | |
| May-06 | |
| May-04 |
