Crane NXT Faces A Tough Currency Comparison As Antares Lifts Sales And Its Raised Outlook Is Tested
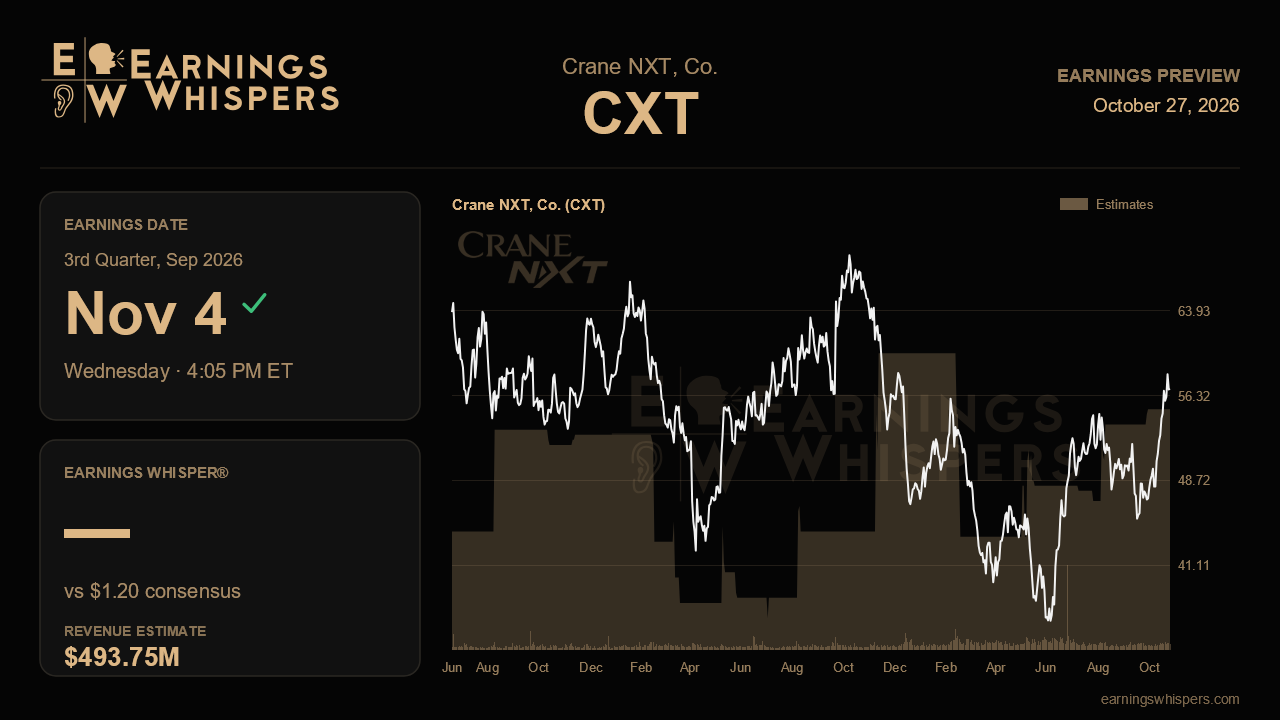
Crane NXT heads into its third-quarter report with an unusual split in expectations: revenue is supposed to climb at a double-digit clip while earnings per share slip. That gap is mostly a story about timing and mix. The newly acquired Antares Vision business is padding the top line, while the company's highly profitable currency and authentication franchise runs into the toughest year-over-year comparison of the year. How cleanly management handles that crosscurrent will show whether last quarter's first genuine guidance raise was the start of a trend or a high-water mark.
Wall Street expects earnings of $1.20 per share on revenue of about $493.8 million when results arrive after the close on November 4. That would mean sales growth of roughly 11% from a year ago but a 6% decline in earnings from $1.28. Sequentially, the bar is a modest step up from the $1.10 earned in the second quarter on nearly identical revenue. For the full year, management lifted its adjusted EPS outlook to $4.22 to $4.42 from $4.10 to $4.40, a range it had held through two straight reports. The consensus of $4.23 sits barely above the bottom of that range, which says analysts banked the raise but are not yet giving credit for upside. That cautious positioning gives the company room to impress, though it also hints at lingering doubt about how much of the year depends on the fourth quarter.
The security and authentication segment is the swing factor. Management guided third-quarter sales there to be flat to slightly down against a very strong period last year, a warning it has repeated since late 2025, so a soft headline number should not surprise anyone. What matters more is whether the underlying engine looks as healthy as advertised. Backlog reached a record of roughly $500 million last quarter, with visibility stretching into 2028, and the full-year segment outlook was raised to high single digits to low double digits. Steady or growing backlog, continued margin expansion, and early signs of progress on the doubling of international micro-optics capacity would validate that story. A backlog drawdown or any retreat from the raised segment outlook would challenge it, because the bull case rests on currency demand that is both durable and visible.
Antares is the other proof point. Management said the integration was running ahead of plan about five months in, and the company has flagged early cross-selling into pharmaceutical track-and-trace using its authentication technology and government relationships. Because Antares revenue is weighted toward the fourth quarter, this report will not settle the question, but it should show whether the business is contributing as expected and whether the segment remains on course for its targeted margin of about 27% by year-end.
Payments and merchandising is the weak spot. Its full-year outlook was trimmed to slightly down on a mid-single-digit hardware decline tied to slower large retail projects. The business is a smaller piece of the portfolio, and margins there expanded anyway, but further project delays would test management's claim that the softness is contained. Lower interest expense from debt paydown, with leverage targeted at about 2.3 times by year-end, offers a cushion below the operating line.
The market has already moved in the company's favor. Shares have gained about 6.6% since the last report while the S&P 500 slipped, and at $56.94 the stock sits well above its 200-day average and within 3% of its post-earnings high of $58.52, close enough to be testing a breakout. Sentiment has turned slightly bullish from slightly bearish, a modest shift. The central question is whether Crane NXT can absorb a difficult currency comparison while showing enough backlog strength and Antares momentum to make the fourth-quarter-heavy plan credible. Reaffirming or nudging up the raised range would keep the narrative intact; anything that leans on an even bigger year-end finish would invite skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-15 | |
| Oct-07 | |
| Sep-04 | |
| Aug-24 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-09 | |
| Jun-09 | |
| May-06 | |
| May-06 |
