Crane NXT Beats And Lifts EPS Midpoint On Currency Strength, But A Sales Cut Exposes A Stalling DTT Engine
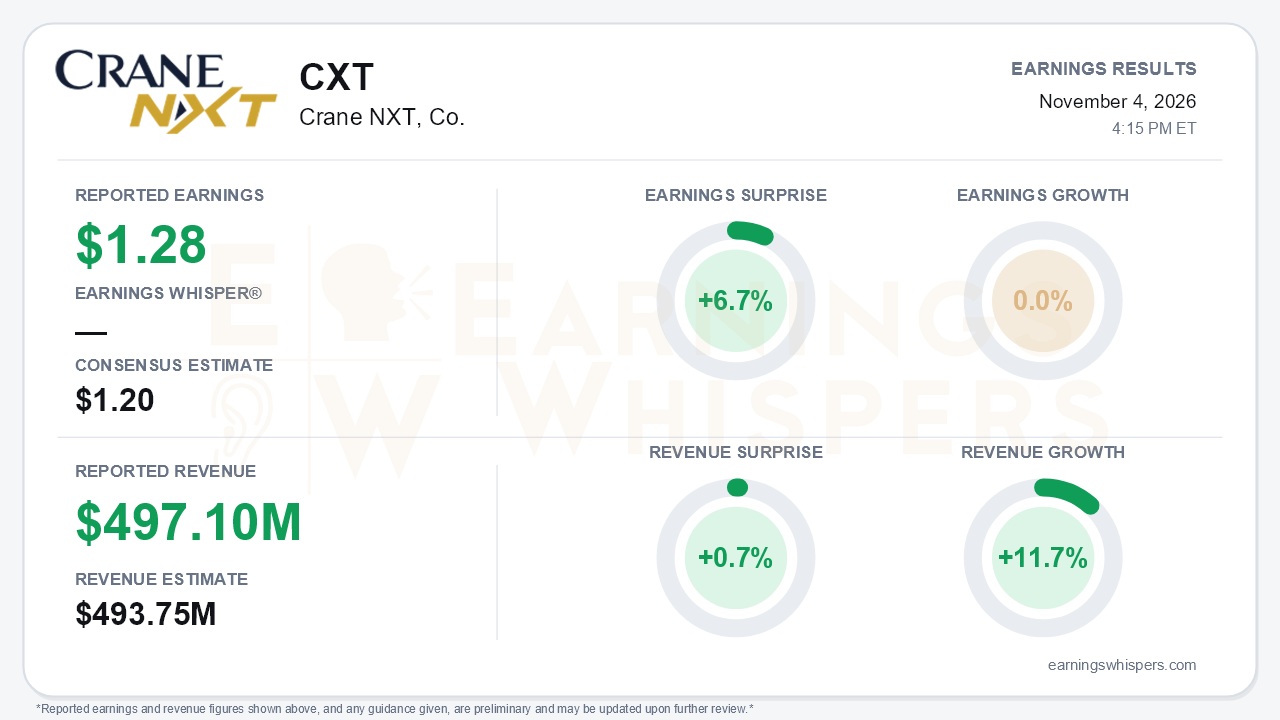
Crane NXT delivered a clean headline beat for the third quarter. Adjusted earnings of $1.28 per share topped the $1.20 consensus by 6.7%, and revenue of $497.1 million edged past the $493.75 million estimate by 0.7%. Beneath the headline, the picture is less tidy. Revenue grew 11.7% year over year, but adjusted EPS was flat at 0.0% growth, matching the $1.28 earned a year ago. Organic sales rose just 1.1%. The central tension is that management nudged the full-year EPS midpoint higher while cutting the sales outlook. A strengthening currency and authentication franchise is carrying a detection and traceability business that is losing organic momentum.
The quality of the quarter deserves scrutiny. Acquisitions, mainly Antares Vision, purchased in March, contributed 11.2 points of growth, so nearly all of the top-line expansion was bought rather than earned. On a GAAP basis, EPS fell to $0.66 from $0.87 and net income dropped 24%. Acquired intangible amortization rose to $25.6 million from $16.0 million, and acquisition-related adjustments climbed to $9.9 million. Adjusted EBITDA increased only 3.9% to $127.2 million, and margin compressed 190 basis points to 25.6%. Interest expense of $19.9 million, up from $16.2 million, absorbed the operating gains. That explains why adjusted EPS could not grow despite higher adjusted operating profit.
The segment split tells the real story. Security and Authentication Technologies (SAT) was excellent. Organic sales rose 7.2%, GAAP operating profit increased 17.3%, and adjusted EBITDA margin widened 60 basis points to 29.2%. Detection and Traceability Technologies (DTT) went the other way. Organic sales fell 5.3%, GAAP operating profit dropped 41.2%, and adjusted EBITDA margin slid 430 basis points to 28.0%. On the call, management cited two problems. Big-box retailers pushed out previously announced CPI hardware refresh programs, and hardware is expected to stay soft into 2027. Separately, pharma customers deferred Antares Vision life sciences installations to the first quarter of 2027. The CPI outlook has now deteriorated for several consecutive quarters, from flat to slightly down to soft with push-outs.
Guidance reflects that divergence.
- **Raised:** The adjusted EPS range was narrowed to $4.32 to $4.42, lifting the midpoint to $4.37 from $4.32. SAT growth guidance rose to roughly 11%.
- **Cut:** Total sales growth was lowered to about 14% from 15% to 17%, and DTT growth to the high teens from the low 20s.
- **Below the line:** Part of the EPS support comes from non-operating expense, now guided to $75 million to $80 million from about $80 million, not from better operations.
Backlog also eased sequentially. The total fell to $715.5 million from $755.5 million in June. DTT dropped to $233.9 million from $257.4 million, and SAT slipped to $481.6 million from its second-quarter record of $498.1 million. Year over year, backlog remains well above the $557.0 million of a year ago, though about $125 million of that is Antares.
The catalysts sit almost entirely in currency, and they are substantive:
- **Bank of Canada:** The new $20 banknote will feature Crane micro-optics, adding a marquee developed-market central bank.
- **U.S. government:** Multi-year renewals for micro-optics and currency paper build on the 10-year passport paper renewal secured in the second quarter.
- **Federal Reserve:** The 2027 print order is up double digits in volume and skewed toward the micro-optics $100 bill, with revenue flowing from early 2027.
- **Capacity:** Management is accelerating micro-optics investments in the U.S. and Malta, with currency capex stepping up in the fourth quarter.
- **2027 outlook:** Preliminary commentary pointed to SAT growth with margin accretion.
Cash generation was another genuine strength. Adjusted free cash flow of $97.7 million represented roughly 132% conversion, and net leverage stands at 2.5x. Management also said it is actively assessing portfolio optimization. That opens the door to repositioning weaker pieces, possibly CPI, although no transaction was announced.
Investors arrived with improving expectations. Earnings Whispers sentiment moved from essentially neutral (-0.02) to modestly positive (0.11). That is a meaningful but not euphoric shift. The stock has done much of the talking: shares are up 15.3% since the open following the August report and sit about 28% above the 200-day moving average. The Earnings Whispers trend signals are uniformly positive. That run-up raises the bar. A beat built on currency strength and lower non-operating costs, paired with a top-line cut, gives bears legitimate ammunition after a strong move.
The bottom line is that Crane NXT's currency and authentication business is getting stronger, with new central bank wins, multi-year government renewals, and a larger Fed order providing real visibility into 2027. DTT is the weak link. Organic declines, margin compression, retail push-outs, and delayed pharma installs forced a sales cut and are masking SAT's progress in the consolidated numbers. The EPS beat and higher midpoint are credible, but flat year-over-year earnings and 1% organic growth show how much depends on a CPI and Antares recovery that management itself now places in 2027.
Read our earnings preview for Crane NXT, Co.: https://www.earningswhispers.com/article/CXT/21817
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-15 | |
| Oct-07 | |
| Sep-04 | |
| Aug-24 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-09 |
