Encore Capital's Street Estimates Sit Below Its Raised Guidance Heading Into Third Quarter
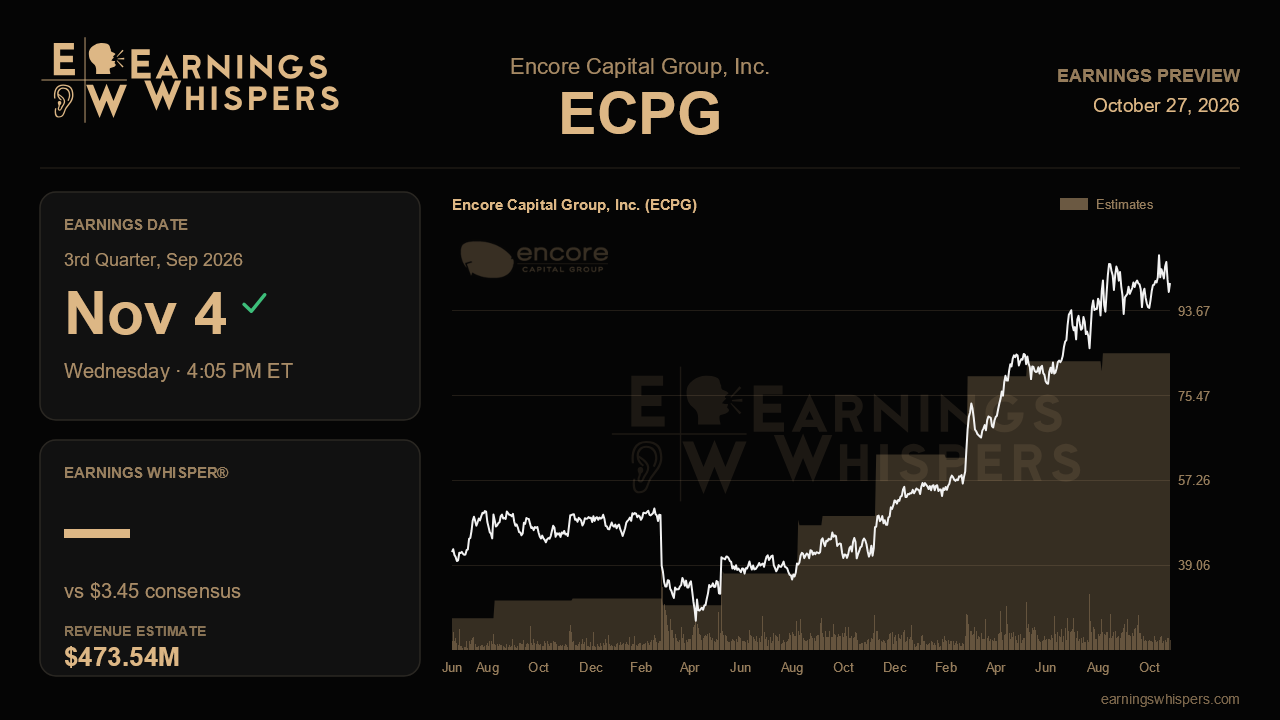
Encore Capital enters its third-quarter report with an unusual expectations gap. Management has raised its 2026 earnings outlook twice, from $12 a share at the start of the year to $13 in the spring and then to a range of $13 to $14 in August. Yet the full-year consensus of $13.01 sits at the very bottom of that range. Either analysts doubt the second half, or they have not fully caught up with a debt buyer whose collections, purchasing and financing costs are all moving in its favor.
For the quarter ending in September, Wall Street expects earnings of $3.45 a share on revenue of $473.5 million. That would be EPS growth of about 8.8% from $3.17 a year ago, with revenue up a more modest 2.9%. Revenue would also come in below the $491.9 million reported last quarter, so the Street is not counting on a top-line surge. The arithmetic on guidance is the more telling detail. Encore earned $3.86 in the first quarter and $2.81 in the second, and the second-quarter figure absorbed a one-time refinancing charge of roughly $1 a share. Adding $3.45 for the third quarter puts the year-to-date total near $10.12. Reaching the $13.01 consensus would then require only about $2.89 in the fourth quarter, a step down that looks hard to reconcile with the trends management described. A clean beat paired with a firm reiteration of the range would make the low-end consensus look stale.
The refinancing is the newest lever and should show up for the first time across a full quarter. The $1 billion May deal, split between dollar high-yield notes due 2032 and a euro floating-rate note due 2033, was priced at lower coupons and is expected to save about $50 million a year in interest, or roughly $12 million a quarter. The soft call of $230 million in convertible notes, settling in the third quarter, should further simplify the capital structure. If interest expense does not fall visibly, the savings story will need explaining.
The operating test sits in the US. Midland Credit Management posted record collections of $572 million, up 17%, and record purchases of $372 million, helped by opportunistic bulk deals in the spot market. Management argued that better collection efficiency lets it pay slightly higher prices and still win share. Validation would mean purchases running at a pace consistent with the top of the $1.4 billion to $1.5 billion full-year target, collections on track for the raised $2.8 billion to $2.85 billion goal, and a cash efficiency margin holding in the 60% to 61% zone rather than drifting back toward the 58% floor. Also worth tracking is the mix within changes in expected recoveries. In the second quarter, $18 million of the $71 million came from raised future-recovery forecasts, a sign that overperformance is turning into durable portfolio revenue. A larger share there would support earnings quality.
Europe is the weak link. Cabot collections were flat year over year last quarter after growing 7% in the first quarter, as UK lending stayed subdued, delinquencies stayed low and competition stayed intense. Another flat or declining print would not break the thesis, but it would confirm that Encore's growth rests almost entirely on the American market.
The market has been unenthusiastic. Shares have slipped 1.5% since the last report, slightly worse than the S&P 500, and sentiment is essentially unchanged at a mildly bullish 34.1%. Still, at $99.64 the stock trades about 21% above its 200-day average and has shifted into a higher range than last quarter, though it sits about 6% below its post-earnings high of $105.98. The central question is whether Encore can show that the second-quarter momentum, reinforced by lower funding costs, keeps the company tracking toward the middle of its guidance range. If it does, the gap between the Street and management is likely to close in management's favor.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-06 | |
| Oct-06 | |
| Aug-19 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-06 | |
| May-13 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-06 | |
| May-06 |
