Encore Capital Crushes Estimates And Lifts Guidance A Third Time, But Recovery Revisions Are Doing Much Of The Lifting
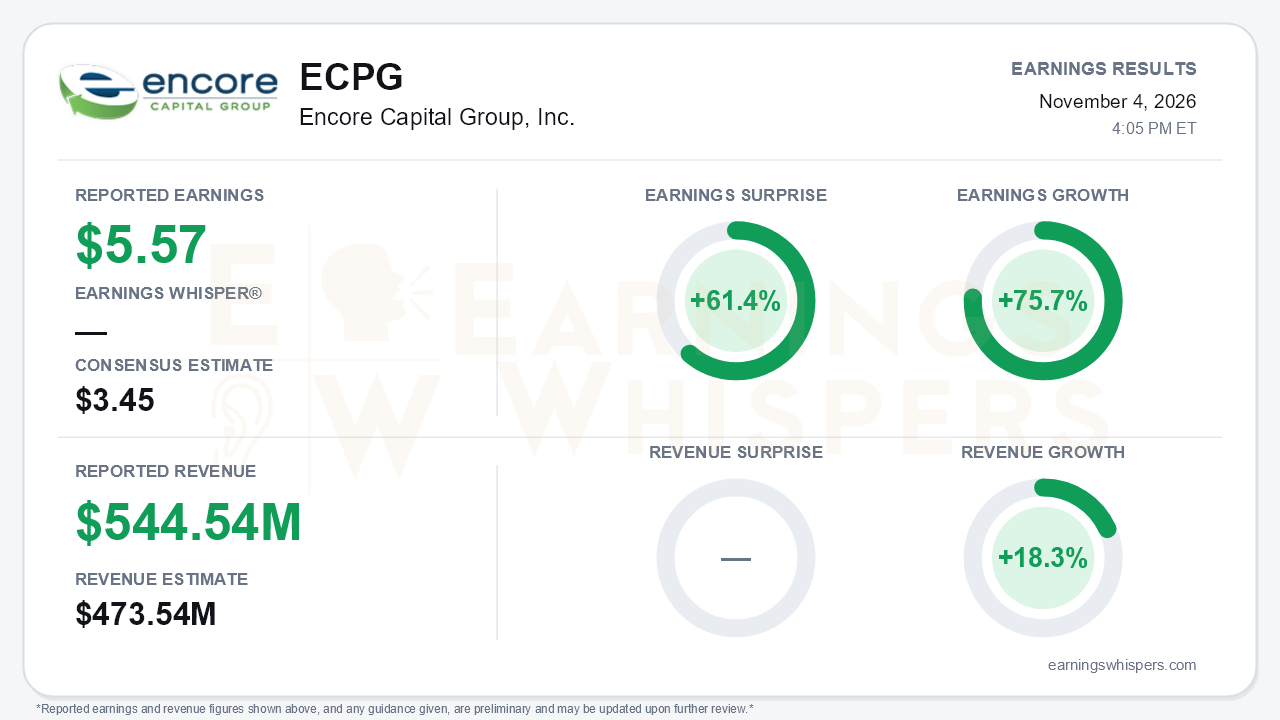
Encore Capital Group (NASDAQ: ECPG) delivered one of its strongest quarters in years. Third-quarter GAAP earnings of $5.57 per share beat the $3.45 consensus by 61.4% and grew 75.7% from a year ago. Revenue of $544.54 million topped expectations by 15.0% and rose 18.3%. Management followed with its third consecutive full-year guidance increase, lifting 2026 EPS to $15.50-$16.00 from $13-$14. That range is up from $12 at the start of the year. The headline is unambiguously strong. The more important question is how much of the beat reflects cash generation and how much reflects upward revisions to what Encore expects to collect in the future. That is the central tension in the quarter.
The composition of revenue tells the story. Record global collections of $754 million rose 14%, led by a 17% gain at U.S. unit MCM to $589 million. Revenue grew faster, at 18%, because changes in recoveries jumped to $111 million from $63.6 million a year ago. Core portfolio revenue grew a more modest 12% to $414 million. Operating expenses rose only 9%, and interest expense dipped slightly. A smaller share count added further lift, which is why EPS grew 76% while net income grew 66%. Servicing revenue slid to $17.5 million from $22.2 million, a minor but continuing drag.
The call addressed the quality question directly, and the evidence leans constructive. Changes in expected future recoveries reached $59 million, compared with $18 million in Q2, $16.7 million in Q1 and $11 million in Q4 2025. The 2023-2025 U.S. vintages accounted for $88 million of total recoveries. Encore is now formally raising its collection curves on those vintages rather than simply booking quarter-by-quarter outperformance. Management characterized this as "betterment, not pull forward." Year-to-date collections are running at 109% of expected remaining collections, up from 106% after Q1. The debt purchasing yield climbed to 44.9% from 41.7%, and trailing return on invested capital rose to 15.7% from 14.7%. Skeptics can fairly note that revisions to collection curves are estimates. Still, the steady climb in collections against forecasts gives those estimates real support.
Bears still have legitimate ammunition. Collections growth has cooled from 19% in Q1 to 13% and 14% in the past two quarters. Purchases of $390 million fell from Q2's record $444 million, which included opportunistic spot deals. Like-for-like U.S. pricing has edged higher for two quarters as some competitors withdraw, though management says collections efficiency has offset it so far. Cost of legal collections rose 25% to $100 million as the large 2024-2025 vintages age into the legal stage. The cash efficiency margin eased to 59.6% from 60.9% in Q1, though it remains above the full-year target of more than 58%. Europe remains a laggard: Cabot's collections grew just 2%. The guidance also implies a sharp step-down in the fourth quarter. Against nine-month EPS of $12.21, the new range implies roughly $3.30-$3.80 for Q4, suggesting management is not extrapolating Q3's revision-heavy result.
The forward catalysts lean positive. A potential $15-$20 million non-cash tax benefit in Q4 is excluded from guidance. Releasing that valuation allowance on Cabot deferred tax assets would add $0.65-$0.90 per share. Encore also settled its 2029 convertible notes in cash and extended its U.S. credit facility to October 2029. Leverage held at 2.3x, and management is willing to move toward the top of its 2-3x range for bulk or back-book purchases. Management also expressed confidence in further earnings growth in 2027 and described UK lending as growing after calling it subdued on earlier calls. Buybacks totaled $73 million year to date.
The market setup is more muted than the results. Investor sentiment was essentially unchanged at a moderately positive 0.35. Shares ended at $99.83 ahead of the report, 1.3% below the open following the August release. That leaves them 5.8% under the 52-week high of $105.98 set in mid-October, though still 19.3% above the 200-day moving average. Most Earnings Whispers trend readings are positive, with price trend the neutral exception. The stock has consolidated rather than chased the steady guidance increases.
The bottom line is that Encore's beat was large, and its quality held up better than a revision-driven quarter usually would. Rising collection curves on recent U.S. vintages, collections running ahead of forecasts and climbing returns all support the improvement. The risks are slowing collections growth, firmer U.S. pricing, mounting legal costs and a flat European business. Investors will want to see whether outperformance keeps translating into collection-curve revisions rather than normalizing, but the fundamental trajectory clearly improved this quarter.
Read our earnings preview for Encore Capital Group, Inc.: https://www.earningswhispers.com/article/ECPG/21826
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-06 | |
| Oct-06 | |
| Aug-19 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-06 | |
| May-13 | |
| May-12 | |
| May-11 |
