Eversource Faces An 18% Earnings Dip As Revolution Wind And FERC Questions Linger
Eversource Energy spent its last report clearing away problems. The Aquarion water sale closed, Moody's lifted its outlook to stable, Connecticut finally ruled on storm costs and a new transmission award landed. The market has not given the company much credit for any of it. The shares have fallen 6.2% since that report while the S&P 500 gained 2.8%. That leaves the third-quarter release, due after the close on November 4, with a narrower job than usual: show that the de-risking story is holding and that nothing new has crept in to replace the old overhangs.
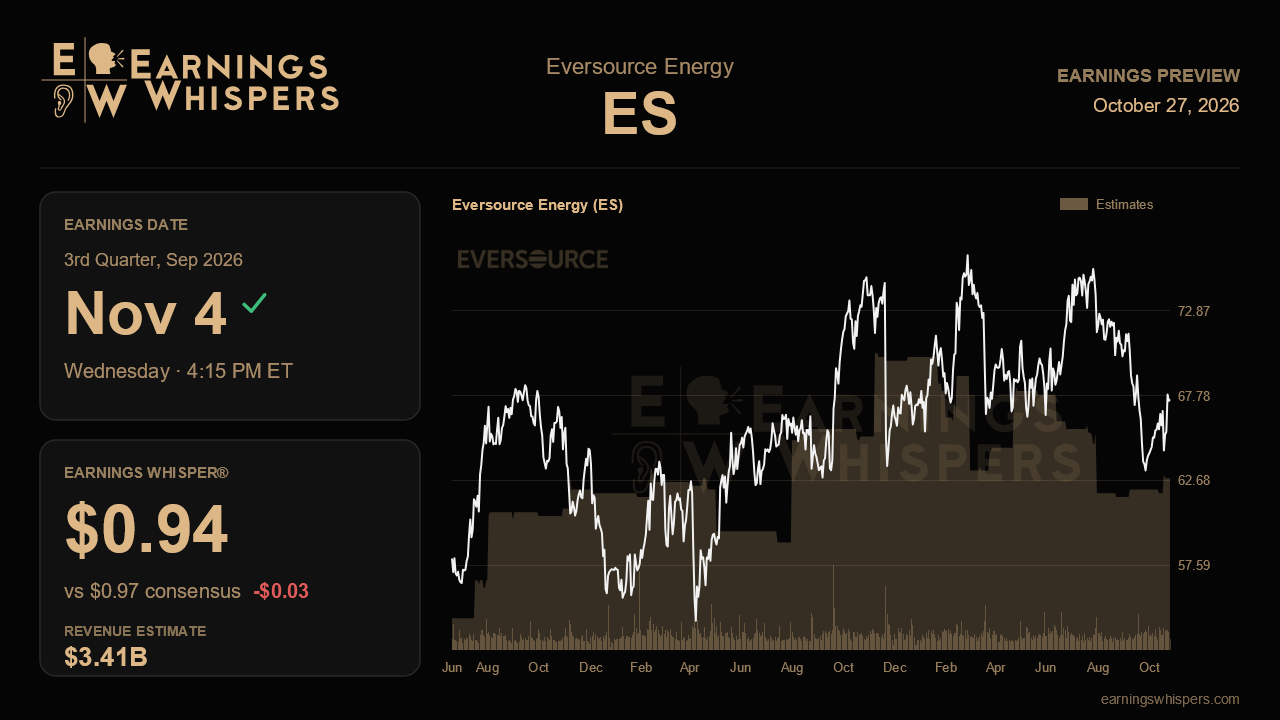
The headline numbers will look weak, and that is mostly by design. Consensus calls for earnings of $0.97 a share, down 18.5% from $1.19 a year ago, on revenue of about $3.41 billion, up 5.9%. The earnings decline reflects two known factors. FERC cut the base transmission return on equity to 9.57% from 10.57%, and the Aquarion earnings stream is gone after the June 30 sale. The second quarter already showed the pattern, with recurring EPS of $0.87 against $0.96 a year earlier on lower transmission and gas results. The whisper number of $0.94 sits slightly below consensus, which suggests the bar is modestly lower than the published estimate rather than higher.
Full-year guidance is the more useful anchor. Management reaffirmed its 2026 range of $4.57 to $4.72 a share after lowering it in March from $4.80 to $4.95. The Street's $4.64 sits right at the midpoint, so analysts are neither stretching for upside nor betting on a shortfall. A clean reaffirmation would be enough. Any drift toward the lower half would undercut the more confident tone management struck last quarter, when it said long-term growth should run in the upper half of its 5% to 7% range by 2028 and stay there through 2030.
Revolution Wind is the swing factor most likely to move sentiment. Last quarter brought an incremental $164 million after-tax charge tied to two stop-work orders and vessel remobilization, reversing a stretch in which management had held that liability steady. The project was described as 97% complete with commercial operation expected later in 2026. Another charge would revive doubts about whether the offshore wind exposure is truly contained. Confirmation that the schedule is on track would help close that chapter. On FERC, the new transmission rate tied to the company's filing seeking 11.39% is expected around November 30, after this report, so any update on timing or the roughly $880 million of unreserved refund exposure will be scrutinized.
The constructive pieces need follow-through. Investors should look for progress on securitizing the roughly $670 million of approved Connecticut storm costs, evidence that the $1.7 billion of Aquarion proceeds is reducing parent debt, and credit metrics holding above rating thresholds. Early signals on the Connecticut Light and Power rate case, which seeks a $451 million revenue increase in a politically sensitive election year, will also matter, as will any detail on the roughly $700 million ISO-NE transmission project and its place in the $26.5 billion capital plan.
Sentiment remains bearish but has eased slightly, to a reading of negative 0.27 from negative 0.295 before the last report. The stock trades at $67.55, below its 200-day moving average of $70.04 and roughly mid-range between its post-earnings low of $62.72 and high of $73.16, a range that sits below the prior quarter's. That backdrop implies skepticism rather than euphoria. The central question is whether Eversource can post a quarter with no fresh write-downs and a firm reaffirmation of its range. If it does, the upper-half growth narrative stays intact. If Revolution Wind costs rise again, the market's doubts will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Sep-29 | |
| Sep-21 | |
| Sep-16 | |
| Sep-15 | |
| Sep-10 | |
| Sep-10 | |
| Aug-14 | |
| Aug-04 | |
| Jul-31 |
