Eversource Misses On Q3 As ROE Cut And Storm Disallowance Bite, But Lifts Guidance Midpoint And Strengthens Balance Sheet
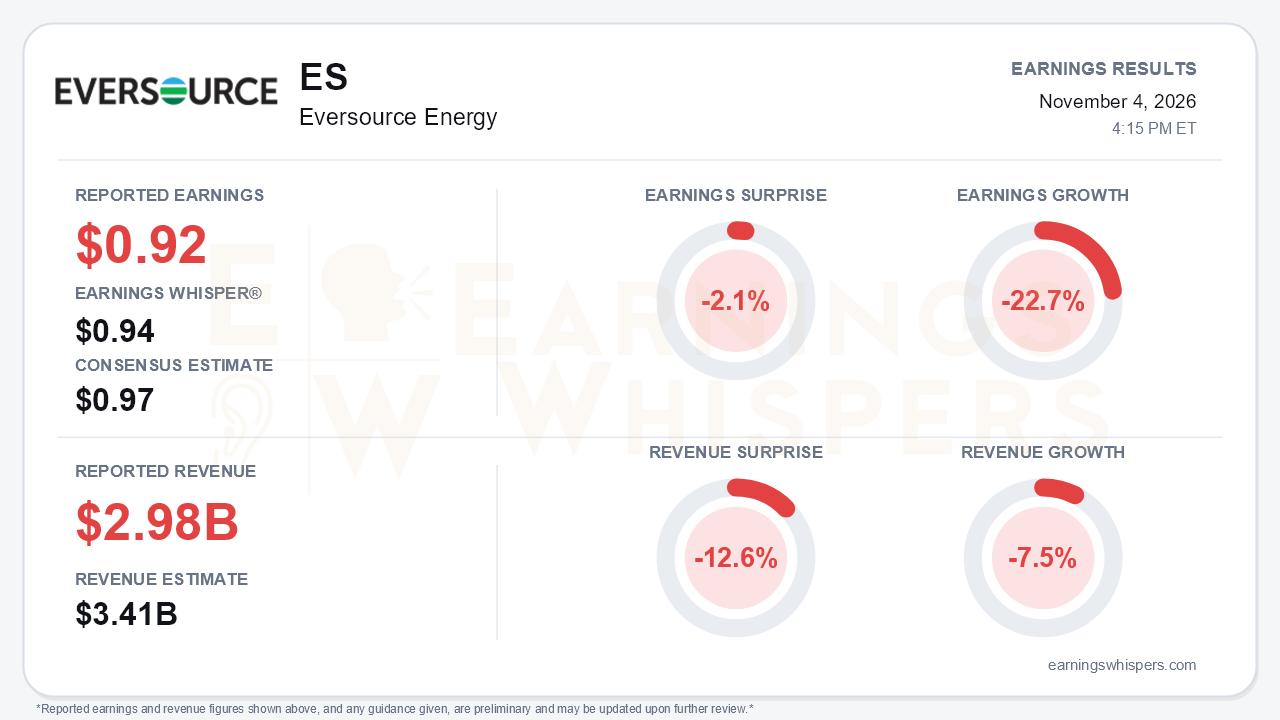
Eversource Energy (NYSE: ES) reported third-quarter earnings of $0.92 per share, missing the $0.97 consensus by 2.1% and falling short of the $0.94 Earnings Whisper number. Earnings fell 22.7% from the prior year's $1.19 non-GAAP recurring result, and revenue of $2.979 billion missed the $3.41 billion consensus by 12.6% while declining 7.5% year over year. Management nonetheless narrowed full-year 2026 non-GAAP guidance to $4.62–$4.70 and lifted the midpoint to $4.66 from $4.645. That is the central tension. The reported quarter shows how much the 2026 earnings base has been reset by regulatory setbacks and the Aquarion sale, yet the outlook and balance sheet look incrementally firmer than they did three months ago.
The miss was broad-based. Unlike last year, there were no non-GAAP adjustments, so GAAP and recurring EPS were both $0.92. Transmission earnings slipped to $182.0 million from $185.5 million as FERC's reduction of the New England ROE to 9.57% from 10.57% and higher interest expense offset rate-base growth. Electric distribution fell to $200.9 million from $221.6 million, hurt by roughly $40 million in disallowed Connecticut storm costs from PURA's July decision. Natural gas posted a wider seasonal loss of $43.4 million, though much of that reflects a Massachusetts rate-design change that shifts revenue recovery between quarters rather than lost earnings. The year-to-date gas contribution is actually up. Water contributed nothing after the June 30 Aquarion sale, versus $18.9 million a year ago. Parent results dropped to $6.5 million from $33.3 million on a higher tax rate and interest costs. Consolidated interest expense rose to $348.7 million from $318.1 million, and the diluted share count grew by about 5 million. The revenue shortfall looks less alarming for a regulated utility, where pass-through items and regulatory amortization swing the top line, but the earnings drag from ROE, storm costs and financing is real.
The call carried a more constructive message than the headline numbers. Revolution Wind reached commercial operation, and management said the reserve booked with the $164 million second-quarter charge is adequate, sharply reducing the risk of further offshore wind liabilities ahead of a final settle-up with GIP in 2027. ISO-NE moved the Eversource/Avangrid transmission project from preliminary to final selection, worth $700 million to Eversource, representing upside to the reaffirmed $26.5 billion capital plan. Connecticut smart meters, roughly $1 billion, are another potential addition, and a full capex update is promised with fourth-quarter results. Credit metrics improved meaningfully: S&P FFO/debt rose to 15.4% from 14.3% at the second quarter, and Moody's to 16.1% from 15.7%. Management reiterated that no near-term equity is needed, with the $800 million–$1.1 billion planned through 2030 back-half weighted. Massachusetts smart meter installs topped 500,000, and a roughly $50 million DOE grant is pending.
Management also sounded more confident about a 2028 inflection toward the upper half of its reaffirmed 5–7% long-term EPS growth range, now measured from the $4.66 base. It cited a full year of Connecticut storm cost recovery, paydown of $1.1 billion in storm debt, a Massachusetts gas rate-base addition in November 2027, and the NSTAR Electric performance-based-rate review. A final financing decision on Connecticut storm securitization is expected at the end of January, with cash by mid-2027.
Bears still have legitimate ammunition, and some of it is new. Management cautioned that GAAP accounting may force recognition of roughly $880 million in incremental long-dated FERC refunds before the DC Circuit rules on the appeal, which could come in late summer or early fall 2027. Management also said meeting the May 2027 refund deadline will be challenging. A separate prospective FERC ROE decision remains pending, with parties proposing figures in the 9% range against Eversource's requested 11.39%/10.79%. Higher rate assumptions, 2027 debt maturities and a court appeal over denied storm carrying charges add further uncertainty.
Investors entered the report skeptical, and that skepticism deepened slightly. Earnings Whispers sentiment stayed negative and edged down to -0.328 from -0.295. Shares at $70.46 are 2.1% below the open following the July report and only 0.6% above the 200-day moving average of $70.03, so the stock is essentially range-bound around that trend line. The trend readings are mixed: sequential growth and AVWAP are positive, while price trend is negative.
The bottom line is that Eversource delivered a weak quarter on the numbers, with a miss on both lines and a steep year-over-year EPS decline rooted in the ROE cut, storm disallowances and the Aquarion exit. Beneath that, the setup improved. The offshore wind overhang is largely resolved, credit metrics are stronger, the guidance midpoint ticked up and transmission growth was secured. Whether investors look through the reset now depends on how the FERC refund accounting and the appeal unfold over the coming year.
Read our earnings preview for Eversource Energy: https://www.earningswhispers.com/article/ES/21834
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Sep-29 | |
| Sep-21 | |
| Sep-16 | |
| Sep-15 | |
| Sep-10 |
