Genco's Promised $1 Dividend Faces Its First Test As Diana Bid Clouds The Outlook
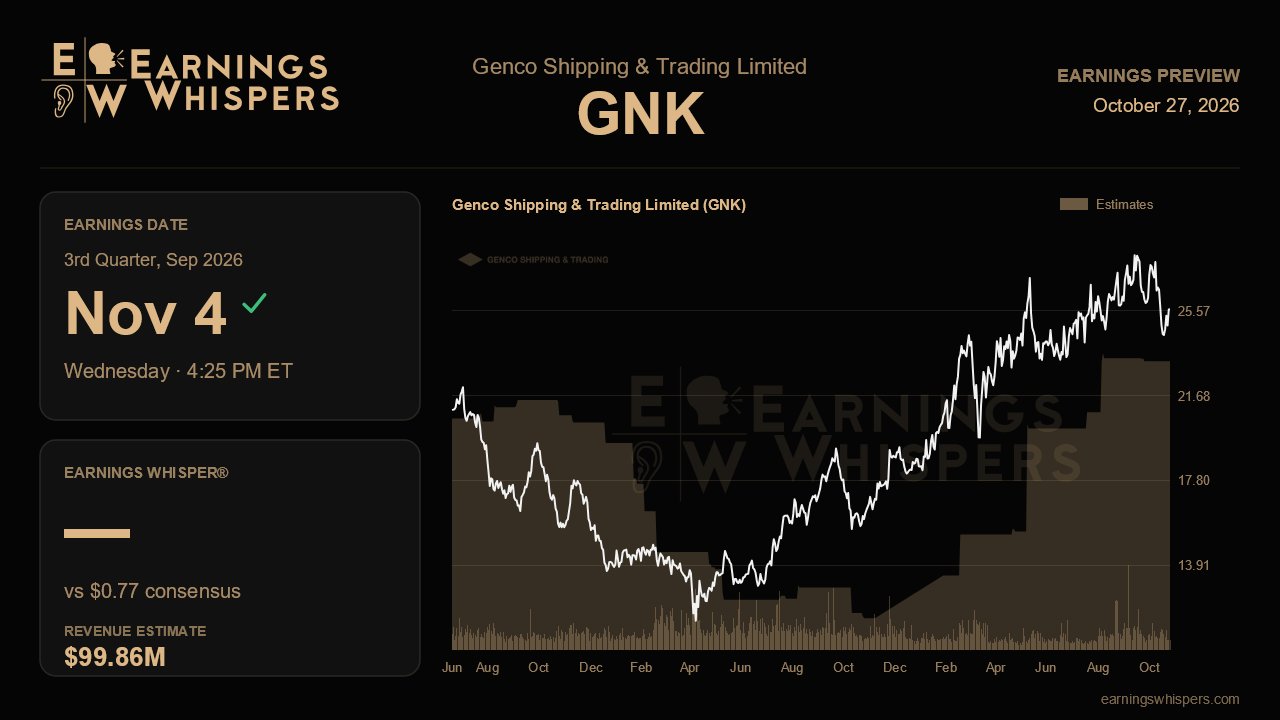
Genco Shipping & Trading heads into its third-quarter report having made a bold promise. Last quarter, management said both the third- and fourth-quarter dividends should top $1.00 per share. That lifted full-year guidance above $3.15, up from roughly $2.50 just one quarter earlier. The November 4 release, due after the close, is the first chance to see whether freight markets delivered on that call. It is also the first look at how far talks with Diana Shipping have progressed.
The Street is looking for earnings of $0.77 per share on revenue of about $99.9 million. That compares with a loss of a penny a year ago, which explains the eye-popping growth figure, and with $0.65 last quarter. Revenue is expected to rise about 25% from the year-ago period, solid growth driven mainly by charter rates rather than fleet expansion. The more useful benchmark is the rate data. Genco had already fixed 66% of its third-quarter days at $28,600 per day, well above the $24,273 it earned in the second quarter, which was itself its best quarterly rate since 2022. With an industry-low break-even near $10,000 per day, most of that rate improvement should fall straight to cash flow.
That is why the realized time charter equivalent rate matters more than headline EPS. Genco's dividend is calculated from cash flow and excludes items such as proxy and transaction costs. A noisy GAAP line therefore would not necessarily threaten the payout. The second quarter carried $13.1 million of other operating expenses tied to the tender offer and proxy fight, up from $3.8 million in the first quarter. Continued advisory work on the Diana proposal could keep that line elevated and pull reported earnings below the cash picture. The narrative would be validated by a realized rate close to or above the fixture level, a declared dividend clearly above $1.00, and fresh fourth-quarter fixtures that support the second $1.00-plus payout. The story would be challenged if the unfixed third of the quarter came in well below $28,600 per day. Signs that the strength in Capesize rates has faded heading into winter would also hurt.
The demand drivers management highlighted deserve follow-up. These included record Chinese iron ore imports and Brazilian exports in June, a revival in coal shipments tied to energy security, and El Nino conditions that are already squeezing Panama Canal transits. The Genco Volunteer, a 2019-built Capesize, was due to deliver in August and should add earning days at high rates. The 2025 acquisitions contributed about 15 cents of accretion to the second-quarter dividend, and investors will want to see that contribution grow.
Then there is Diana. Its non-binding proposal offers $24.80 in cash plus one Diana share, and the board has authorized its advisors to keep talking. That marks a shift from the adversarial stance of the earlier proxy fight. Management itself flagged the drawbacks: dilution from the stock component, pre-agreed vessel sales to Star Bulk at a discount, and a cash portion that shrinks as Genco pays dividends. That last point creates an awkward tension. Every dollar of the promised payout reduces the cash Diana would hand over.
The market has been cautious. Shares have slipped 3.5% since the last report, trailing the S&P 500 by about three percentage points despite clearly improving fundamentals. At $25.64, the stock sits above its 200-day moving average but in the lower half of its post-earnings range of $24.09 to $28.42. Sentiment has also turned more bearish than it was heading into the prior report. The central question is whether Genco can show that its standalone earnings power, measured by realized rates and a dividend above $1.00, is worth more than what is on the table from Diana. A clean beat on rates would strengthen the board's hand. Any wobble would make the takeover math look more attractive.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Sep-25 | |
| Sep-22 | |
| Sep-18 | |
| Sep-04 | |
| Aug-17 | |
| Aug-14 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-23 | |
| Jul-23 |
