Genco Posts Record Dividend And Multi-Year-High Rates, But Smaller Upside Revisions And A Softer Cape Market Keep Investors Cautious
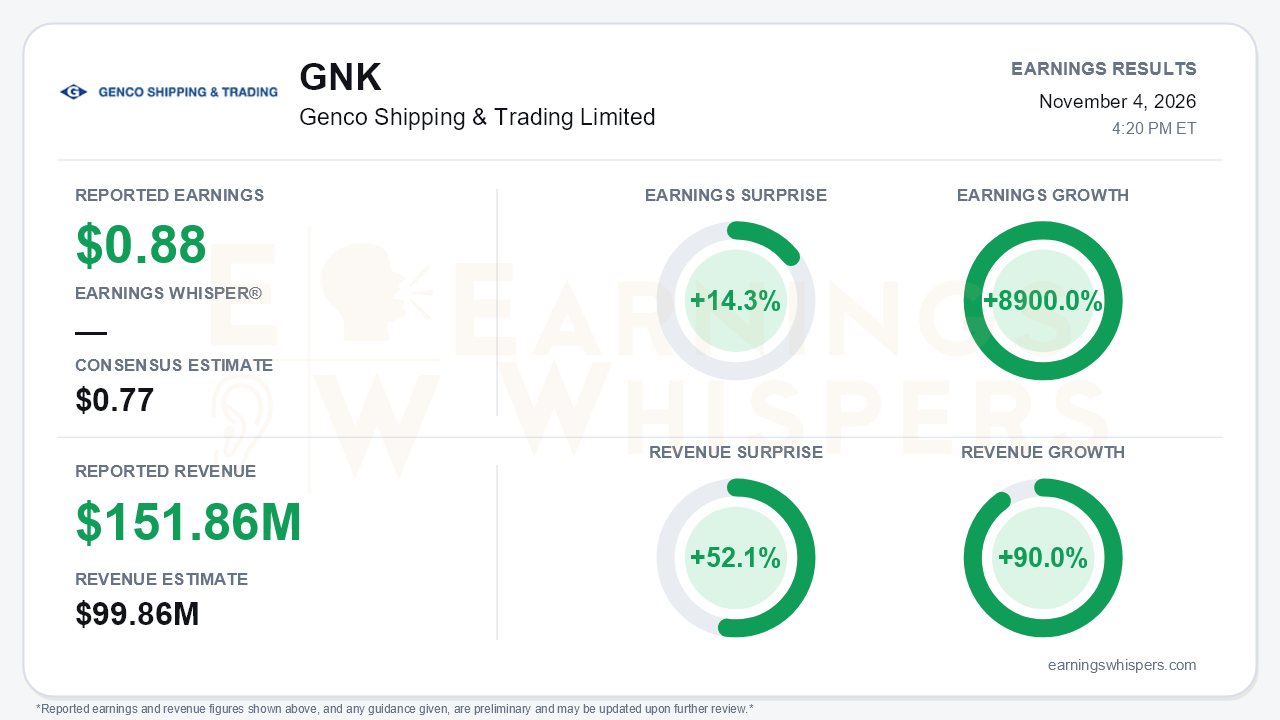
Genco Shipping & Trading delivered its strongest quarter in years, and the market barely seems convinced. Adjusted EPS of $0.88 beat the $0.77 consensus by 14.3%, while revenue of $151.86 million beat the $99.86 million estimate by 52.1% and grew 90.0% year over year. Earnings grew 8900.0% against an adjusted loss of $0.01 per share a year ago. GAAP diluted EPS was $0.85, with adjustments limited to a $0.6 million impairment, $0.4 million of other operating expense, and a $0.2 million unrealized fuel-hedge loss. The bigger shareholder outcome was the record $1.05 dividend, up 31% from Q2 and 600% from a year ago. The central tension is that Genco is still accelerating, but each new upgrade to the outlook is getting smaller while investors are looking past the record print.
The quality of the beat is strong. This was rate-driven operating leverage, not accounting relief. Fleet-wide TCE rose to $27,539 per day from $15,959 a year earlier and continued a clean sequential climb from $19,346 in Q1 and $24,273 in Q2. Capesize TCE reached $36,980, and the newer Newcastlemaxes earned $41,315. Net revenue nearly doubled to $104.6 million from $55.0 million. Adjusted EBITDA reached $68.1 million, up from $56.7 million in Q2 and $36.2 million in Q1. Through nine months, adjusted EBITDA of $161.1 million already well exceeds full-year 2025's $85.9 million. There were cost pressures: daily vessel operating expenses rose to $6,855 from $6,312 on higher crew and insurance costs. Depreciation and interest expense also climbed with the larger fleet and higher debt. These were rounding errors next to the rate tailwind.
The forward picture still points up, but less steeply. Q4 fixtures stand at $30,102 per day on 66% of owned available days, which management framed as the highest level since Q4 2021. Capesize/Newcastlemax days are fixed at $40,187. Management reiterated a Q4 dividend above $1 and lifted its full-year dividend outlook to more than $3.20. That increase is only about $0.05 from the prior call, compared with a roughly $0.65 jump between the Q1 and Q2 calls. The unfixed third of Q4 days also faces a less generous market. Capesize rates fell from roughly $50,000 per day in September to a floor near $30,000, pressured by Brazilian wet weather and high bunker prices. Vale guided to the low end of its range, and Q4 includes 120 scheduled off-hire days, rising to 165 in Q1 2027.
The demand narrative on the call remained constructive. Simandou iron ore exports are ramping ahead of schedule, with a record 5.3 million tonnes in October and 21 million tonnes year to date. Management also cited China's structural shift toward high-grade seaborne ore and potential import growth in India and Vietnam. On coal, it pointed to long-haul US- and Colombia-to-Asia flows supported by gas-to-coal switching and lower Chinese domestic output. Still, bears have legitimate ammunition:
- An analyst flagged that Chinese steel production is down about 3% year to date.
- The orderbook has climbed to 16% of the fleet from 12% earlier in the year.
- Capesize net fleet growth has edged up to 2%.
- Genco's cash breakeven has drifted to $10,500 per day from about $9,700 at the end of 2025.
- Debt rose to $380 million from $330 million to fund the Genco Volunteer, cutting undrawn revolver capacity to $300 million.
Leverage remains conservative, with net loan-to-value of 18% and liquidity of $394.6 million. However, rising secondhand values make further accretive acquisitions harder. The Diana Shipping proposal, prominent in earlier quarters, was not addressed, leaving that overhang unresolved.
Investor sentiment moved the wrong way despite the record quarter. It deteriorated meaningfully, from -0.09 at the prior report to -0.30, slipping from roughly neutral into clearly negative territory. The price action is consistent with that skepticism. At $24.71, shares are 7.0% below the $26.57 open following the August report, even as TCE, EBITDA, and the dividend all stepped higher. The stock sits only 1.2% above its 200-day moving average of $24.41, so it is hovering near that trend line rather than trading with conviction. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP still negative, which fits a market weighing strong current cash flow against doubts about how long peak rates last.
The bottom line is that Genco's quarter was fundamentally excellent. It delivered a clean beat driven by rates, a record dividend that topped its own projection, and Q4 fixtures pointing to even higher earnings. What has changed is the slope. Dividend guidance moved only marginally, Capesize rates have cooled from September's peak, and breakeven, debt, and orderbook trends are all creeping the wrong way. Investors appear to be pricing a cycle closer to its crest than its trough. The next leg for the stock likely depends less on Q4, which is largely booked, and more on whether Simandou and coal demand can hold Capesize rates above that $30,000 floor into 2027.
Read our earnings preview for Genco Shipping & Trading Limited: https://www.earningswhispers.com/article/GNK/21841
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-13 | |
| Sep-25 | |
| Sep-22 | |
| Sep-18 | |
| Sep-04 | |
| Aug-17 | |
| Aug-14 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 |
