Warrior Met Coal Tests Whether Blue Creek Volumes Can Outrun Sliding Coal Prices
Last quarter Warrior Met Coal finally delivered the payoff its shareholders had waited years for: Blue Creek tons poured in, costs fell and free cash flow swung to a positive $103 million after three straight quarters in the red. The catch was that management, in the same breath, warned that the second half of the year would likely bring weaker selling prices, thinner profitability and softer cash generation. The third-quarter report, due after the close on November 4, is the first real test of how much of that caution shows up in the numbers, and whether the new shareholder-return story survives contact with a tougher pricing tape.
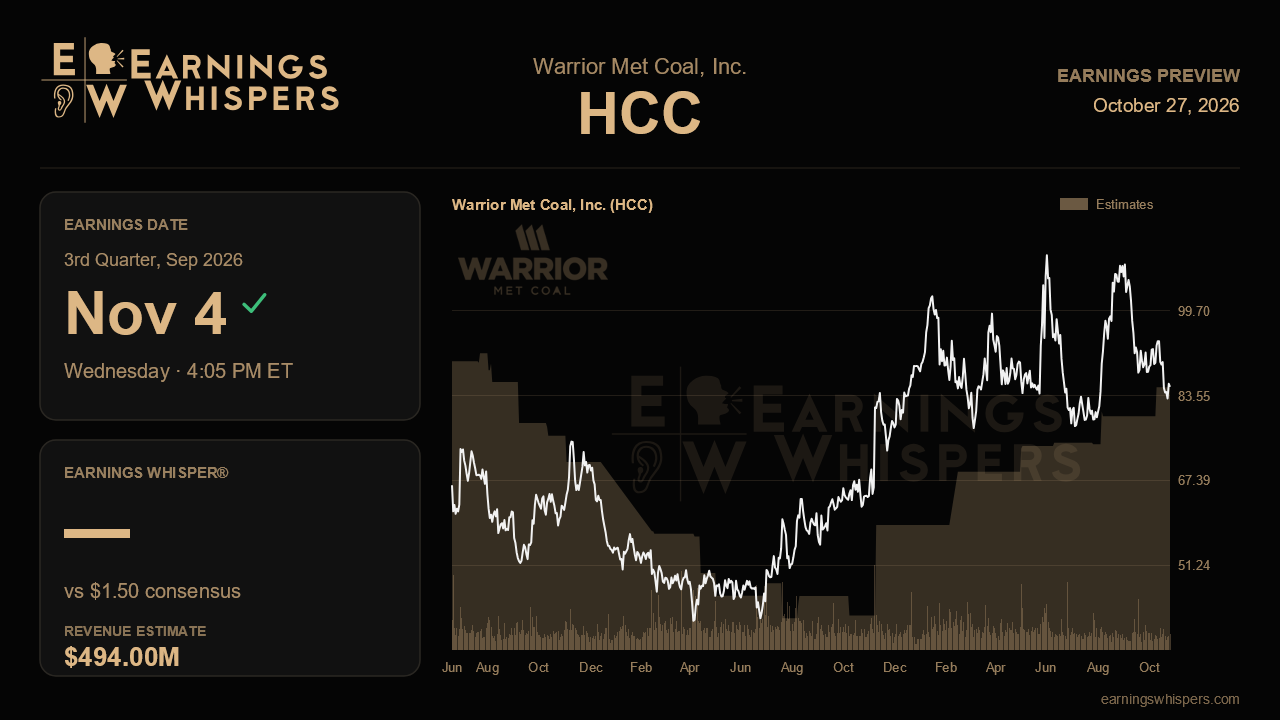
The Street has already pencilled in a step back. Consensus calls for earnings of $1.50 a share on revenue of about $494 million, down from $1.65 and $509.7 million in the second quarter. Year over year the comparison still looks spectacular, with earnings expected to more than double from $0.70 and revenue up roughly 50% from $328.6 million, but that growth mostly reflects the Blue Creek ramp lapping a much smaller base. The more telling detail is that analysts expect revenue to slip only about 3% sequentially while earnings fall about 9%. That implies volumes stay near record levels while lower realized prices and some cost creep squeeze the margin, which is essentially the scenario management sketched out.
Pricing is the swing factor. Gross price realization has fallen for four straight quarters, from 83% to 66%, and the average net selling price dropped to $138 a ton from $149. The culprit is a widening discount on East Coast high-vol A coal relative to the premium benchmark, compounded by a mix that leans increasingly toward that grade as Blue Creek grows. Management expects the benchmark itself to drift down from its supply-driven second-quarter average of $216 into a lower, range-bound market, with second-tier relativities staying depressed. If realization stabilizes near 66% rather than sliding again, the earnings hit could prove milder than feared. Another leg lower would suggest the mix problem is structural and that the Street's modest sequential decline is too generous.
On the other side of the ledger are volume and cost, the parts of the story Warrior controls. Management raised full-year volume guidance by half a million tons, lifting Blue Creek to 5.0 million tons with about 90% already contracted, and second-quarter cash costs fell to $93 a ton with help from the 45X production credit. Holding costs near that level despite the few dollars a ton of inflation management flagged would validate the operating-leverage thesis. Any shortfall in shipments against the raised target, or a jump in unit costs, would undercut the one argument that has been offsetting weaker prices.
Cash is where the narrative gets decided. With Blue Creek construction spending finished, management talked openly about moving to the next phase of shareholder returns, including a higher fixed dividend, specials and opportunistic buybacks, guided by a target of $350 million to $400 million in cash and roughly $500 million of total liquidity. A second consecutive quarter of solidly positive free cash flow would make that pivot credible; a slide back toward breakeven would push it further out.
The market is not giving the company the benefit of the doubt. Sentiment has cooled sharply, from roughly 35% bullish ahead of last quarter to under 5% now, and the shares have slipped 1.6% since the last report, trailing a modestly lower S&P 500. At about $85, the stock sits below its 200-day moving average near $90 and close to the bottom of a wide post-earnings range stretching from about $82 to $111. That positioning lowers the bar somewhat. The central question is whether Blue Creek's volume and cost advantages can keep free cash flow and the promised capital returns on track even as realized prices keep eroding. If they can, the gloom looks overdone; if not, the free-cash-flow inflection may look more like a high-water mark.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 | |
| Jul-15 | |
| May-14 | |
| May-01 | |
| Apr-30 | |
| Apr-20 | |
| Apr-08 | |
| Mar-10 | |
| Mar-06 |
