Warrior Met Coal's EPS Miss Exposes A Margin Squeeze, While Blue Creek Cash Funds A $2 Special Dividend
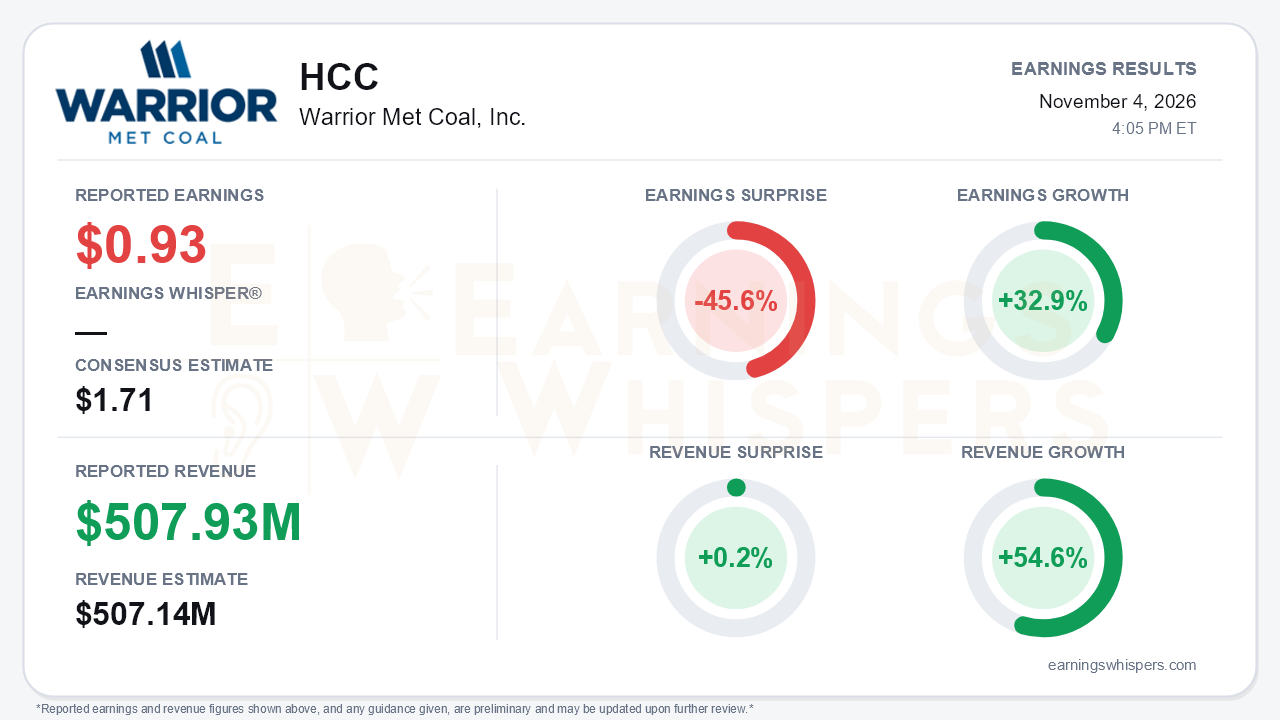
Warrior Met Coal's third quarter delivered two very different results. Earnings missed badly: $0.93 per share against a $1.71 consensus, a 45.6% shortfall. Cash generation was the strongest of the Blue Creek era and was large enough to fund a $2.00 per-share special dividend. Revenue of $507.93 million beat consensus by only 0.2% but grew 54.6% year over year, and EPS rose 32.9% from a year ago. The year-over-year comparison hides a sharp sequential decline, however. Net income fell to $49.3 million from $87 million in the second quarter, and EPS fell from $1.65. That is the central tension: the balance sheet and capital-return story improved, while unit profitability moved the wrong way.
The quality of the quarter deserves scrutiny from both directions. The year-over-year EPS growth understates the operating improvement. Pre-tax income more than doubled to $48.9 million from $22.9 million, but the prior-year quarter benefited from a $13.7 million tax benefit, compared with essentially none this time. The record free cash flow also needs context. Free cash flow of $138.9 million, up from $103 million in Q2 and negative $92 million in Q1, was helped by two factors:
- a $41 million inventory drawdown;
- capital spending of just $27.1 million, as Blue Creek construction wound down.
The inventory reduction was deliberate. Management sold about 550,000 surplus tons of High-Vol A coal at fixed prices, which cut roughly $27 million from Adjusted EBITDA and about $8 per ton from net pricing. Adjusted EBITDA still rose 76% year over year to $124.0 million, but it fell from $157 million in Q2 and $143 million in Q1. The Adjusted EBITDA margin dropped to 24% from 31%.
The call detailed why margins slipped. Cash cost per ton rose to $105 from $93 in Q2, and management broke the increase down as follows:
- Mine No. 7 geology and a longwall move added about $11 per ton;
- higher price-linked royalties added about $6;
- inflation added about $2.
The inflation item matters because management had called inflation immaterial last quarter and now expects it to persist. Gross price realization was stuck at 66%, versus 83% a year ago and an 80-85% long-term target. The causes were a heavier High-Vol A mix sold into the Pacific Basin at lower price relativities, and freight and demurrage that the Middle East conflict and port loading delays pushed sharply higher. Cash margin per ton slid to $39 from $45 in Q2 and $53 in Q1. Volumes also dipped from Q2's record, to 3.5 million tons sold and 3.1 million produced. Full-year guidance was only reaffirmed after last quarter's raise. The Q4 bar is not trivial, because one longwall move remains and year-to-date cash costs of $97.89 per ton sit inside the $95-$105 guidance range.
The demand side was more constructive. Premium Low-Vol pricing averaged $225 per ton, up from $216, and spiked to $252 in September. The spike came after Chinese mine-safety restrictions reopened the arbitrage and revived Chinese seaborne buying. A U.S. mine fire is expected to constrain High-Vol A supply into at least the first half of 2027. Management described European demand as stronger than it expected nine months ago, and said Blue Creek customer adoption keeps exceeding expectations. Looking further out, management said it expects 2027 volumes to exceed 2026 levels and pointed to Blue Creek debottlenecking toward 6-7 million tons of potential. With inventory now down to 967,000 tons, below the company's 1 million-ton target, working capital should be roughly flat from here. The cash gains that came from monetizing inventory therefore will not repeat.
Bears have legitimate ammunition. Management expects prices to settle below the September peak. The pricing tailwind depends on China maintaining its safety curbs. Freight disruption may extend beyond year-end. Management also declined to commit to a buyback despite the stock's steep drawdown.
Investors entered the report already uneasy. Earnings Whispers sentiment fell to 0.09 from 0.35 at the prior report, remaining slightly positive but sharply weaker. Shares closed at $80.66 on the eve of the release, 6.8% below the opening price after the August report and 10.3% below the 200-day moving average. They were also sitting essentially at the inter-earnings low, 27.6% below the 52-week high of $111.42 set on September 2. The internal trend readings are mixed: momentum is positive while AVWAP remains negative. In practice, the market had already been pricing much of the margin erosion before the miss became official.
The bottom line is that Warrior has crossed from investment mode into harvest mode. Liquidity reached $578 million, and the roughly $106 million special dividend is tangible proof that Blue Creek is converting into shareholder cash. However, the quarter's earnings power fell well short of expectations, unit costs and realizations moved against the company, and the strongest pricing support rests on Chinese policy and supply disruptions that could reverse. For the setup to improve, Q4 needs to show cost relief at Mine No. 7 and better realizations, not just another strong cash quarter.
Read our earnings preview for Warrior Met Coal, Inc.: https://www.earningswhispers.com/article/HCC/21848
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 | |
| Jul-15 | |
| May-14 | |
| May-01 | |
| Apr-30 | |
| Apr-20 |
