LeMaitre Faces A Credibility Test After Its First Guidance Cut As Autograph Carries The Load
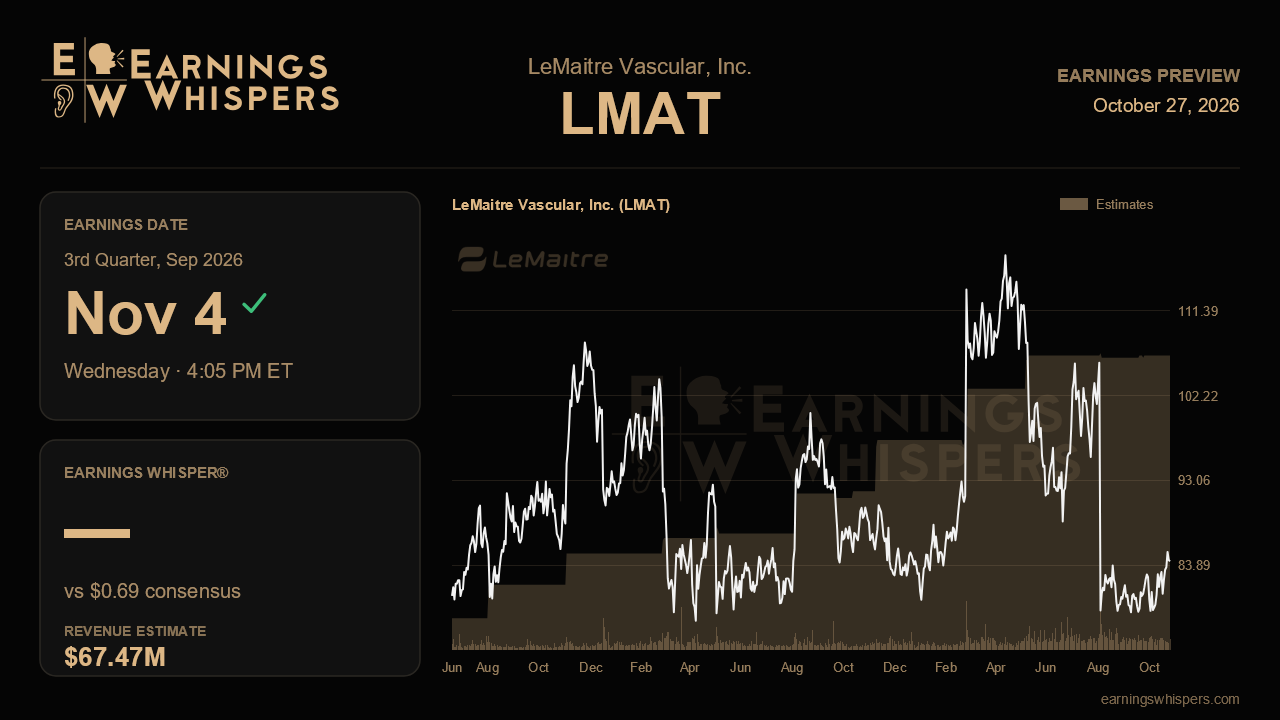
For several quarters, LeMaitre Vascular's earnings reports followed a comfortable script: strong pricing, rising margins and guidance that only moved up. That script broke last quarter, when management trimmed its full-year outlook for the first time in the current sequence, citing a stronger dollar, Middle East export delays and constrained cardiac allograft supply. The third-quarter report, due after the close on November 4, is the first chance to see whether that cut was a one-time reset or the start of a longer drift lower.
The Street is asking for earnings of $0.69 per share on revenue of $67.5 million, which would mean roughly 11% growth on both lines from the year-ago $0.62 and $61.0 million. That is solid, if not spectacular, for a company that delivered 23% EPS growth in the second quarter. Notably, consensus has already been pulled down from $0.72 and $68.5 million to sit near the middle of management's quarterly range of $0.66 to $0.71 and $66.3 million to $68.3 million. In other words, analysts have largely accepted the company's more cautious framing rather than betting on a quick rebound. The full-year range of $2.84 to $2.94 per share on $274.3 million to $278.3 million in revenue now sits below the roughly $3.00 analysts had penciled in before the cut, so another shortfall would land on a bar that has already been lowered once.
The central operating question is whether the three headwinds behave as management described. Export orders tied to the Middle East were expected to stay depressed for the rest of the year, so a modest drag there would be consistent with the plan. Currency is outside the company's control, but its impact should be quantifiable. Cardiac allografts are the more telling swing factor: supply limits capped growth even as the line rose 39% sequentially. Evidence that sourcing is improving would ease concern that the organic growth target, now 11%, could slip again. Catheters, which fell 11% against a recall-inflated comparison, should also become less of a drag as that distortion fades.
On the positive side of the ledger, Autograph needs to keep doing the heavy lifting. The product grew 34% worldwide last quarter and now accounts for about a fifth of sales. Management raised its international Autograph target to $11 million for the year after quarterly sales climbed from $2.1 million to $2.8 million, which implies further sequential gains in the second half. Gross margin is the other pillar. The full-year guide was nudged up to 72.4% on 7% pricing, lower shipping costs and European warehouse relocalization, so any slippage in margin would undercut the argument that the franchise is fundamentally healthy despite top-line noise. Updates on the Poland direct-sales launch, longer Autograph filings and the FDA follow-up at the New Jersey facility will also color the tone, as will any further discussion of the stalled QuickStick dialysis-access claim.
The market has not been forgiving. Shares have slipped 4.4% since the last report, trailing the S&P 500 by three points, and at $84.31 the stock sits well below its 200-day moving average of $94.44 and in the lower half of its post-earnings range of $78.22 to $90.28. That range is a full step down from the prior quarter's $88.59 to $115.75 band. Sentiment remains bearish, though less so than heading into the last report, suggesting some of the disappointment has already been absorbed.
What matters most is whether management can hold its newly reduced full-year outlook. Landing inside the quarterly range with Autograph and margins on track would argue the cut was a contained reset driven by external factors. Another reduction, particularly one tied to allograft supply or core demand rather than currency, would suggest the softer tone from last quarter was the beginning of a less dependable growth story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-12 | |
| Aug-27 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| May-20 | |
| May-07 | |
| May-05 | |
| May-05 | |
| Apr-14 | |
| Apr-07 | |
| Mar-02 |
