LeMaitre Vascular Misses On EPS And Cuts Profit Guidance Again, Even As Organic Growth Accelerates To 12%
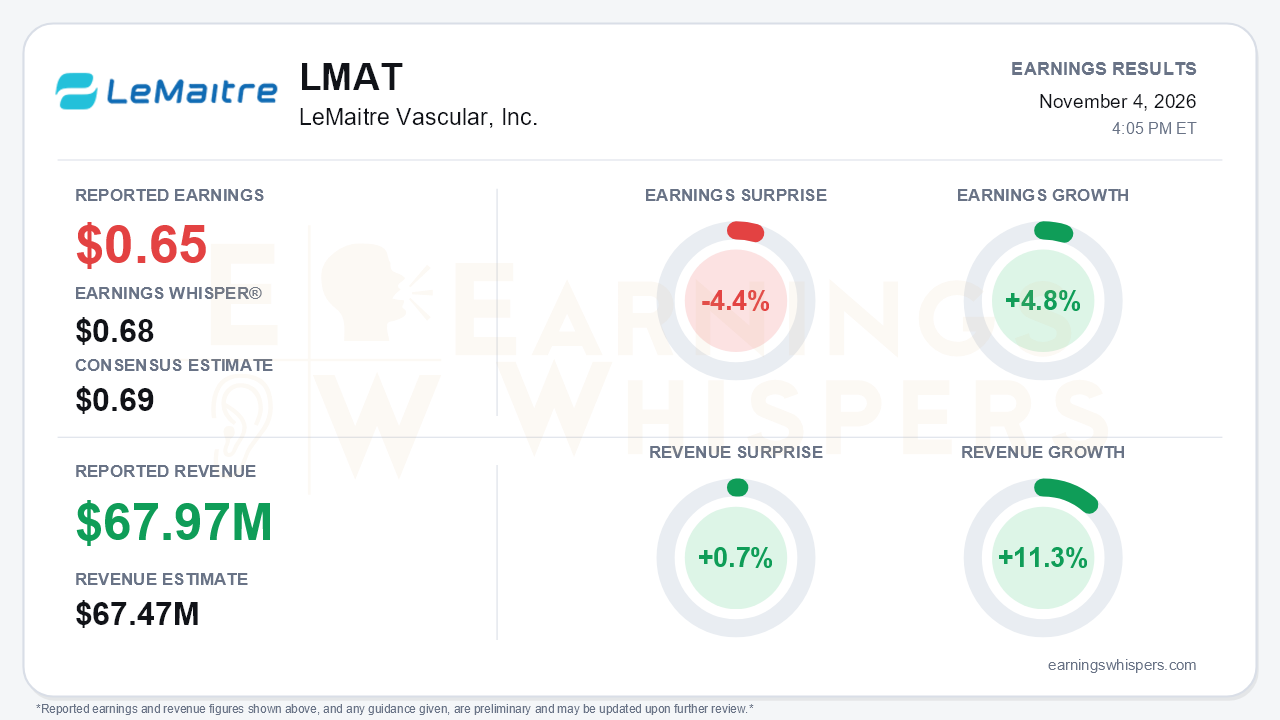
LeMaitre Vascular delivered a quarter in which demand improved but profitability did not keep pace. Third-quarter EPS of $0.65 missed the $0.69 consensus by 4.4% and fell short of the $0.68 Earnings Whisper number. Revenue of $67.97 million beat consensus by 0.7% and grew 11.3% year over year. On an organic basis, sales rose 12%, up from 10% in the second quarter and above the roughly 11% implied by August guidance. The problem is that the extra growth did not reach the bottom line. Management trimmed full-year profit guidance for the third consecutive call, and that is the central tension: the top line is getting stronger while earnings visibility keeps getting weaker.
The EPS comparison needs context. GAAP EPS fell 14% from $0.75 because the year-ago quarter included a non-recurring Employee Retention Tax Credit. Excluding that credit, earnings grew 4.8%, which is far slower than double-digit sales growth. Gross margin was a modest bright spot at 71.7%, up 90 basis points on an adjusted basis because of higher selling prices and operational efficiencies. Spending absorbed that gain. Adjusted operating expenses rose 18%, with sales and marketing up about 22% and R&D up roughly 49%. Management attributed part of the increase to an easy comparison against belt-tightening in the third quarter of 2025. Even so, operating margin fell to 26% from 29% in the second quarter. A $0.5 million inventory reserve tied to the FasTip discontinuation also weighed on results. Adjusted operating income grew just 5%.
The operating story beneath the miss is genuinely healthy:
- Growth came from 7% price and 5% units, a mix that reflects LeMaitre's pricing power in niche vascular products.
- Grafts rose 20% and shunts rose 14%.
- RestoreFlow allograft growth accelerated to 34% from 17% in the second quarter, and cardiac allografts jumped 65%.
- International Artegraft sales reached $3.0 million, up from $2.8 million in Q2 and $2.1 million in Q1. Management reaffirmed a full-year international Artegraft target above $11 million.
- Artegraft approvals expanded to 60 countries with new clearances in Brazil and Saudi Arabia, and a Japanese PMDA filing is planned this quarter.
- The sales force grew to 171 reps from 163 last quarter, with 17 openings still unfilled.
Demand is not the issue. The cost of capturing that demand, together with currency, is. Management cited a stronger dollar, with EUR/USD at 1.12 versus 1.15 in August, as a drag on reported revenue and margin flow-through.
Guidance shows the cumulative erosion. Full-year EPS guidance is now $2.80, down from $2.89 last quarter and $3.00 earlier in the year. Other targets moved the same way:
- Operating income guidance fell to $75.4 million from $76.8 million, implying a 27% margin versus 28% previously.
- Gross margin guidance slipped to 72.1% from 72.4%.
- Reported revenue guidance edged down to $275.8 million.
- Fourth-quarter organic growth guidance fell to 11% from 12%.
- Fourth-quarter EPS guidance of $0.70 to $0.75 was characterized as below estimates.
The $19.2 million B. Braun asset acquisition is strategically sensible. It is LeMaitre's first sizable deal in roughly six years and adds polyester and silver-coated grafts with $9.4 million in 2025 sales, all outside North America. However, the acquired products carry roughly 40-50% gross margins, well below the corporate level. Management expects 10-15% first-year customer breakage, and the products are flat sellers. The deal adds only about $150,000 of fourth-quarter sales at break-even.
Leadership is also changing. President Dave Roberts, architect of 26 acquisitions, steps down at year-end, and the CEO will lead business development on an interim basis. That is a notable change for a company whose growth model relies on bolt-on deals. RestoreFlow cardiac demand also remains constrained by internal quality-release capacity, which caps one of the fastest-growing lines. On the positive side, management described an October FDA meeting on the New Jersey Artegraft facility as encouraging. Free cash flow rose $6 million sequentially to $19.7 million, and cash reached $390 million. The $100 million buyback authorization appears largely unused so far.
The market had already priced in skepticism before the report. Shares closed at $80.60 the day before earnings, down 8.6% since the opening after the August report. The stock sat 14.6% below its 200-day moving average and only 3% above the 52-week low of $78.22 set on September 21. Investor sentiment was negative entering the report and weakened modestly, moving from -0.37 to -0.41. That shift reflects incremental caution rather than capitulation. Price and AVWAP trend readings remain negative. Another guidance cut gives bears legitimate ammunition, though much of that frustration was arguably reflected in the stock beforehand.
The bottom line is that LeMaitre's growth engine is running faster, led by biologics, international Artegraft expansion and pricing. Margin discipline, however, has slipped as investment, currency and one-time charges absorb the upside. Until the company stops resetting profit guidance lower and shows that its expanded sales force and the B. Braun portfolio can earn operating leverage, the accelerating top line is unlikely to be enough to repair a stock trading near its lows.
Read our earnings preview for LeMaitre Vascular, Inc.: https://www.earningswhispers.com/article/LMAT/21862
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-12 | |
| Aug-27 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| May-20 | |
| May-07 | |
| May-05 |
