Centrus Faces A Light Quarter And A Halved Stock As Build-Out Story Meets Its Test
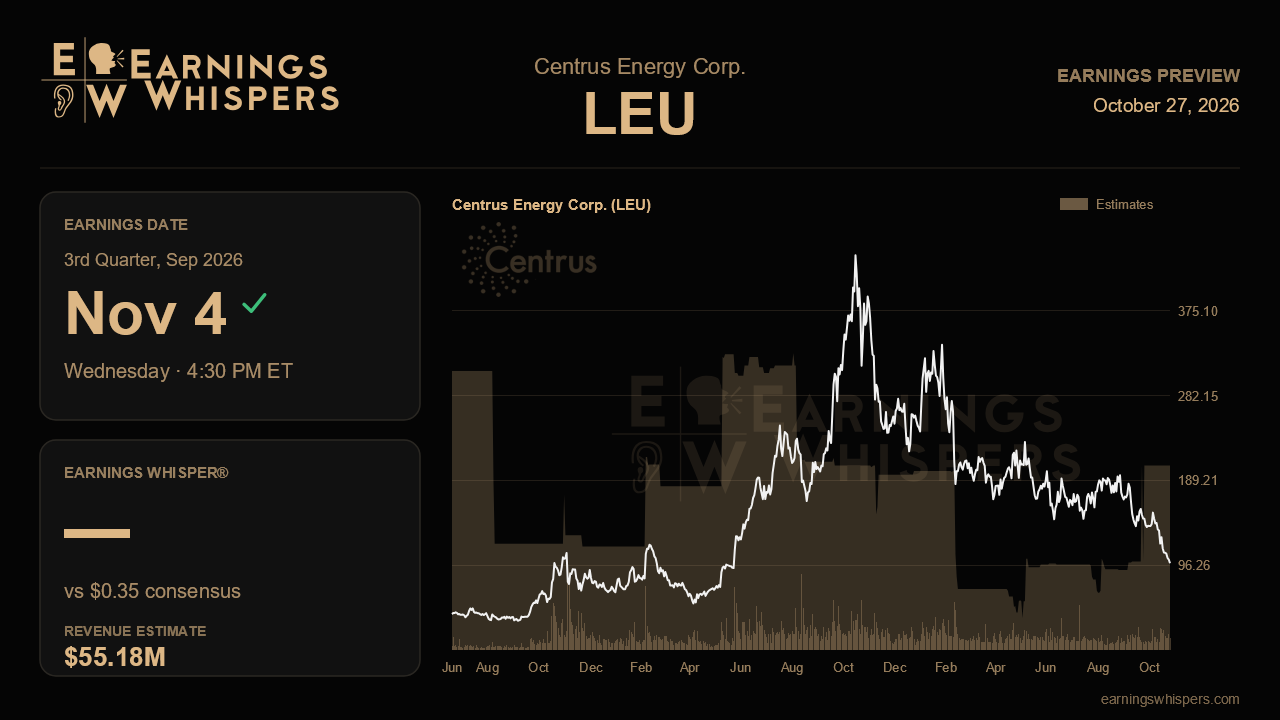
Centrus Energy heads into its third-quarter report with an unusual disconnect. Last quarter management described a business that had moved from waiting on Washington to executing on signed contracts, with a $900 million Department of Energy enrichment task order finalized, backlog contingencies cleared and revenue guidance nudged higher. The market's response since then has been brutal: the shares have lost roughly half their value, falling 51% while the S&P 500 barely moved. The report after the close on November 4 needs to show that the operating story is still intact even if the quarterly numbers look small.
They will look small. Analysts expect revenue of about $55.2 million, down 26% from $74.9 million a year ago and a fraction of the $176.1 million booked last quarter. Earnings are forecast at $0.35 a share, up from $0.19 in the year-ago period. That combination tells you how lumpy this business is. Enrichment deliveries follow customer contract timing rather than a smooth curve, so a soft revenue quarter is not by itself a warning sign. What matters more is the full-year picture. Management reaffirmed its 2026 revenue outlook of $450 million to $500 million, a range it raised from $425 million to $475 million earlier in the year. The Street sits at about $470.6 million, comfortably inside the range and just below the midpoint. Any hint that the fourth quarter cannot deliver the heavy lifting the guidance implies would matter far more than a miss on a seasonally thin third quarter.
The real scorecard is the build-out. Backlog climbed to $4.5 billion last quarter from $3.8 billion at the end of 2025, with $2.4 billion of the roughly $3 billion enrichment book under definitive agreements. Holding that figure steady, or converting more of it to definitive contracts, would validate the claim that demand for domestic enrichment is deepening. The Oklo letter of intent for up to five Aurora units is a natural candidate for progress, as is further detail on the X-Energy offtake. On the execution side, management promised a first centrifuge completed at Oak Ridge this year, said about 75% of critical suppliers were under contract, and lifted planned Piketon hiring to more than 175 people. Updates showing those milestones on schedule, plus any color on the idea of pulling commercial production forward from 2029, would support the narrative heading into December's first Investor Day.
The pressure points from last quarter remain live. Profitability compressed as uranium and enrichment costs rose, with per-unit SWU costs up 13% and LEU cost of sales up 36% from a year earlier, while stock compensation and advanced technology spending added to overhead. Technical Solutions revenue is also shrinking as the government operations contract winds down. Capital spending reached $82.2 million last quarter and is expected to accelerate, and cash slipped to about $1.9 billion. Investors should want evidence that gross margins are stabilizing and that spending is tracking the plan rather than creeping ahead of it.
Sentiment has softened its bearish edge, improving to a modestly negative reading from a more pessimistic one before the last report, even as the stock slid. Shares near $98 sit just above the post-earnings low of $96.80 and far below the 200-day moving average around $190, so the market has already priced in considerable doubt. That lowers the bar in one sense but also means fresh disappointment on costs or timelines could test whether support holds.
Ultimately, this quarter is less about the headline numbers than about confirmation. If Centrus reaffirms its full-year range, keeps backlog intact and shows the Oak Ridge and Piketon milestones moving on time, the contracted growth story from last quarter survives. If margins keep eroding or execution dates drift, the sell-off will start to look like a verdict rather than an overreaction.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-19 | |
| Sep-21 | |
| Sep-17 | |
| Sep-17 | |
| Sep-13 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-02 |
