LandBridge Must Show Its Record Quarter Was A New Baseline, Not A Spike
LandBridge enters its third-quarter report with an unusual burden. Last quarter it posted a record $66.8 million in revenue, up 31% from the prior quarter, and for the first time put numbers on its digital-infrastructure ambitions. This time the question is less about headline growth than about durability. Can the Permian landowner hold that higher revenue plateau, keep its water business ramping, and move any of its data-center talks closer to signed leases?
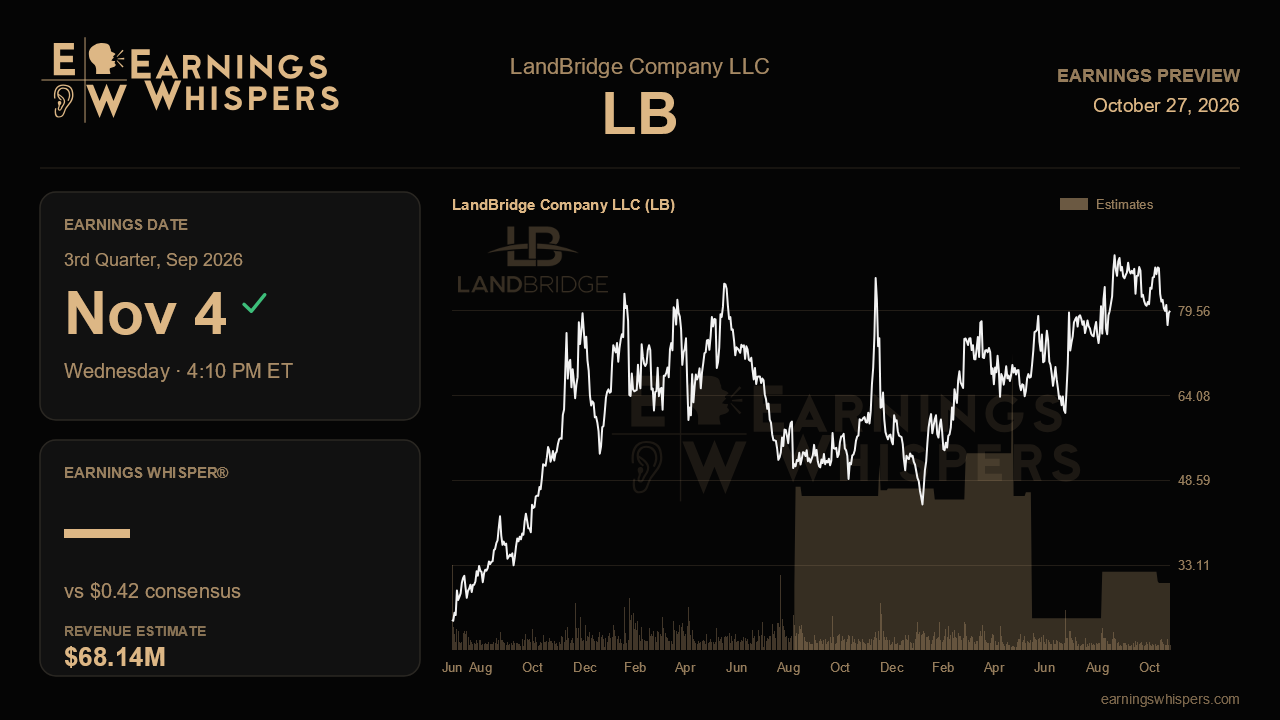
Wall Street expects earnings of $0.42 per share on revenue of $68.1 million, which would be gains of roughly 62% and 34% from a year ago. Those year-over-year figures look impressive, but the sequential picture tells the real story. Analysts are penciling in only about a 2% revenue increase over the second quarter, so the Street is effectively betting that the second-quarter jump was a new floor rather than a one-time spike. That framing lines up with management's full-year adjusted EBITDA guidance of $210 million to $230 million, which was raised after the first quarter and reaffirmed, not lifted again, last time. With first-half revenue near $118 million and EBITDA margins running in the high 80s, a quarter in the high $60 million range keeps the company on pace for the middle to upper part of that range. A clear beat could reopen the case for another increase. A shortfall would make the decision to merely reaffirm look prudent in hindsight.
The operating details matter more than the headline. Management said produced water volumes rose about 15% sequentially last quarter, well ahead of the roughly 5% it had planned, as WaterBridge and Speedway assets came online early. It also signaled that the Speedway pipeline ramp would continue through the second half. The report should show whether water handling royalties kept climbing or whether the early start simply pulled growth forward. Surface use royalties, up 41% sequentially last quarter, are the other key line, since they are the cleanest read on how intensively operators are using LandBridge acreage. Oil and gas royalties rose 20% on higher prices, which makes that stream the most exposed to commodity swings. Investors should also listen for any update on per-barrel royalty rates, which management said have room to rise as pore space grows scarcer.
The bigger strategic test is digital infrastructure. Management described seven counterparties representing more than 10 gigawatts under letters of intent, options, or late-stage documents, and said it expects several to convert into revenue-producing leases by the end of 2027. Nobody should expect lease revenue this quarter. What would strengthen the story is evidence of movement, such as an LOI turning into a definitive agreement, clearer power-delivery timelines, or confirmation that the Texas directive pausing new data-center approvals has not slowed talks. Management argued its behind-the-meter, brackish-water projects are insulated from that directive. This quarter's commentary will show whether that view holds up. Updates on the planned re-domicile as a Texas corporation, aimed at index eligibility, and on the recent landfill surface acquisition will round out the picture.
Sentiment has warmed considerably, rising to 57.4% bullish from 18.7% ahead of the prior report, yet the stock has gained only about 1% since then, barely ahead of a slightly lower S&P 500. At $79.58, shares sit above the 200-day moving average of $72.77 but well below the post-earnings high of $91.69 and closer to the $74 low. The market seems to have priced in some of the good news, run up on it, and then given much of that back.
The narrative stays intact if LandBridge shows that second-quarter revenue was a durable base, that water volumes are still compounding, and that the data-center pipeline is advancing despite the regulatory noise. Free cash flow margin, which slipped to 60% on acquisition spending, and net leverage of 2.5x are secondary checks. The main question is whether this quarter confirms that the business has moved permanently higher.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Sep-22 | |
| Sep-22 | |
| Aug-11 | |
| Aug-09 | |
| Aug-06 | |
| Aug-05 | |
| Jul-27 | |
| Jul-13 | |
| Jun-15 | |
| May-06 | |
| Apr-13 | |
| Apr-02 | |
| Mar-16 |
