LandBridge Beats And Raises As Alpha Data Center Lease Turns Binding, But A Debt-Funded Land Grab Keeps Investors Cautious
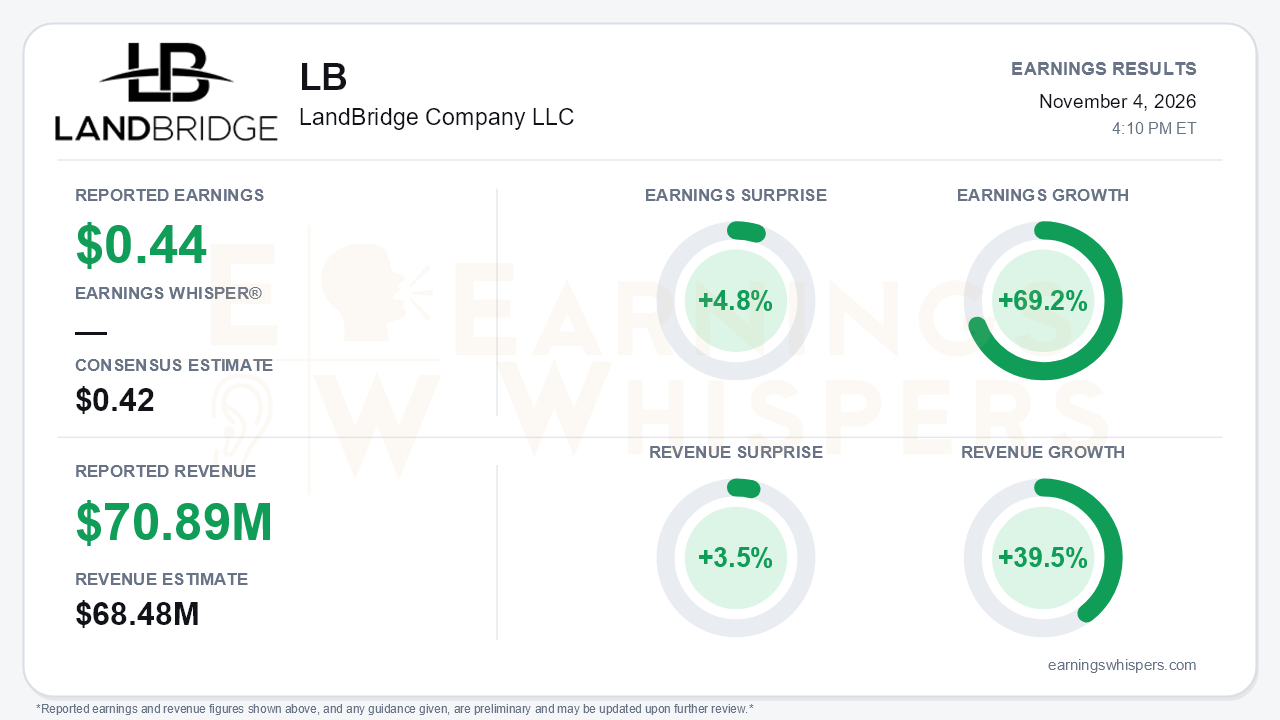
LandBridge delivered another record quarter. EPS of $0.44 topped the $0.42 consensus by 4.8%, and revenue of $70.89 million beat the $68.48 million estimate by 3.5%. Earnings grew 69.2% year over year and revenue grew 39.5%. Management raised full-year 2026 Adjusted EBITDA guidance to $220-$235 million, the second increase this year, up from $210-$230 million and from the original $205-$225 million range. The more consequential development was strategic. PowerBridge converted its Alpha Digital Campus option into a long-term ground lease with a power royalty and started construction. The central tension is how the next leg of growth is being financed: debt-funded acreage bought at a full multiple, at a time when sequential growth is cooling and the stock has been trending lower.
The quality of the quarter holds up well. All three revenue streams grew sequentially. Surface use royalties and revenue rose $2.1 million to $54.3 million, driven by higher produced-water volumes, including the Speedway Phase I ramp, and by pipeline easement revenue. Resource sales and royalties rose $1.4 million to $12.5 million, and oil and gas royalties rose to $4.1 million as net production increased to 917 boe/d from 773. Adjusted EBITDA reached $63.7 million at a 90% margin, up from 89% in Q2 and 88% a year ago. G&A was essentially flat year over year at $15.9 million while revenue grew by roughly $20 million, which is genuine operating leverage. GAAP net income of $34.0 million absorbed $9.1 million of share-based compensation, most of it tied to holding-company management units that the company says are non-dilutive and will not be paid in cash by LandBridge. Free cash flow jumped to $49.0 million (69% margin) from $40.2 million (60%) in Q2. One detail deserves scrutiny: related-party easement revenue rose to $10.9 million from $0.8 million a year earlier. That makes affiliate activity a growing share of the surface business.
Growth is also decelerating, as management had warned. Sequential revenue growth slowed to 6% from 31% in Q2. The CFO tied the guidance raise explicitly to the expected contribution from recent acquisitions starting in the fourth quarter. That means part of the higher outlook reflects acreage the company bought rather than purely organic momentum. The roughly $266.8 million spent on about 25,000 acres was priced at around 10x EBITDA, according to the call. Management laid out a path to below 6x through pore-space commercialization and eventually to 3x or less. That is a credible playbook given LandBridge's history, but it is a promise rather than a result, and disclosure on the acquired acreage remains limited.
The balance sheet absorbed the cost:
- **Borrowings:** $765 million, up from $545.2 million at the end of Q2.
- **Leverage:** 3.0x, up from 2.5x and above the 2-2.5x target.
- **Quarter-end cash:** $16.8 million.
- **Liquidity:** $126.8 million at quarter-end, before the October $125 million tack-on to the 6.25% 2030 notes restored it to roughly $252 million pro forma.
Interest expense has already climbed to $9.9 million from $7.9 million a year ago. Bears have legitimate ammunition here, especially if commercialization of the new acreage takes longer than management expects.
The offset is Alpha. Phase I covers 825 of the roughly 3,400 optioned acres and is expected to support more than 300 megawatts of a planned 2-gigawatt campus, with first power targeted for Q4 2027. Management framed the economics at $10-$20 million per gigawatt, implying about $20-$40 million annually at full build. Ground rents are expected to begin around the turn of the year, with material cash flow in the first half of next year. An anchor-tenant announcement was signaled as near term. This is the first binding conversion from a pipeline that management described last quarter as more than 10 GW across seven counterparties. The ramp spans several years, however, and Q&A raised Texas political and regulatory uncertainty around data centers, water and oil activity. Management nonetheless framed that backdrop as a tailwind for behind-the-meter, brackish-water sites.
The market has been unconvinced. Shares fell 12.1% from the $78.79 open after the August report to $69.26 and sit 5.9% below the 200-day moving average. Investor sentiment remained positive but weakened, slipping from 0.19 to 0.08, which suggests expectations had already cooled heading into the print. Several Earnings Whispers trend signals, including sequential growth, momentum and AVWAP, read positive, while price trend is neutral. That is a more constructive picture than the share-price slide alone implies.
The bottom line is that LandBridge's operating engine is doing exactly what the model promises: near-90% margins, rising free cash flow and a second guidance raise. Alpha has also moved from optionality to a signed lease under construction. What changed is the risk profile. Leverage now sits above target, organic growth is slowing from Q2's pace, and the thesis increasingly depends on commercializing expensive new acreage and landing an Alpha anchor tenant. Delivering on those catalysts would vindicate the debt. Until then, the stock's discount to its 200-day average reflects reasonable caution rather than a misread of the quarter.
Read our earnings preview for LandBridge Company LLC: https://www.earningswhispers.com/article/LB/21860
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-04 | |
| Oct-27 | |
| Oct-13 | |
| Sep-22 | |
| Sep-22 | |
| Aug-11 | |
| Aug-09 | |
| Aug-06 | |
| Aug-05 | |
| Jul-27 | |
| Jul-13 | |
| Jun-15 | |
| May-06 | |
| Apr-13 |
