Kimball Electronics Must Show Organic Growth Beneath Helvet's First-Quarter Boost
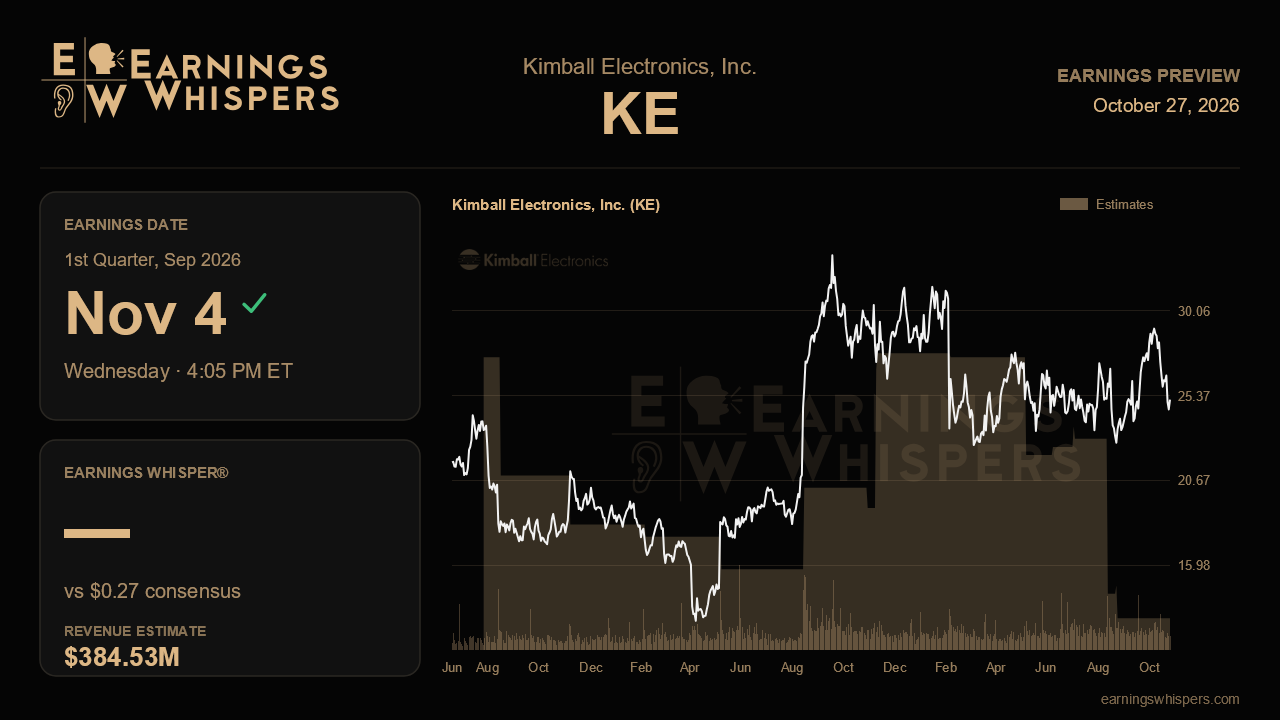
Three months ago Kimball Electronics stopped talking about getting through a transition year and started talking about growth again. Its fiscal first-quarter report, due after the close on November 4, is the first chance to check that pivot against real numbers. It is also the first quarter to include Helvet, the polymer business acquired on July 1. That makes the headline revenue figure less informative than it looks. The real question is whether the base business is actually growing.
Wall Street expects revenue of $384.5 million, up 5.2% from $365.6 million a year ago, and earnings of $0.27 per share, down roughly 45% from $0.49. On revenue, the Street is pacing close to the low end of management's fiscal 2027 range of $1.535 billion to $1.560 billion. A quarter of the bottom of that range is about $384 million. Helvet was framed as contributing roughly $60 million for the year, or about $15 million a quarter. Strip that out and consensus implies organic growth of only about 1%. That is well short of the 3% to 5% organic pace management laid out. Either analysts are assuming the growth is back-end loaded, or they are quietly skeptical. A print that clears consensus on revenue with a clean organic number in the guided range would be the clearest validation of last quarter's upbeat tone.
The earnings decline is less alarming than the percentage suggests. Management guided to a tax rate in the low 30s, above earlier expectations. It also flagged roughly $6.5 million to $7 million of drag from the new Indianapolis medical facility, which does not begin production until the end of calendar 2026. That means this quarter carries the cost of the plant with none of the revenue. Adjusted operating margin was guided to 4.4% to 4.7%, essentially flat with fiscal 2026, as Helvet's accretion offsets the Indianapolis burden. The fourth quarter's 8.9% gross margin was the best of the year. Holding near that level would suggest margins have found a floor. Slipping back toward the high 7% range seen in the third quarter would undercut the idea that profitability has stabilized.
The mix matters as much as the total. Medical, now rebranded as a co-development business, grew in all four quarters of fiscal 2026 and was guided to high-single to low-double-digit organic growth, approaching 35% of sales. That segment has to carry the story. Automotive is guided only flat, with North American EV programs soft and Chinese competition fierce. Industrial remains weighed down by weak HVAC demand. Any further deterioration in those two segments would put more pressure on medical than one segment can comfortably absorb. Early commentary on revenue synergies from Helvet, which management described as an impressive list, would help show whether the deal is more than a bolt-on revenue line.
The balance sheet deserves a look too. Cash conversion days improved to 82 last quarter, and borrowings fell to $116.6 million. Management warned that working capital would creep higher as supply-chain disruptions and customer requests for extra inventory build stock. A modest increase is expected. A sharp one, or a step-up in debt beyond what the Helvet purchase explains, would be a warning sign.
Sentiment has soured noticeably, swinging from mildly bullish before the last report to clearly bearish now. Yet the stock has risen 9.5% since then, beating the S&P 500 by nearly 11 points. At $25.14, shares sit slightly below their 200-day moving average and well off the post-earnings high of $29.20. Some of the early enthusiasm has already leaked out, which arguably lowers the bar. Ultimately, this report hinges on one number buried beneath the acquisition: organic growth. If the core business is expanding near the guided rate while margins hold, the turnaround narrative stays intact. If Helvet is doing all the lifting, the growth story looks borrowed rather than earned.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-29 | |
| Jul-15 | |
| Jul-01 | |
| May-19 | |
| May-05 | |
| May-05 | |
| Apr-22 | |
| Mar-19 | |
| Mar-10 |
