Kimball Electronics Misses On Earnings, But Revenue Turns Higher As Medical Pushes Sales Guidance To The High End
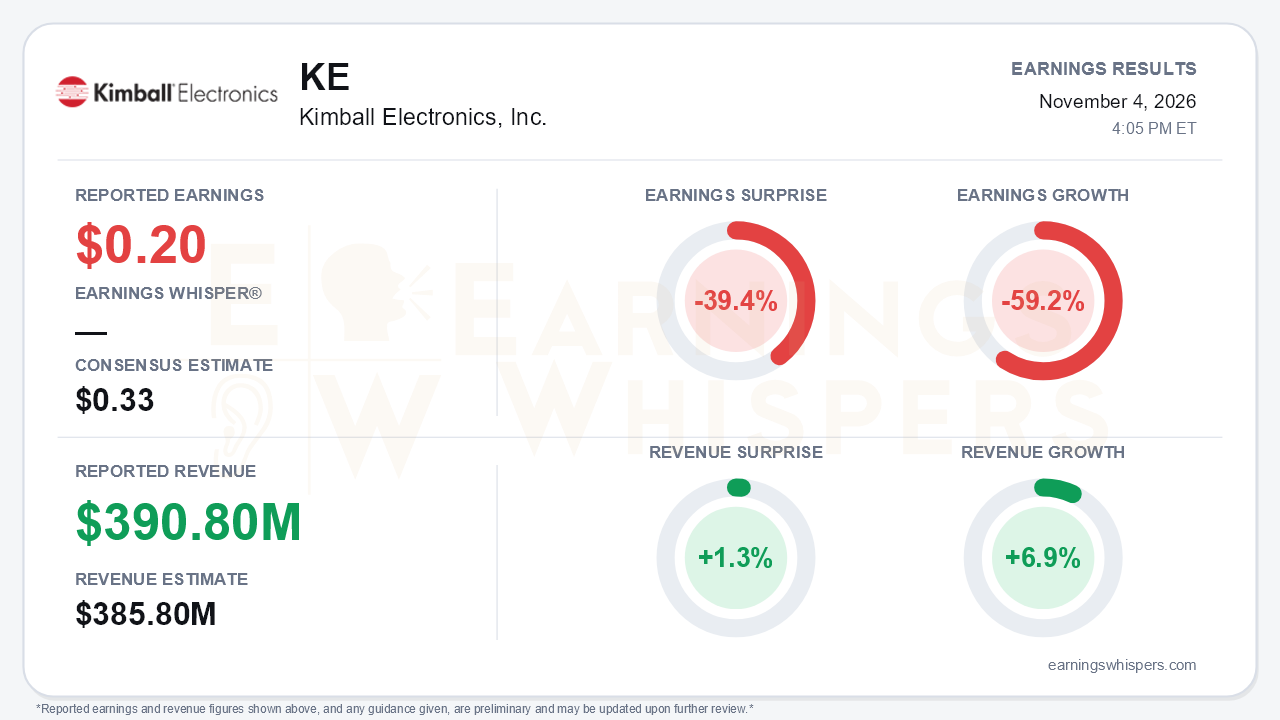
Kimball Electronics (NASDAQ: KE) delivered a quarter with two different stories. Revenue grew 6.9% year over year to $390.8 million, topping the $385.8 million consensus by 1.3% and marking the company's first year-over-year sales gain after declines of 2%, 6%, and 5% in the prior three quarters. Earnings moved the other way. Earnings Whispers puts fiscal first-quarter EPS at $0.20, 39.4% below the $0.33 consensus and down 59.2% from a year ago. That is the central tension: the top line has turned, but very little of that improvement reached the bottom line this quarter.
The per-share figures need some explanation. Kimball's own adjusted EPS was $0.25, down from $0.49, and GAAP diluted EPS fell to $0.11 from $0.40. The Earnings Whispers normalized $0.20 sits between those two numbers and is the basis for the surprise and growth comparisons above. Whichever measure investors use, the beat-versus-miss picture is the same.
Tax was the largest single drag. A 66.1% rate, driven by withholding on cash repatriation, left only $2.6 million of GAAP net income from $7.8 million of pretax income. That charge is not recurring, but the other pressures are more structural:
- **Higher interest cost.** Interest expense rose to $3.5 million from $2.4 million after borrowings to fund the Helvoet Polymer Technologies acquisition.
- **Margin slippage.** Gross margin was 7.9%, flat year over year but down from 8.9% in the fourth quarter.
- **Below-guide profitability.** Adjusted operating margin slipped to 4.3%, compared with 4.9% last quarter and 4.8% a year ago. That is below the full-year guide of 4.4% to 4.7%, which management held rather than raised.
The quality of the beat on revenue holds up better than the quality of the earnings. Organic growth was a modest 3%, with Helvoet contributing $12.4 million and currency adding roughly a point. Growth was broad, though:
- **Medical:** up 14%, or 9% organically.
- **Industrial:** up 5%, after three straight quarterly declines.
- **Automotive:** up 4%, after falling 13% two quarters ago.
The automotive gain needs a caveat. On the call, management acknowledged that some auto revenue reflects pass-through of component inflation and carries little or no margin. That helps explain why sales are improving faster than profitability. Medical organic growth also slowed from 12% a year earlier. Management, however, said the first quarter may be the low point of the year and that it now expects double-digit core medical growth. That is a step up from the earlier high-single to low-double-digit outlook.
The forward indicators were the most constructive part of the report:
- **Backlog.** Open orders rose 16% year over year to $690 million, up from $643 million in June.
- **Guidance.** Kimball reiterated its fiscal 2027 sales range of $1.535 billion to $1.560 billion but now expects to land at the high end.
- **Capacity.** Production at the new Indianapolis medical CDMO facility is slated to begin in December.
- **Integration.** Helvoet integration is described as on plan and on budget, with top-line synergies prioritized.
- **Other programs.** Management cited a new steering program ramp in Poland and new climate-control opportunities.
The tone was noticeably more confident, with management saying its enthusiasm for Helvoet is higher than ever.
Bears still have legitimate ammunition. Operating cash flow was negative $19.3 million, ending a 10-quarter positive streak, as inventories rose about $40 million to $312.1 million. Debt roughly doubled to $235.7 million from $116.6 million. Cash conversion days held at a multiyear low of 82, which suggests the inventory build is partly tied to higher activity. Even so, the combination of rising leverage, memory and component tightness, and continued weakness in North American EV and HVAC demand leaves little room for execution errors. Keeping the margin guide unchanged until inflation becomes clearer signals that management sees the same risk.
Investor sentiment cooled heading into the report. It slipped from a modestly positive 0.058 to essentially neutral at -0.007, a meaningful but not dramatic shift. The stock, meanwhile, had gained 12.7% since the open following the August report, to $25.86, and sat just 0.7% above its 200-day moving average of $25.67. Price and momentum trends have been positive, while the AVWAP reading remains negative. That leaves the shares balanced near a key long-term average rather than trading with a clear cushion, which matters after an earnings miss of this size.
The bottom line is that Kimball's quarter showed real top-line inflection: broad-based growth, a medical franchise expected to accelerate, a fuller order book, and a nudge to the high end of sales guidance. Profitability, cash flow, and the balance sheet all moved the wrong way, and part of that strain came from acquisition costs, a one-time tax hit, and margin-light inflation revenue. The investment case now depends on whether Indianapolis and Helvoet convert growing medical volume into margin improvement toward the guided 4.4% to 4.7% range. Until that shows up, the earnings miss will weigh as heavily as the revenue beat.
Read our earnings preview for Kimball Electronics, Inc.: https://www.earningswhispers.com/article/KE/21857
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-29 | |
| Jul-15 | |
| Jul-01 | |
| May-19 | |
| May-05 | |
| May-05 | |
| Apr-22 |
