Inseego Braces For A Trough Quarter As Cash, Margins And The Nokia Deal Take Center Stage
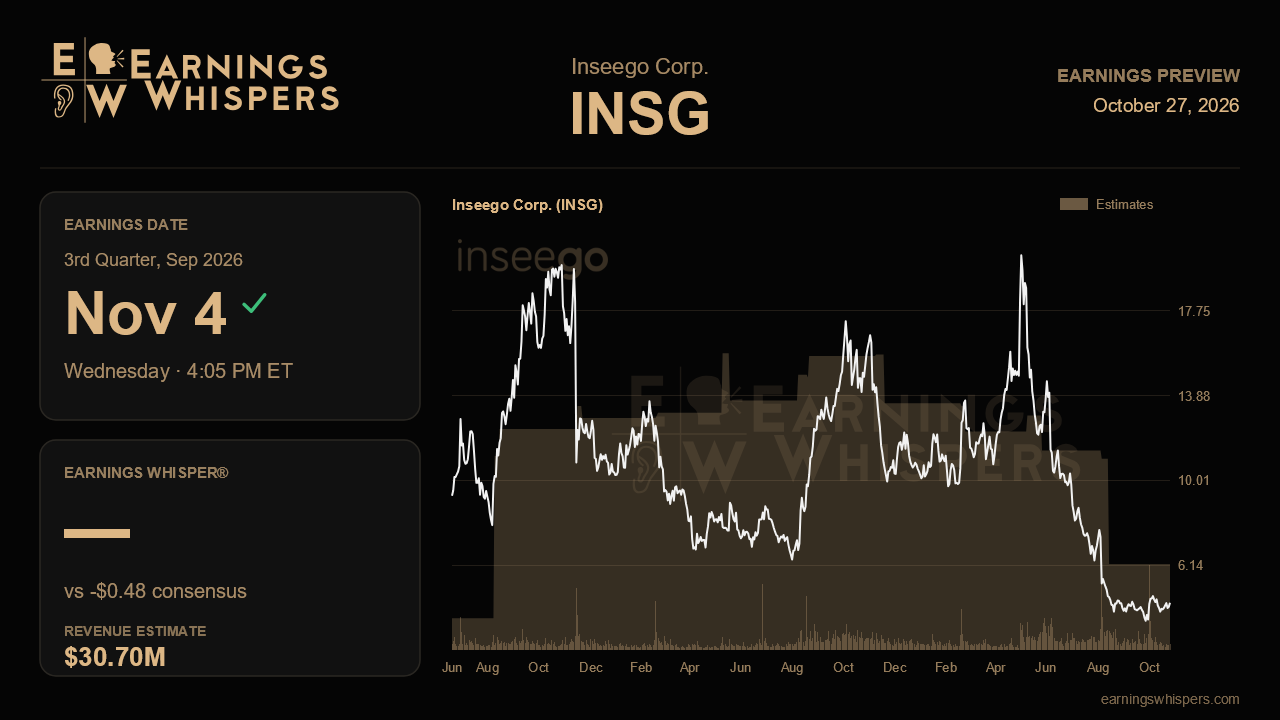
Inseego enters its third-quarter report with the hard part of the bad news already out. In August, management cut its full-year revenue outlook from about $190 million to roughly $155 million and warned that the September quarter would be the low point, with revenue falling sharply and adjusted EBITDA turning negative. The question for the November 4 release is less whether results look ugly, since they are expected to, and more whether this is a controlled trough that clears the way for the transformational Nokia fixed wireless acquisition, or the start of something messier.
The Street has largely accepted management's framing. Consensus calls for revenue of $30.7 million, comfortably inside the company's $28 million to $35 million range and a touch below its $31.5 million midpoint. That would be a 33.1% drop from the $45.9 million reported a year ago and a steep slide from the $44 million posted last quarter. Analysts expect a loss of $0.48 per share, wider than the $0.37 loss last quarter and a stark contrast with breakeven results a year earlier. The width of the guidance range is itself telling: a $7 million spread on a roughly $30 million quarter signals limited visibility, so landing anywhere inside it is less important than the explanation behind the number.
Several swing factors from the last call deserve close scrutiny. Roughly $5 million to $6 million of second-quarter revenue was pulled forward, and management said that would depress third-quarter orders, so a clean read on underlying mobile demand will require separating timing from trend. Mobile was the bright spot last quarter, up 26% year over year on the MiFi Pro M4 launch across all three Tier 1 carriers, and that momentum needs to survive the pull-forward hangover. The bigger worry is fixed wireless, where the largest customer's recovery has been slower than hoped amid its own organizational changes. Any sign that this customer is stabilizing would be the most encouraging data point in the report. Subscribe services are also stepping down by about $2 million a quarter as its sole customer brings work in house, a known headwind that should not surprise.
Margins are where management made its most testable promise. Non-GAAP gross margin fell to 34% last quarter from 43% for 2025, partly because the company used higher-cost memory to fill an upsized order. Management expects product gross margin to recover to the high teens as memory cost pass-throughs take hold. Evidence that pricing is actually sticking with carriers would validate that claim; another quarter of memory-driven compression would suggest Inseego has less pricing power than it hopes. Investors should also look for an update on the long-running search for an engineering leader, since engineering processes that could not scale were the root cause of the product delays behind the guidance cut.
The balance sheet may matter most of all. Cash dwindled to about $2 million at the end of June with $10 million drawn on the revolver, and a quarter of negative EBITDA leaves little cushion. Clarity on liquidity and on financing ahead of the Nokia close, targeted for the fourth quarter, is essential. That deal, with a run rate near $200 million and an EBITDA make-whole funding Nokia's roadmap, would more than double the business, but only if Inseego can absorb it while repairing its own house. Notably, the full-year outlook implies a meaningful fourth-quarter rebound, so the tone of commentary on year-end demand carries real weight.
The market has already rendered a harsh verdict. Shares are down 23.6% since the last report against a roughly flat S&P 500, and at $4.43 the stock sits far below its 200-day average of $9.54 and in the lower half of its post-earnings range of $3.58 to $5.94, a world away from last quarter's $6.22 to $16.78 range. Bullish sentiment has faded to 26.2% from 45.7%. Expectations are low, but so is tolerance for new problems. The narrative stays intact if Inseego lands inside its range, shows margin repair, reassures on cash and keeps the Nokia close on schedule; another guidance trim or financing scare would undercut the case that the worst is behind it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-01 | |
| Sep-29 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-16 | |
| Jun-30 | |
| Jun-25 | |
| May-07 | |
| May-07 |
