Inseego Clears A Lowered Bar, But A Shrinking Core And Nokia-Funded Q4 Outlook Dominate The Story
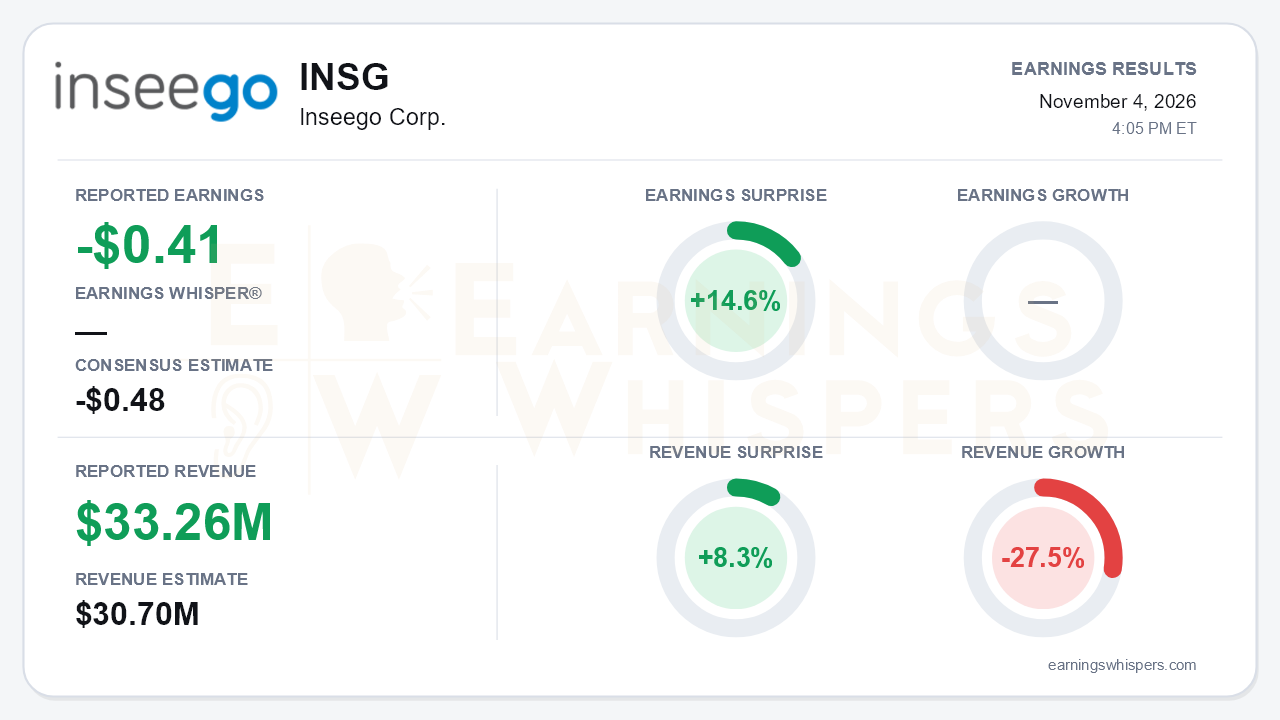
Inseego (NASDAQ: INSG) beat expectations on paper. Earnings Whispers normalized the third-quarter loss at $0.41 per share, versus a consensus loss of $0.48, a 14.6% positive surprise. Revenue of $33.26 million topped the $30.7 million consensus by 8.3%, and the Q4 revenue guide also landed above estimates. The headline flatters a deteriorating business, though. Revenue fell 27.5% year over year and roughly 24% sequentially from $44.0 million in Q2. The company swung from a GAAP profit of $0.03 per share a year ago to a GAAP loss of $0.49. Investors should note the reconciliation: the release shows a GAAP loss of $0.49 and a non-GAAP loss of $0.27, and the normalized figure falls between them. On every basis, the loss widened from Q2's non-GAAP $0.18 and from a $0.12 non-GAAP profit a year earlier. This was a beat against expectations that had already been cut sharply, not evidence of a turn.
The quality of the quarter deserves scrutiny. Fixed wireless access revenue collapsed to $4.2 million, from $14.4 million in Q2 and $17.7 million a year ago. Software services slipped to $10.0 million from $12.3 million sequentially as Subscribe repricing took hold. Mobile solutions was the lone bright spot, rising 10% sequentially to $19.1 million. Management tied part of that gain to carrier pre-buys ahead of component price increases, which likely pulled demand forward. Carrier destocking is already weighing on Q4 orders. GAAP gross margin fell to 33.3% from about 41.6% a year ago, and only after absorbing a $1.8 million inventory reserve. Adjusted EBITDA turned negative at -$1.0 million, compared with +$5.8 million a year earlier. The balance sheet is the more urgent problem. Cash fell to $6.6 million from $24.9 million at year-end, and $7.6 million is drawn on the working capital facility. Inventories nearly tripled to $20.5 million, payables rose to $36.9 million, and the stockholders' deficit widened to $36.6 million.
The call laid bare how far the narrative has eroded. After the Q4 FY25 report, the FY26 standalone outlook was roughly $190 million with double-digit growth and 12% EBITDA margins. It fell to about $155 million in Q2. The new Q4 North America guide of $21 million to $25 million implies something closer to $130-140 million. The next-generation FWA product slipped from Q4 2026 to Q1 2027 because of printed circuit board lead times. That product is central to winning back the largest FWA customer, so that recovery moves into 2027. Management's tone shifted from "bullish on 2026" to "not satisfied" and "a lot of work to do." CEO Juho Sarvikas acknowledged engineering and product delivery issues. He has installed a new CTO, Nick Lambourne, and begun restructuring engineering.
The Nokia FastMile acquisition, closed October 1, is now the core of the story, and it carries both the upside and the risk. FastMile is guided to $35-40 million in Q4. That compares with $68.9 million in Q4 2025 and the roughly $50 million per quarter behind the $200 million run-rate cited earlier. The implied run-rate is now about $140-160 million. Margins are thin: management cited 10-13% gross margins, while the carve-out data show results as low as 3.6% in Q2. Consolidated Q4 adjusted EBITDA of $0-2 million includes $12-14 million of Nokia support payments, which implies a sizable underlying loss. That gap must close before the support ends. An accounting change that capitalizes less software development will also lower reported EBITDA going forward.
There are genuine offsets:
- Nokia is investing $10 million of equity plus a $10 million engineering support payment.
- FastMile's anchor customer in India renewed through 2028 with a minimum purchase commitment.
- A Tier-1 carrier awarded Inseego a premium-tier MiFi, with shipments expected around mid-2027.
- October cuts should remove about $8 million in annual spend, after non-GAAP opex already fell to $14.8 million from $16.9 million.
Much of that payoff is a 2027 story, however. Memory and component inflation remains a threat in low-ARPU markets such as India.
Investors entered the report far less enthusiastic than they had been. Earnings Whispers sentiment remained positive but weakened meaningfully, falling from 0.46 to 0.27. Shares closed at $4.53 before the release, down 21.9% from the $5.80 open after the August report and 51.6% below the 200-day moving average of $9.36. The stock set a 52-week low of $3.58 on September 29 and has since rebounded about 26%. It still sits roughly 24% below its post-August high. The Earnings Whispers trend signals lean negative, with momentum deteriorating, although AVWAP is a modest positive tied to the recent rebound.
The bottom line is that Inseego beat a lowered bar while its standalone business shrank, its key product slipped, and its acquired asset arrived well below its advertised run-rate. The Q4 outlook rests heavily on Nokia's support payments, and the cash cushion is thin. Bulls have a new CTO, a renewed anchor customer, and real cost cuts to point to. Bears have legitimate ammunition until FastMile integration proves it can reach break-even without Nokia's help.
Read our earnings preview for Inseego Corp.: https://www.earningswhispers.com/article/INSG/21853
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-01 | |
| Sep-29 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-16 | |
| Jun-30 |
