McKesson's Whisper Number Runs Far Ahead Of Consensus As Generics Pull-Forward Tests Momentum
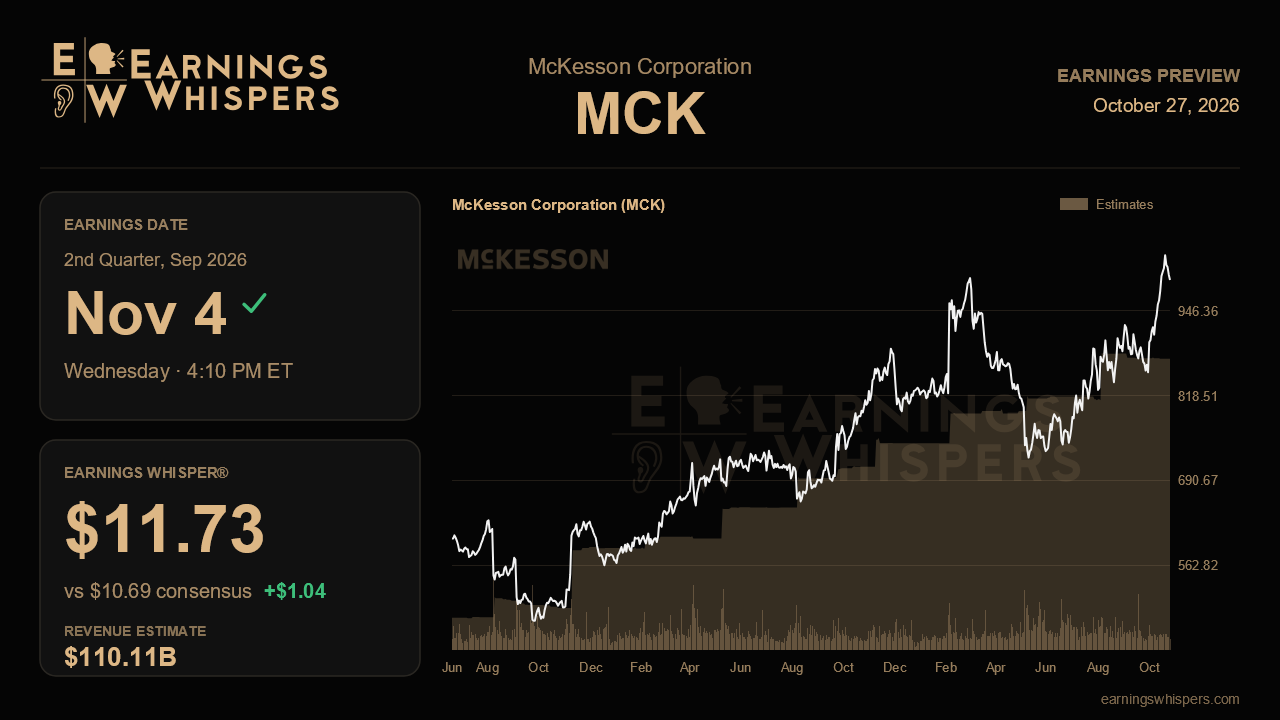
McKesson heads into its fiscal second-quarter report with an unusual gap between what the Street officially expects and what the market seems to be quietly hoping for. Consensus calls for earnings of $10.69 per share, up 8.4% from $9.86 a year ago, on revenue of roughly $110.11 billion, a 6.8% gain. The Earnings Whisper sits at $11.73, about 10% above consensus. That is not a rounding difference. It suggests that after a 20% jump in adjusted EPS last quarter, many investors see the published estimate as a low hurdle and expect McKesson to clear it comfortably.
The tension is that the official forecast implies a sharp slowdown, and management gave a reason for at least part of it. Generics favorability was pulled forward into the first quarter, which flatters that period at the expense of later ones. An 8% earnings growth rate after 20% looks like that timing shift showing up. The full-year picture supports the more upbeat view. McKesson lifted fiscal 2027 EPS guidance to $44.20 to $45.00 from $43.80 to $44.60, an off-cycle raise only one quarter after setting the range, and it implies 15% to 17% growth excluding items, above the company's 13% to 16% long-term target. Yet the full-year consensus of $44.28 sits near the bottom of that range. Either analysts are skeptical, or they have not fully caught up. A second-quarter result near the whisper would argue for the latter and push estimates toward the midpoint.
The core distribution business is the place to look first. North American Pharma operating profit rose 19% to $894 million last quarter, faster than in any of the prior three quarters, and management moved its full-year growth outlook for the segment to the high end of a 5.5% to 9.5% range. Holding that pace even as the generics benefit fades would confirm that the strength is about volume and efficiency rather than timing. GLP-1 distribution is a second gauge. That revenue reached $15 billion, up 24% from a year earlier and 13% from the prior quarter, a rebound after a sequential dip earlier in the year, and McKesson began supporting the Medicare GLP-1 Bridge Program in July. Continued sequential growth would help explain any revenue upside. Oncology and multispecialty, where operating profit climbed 41% with Florida Cancer performing at the high end of the acquisition case, needs to show that the growth is lasting.
The weaker spots could challenge the story. Medical-surgical, being rebranded as Wellverse ahead of standalone operations in January 2027 with Apollo now holding about 13%, saw operating profit fall 20% on product mix and one-time costs. That was its third straight decline. Signs of stabilization matter for how the separation is valued. Free cash flow was negative $372 million last quarter. That was better than a year ago, but analysts have noted it lagging earnings for two years, and the full-year guide of $4.5 billion to $4.9 billion remains below prior levels. Investors should also look for any new detail on the 340B reform proposal and the IRA Part B changes due in 2028, which management called manageable. The $5 billion buyback, half of it completed in the first quarter, provides a per-share tailwind.
The stock has already priced in much of the optimism. Shares are up 8.8% since the last report while the S&P 500 slipped 0.6%, and at $992.87 they trade about 15% above the 200-day moving average and within 4% of the post-earnings high of $1,030.27. Sentiment has become slightly more bearish, moving to 5.2% bearish from 1.2% bearish, a modest shift that hints at some wariness after the run.
The central question is whether McKesson can show that first-quarter strength was more than a generics windfall. If pharma margins hold up and cash flow improves while earnings slow as expected, the raised guidance looks conservative. If the slowdown runs deeper than timing explains, a stock this extended has little room for error.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 |
CD&R, McKesson to Acquire At-Home Infusion Therapy Provider for $5.8 Billion
MCK
The Wall Street Journal
|
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 |
