McKesson Falls Just Short Of A Lofty Whisper But Raises Its Outlook Again As Pharma Distribution Accelerates
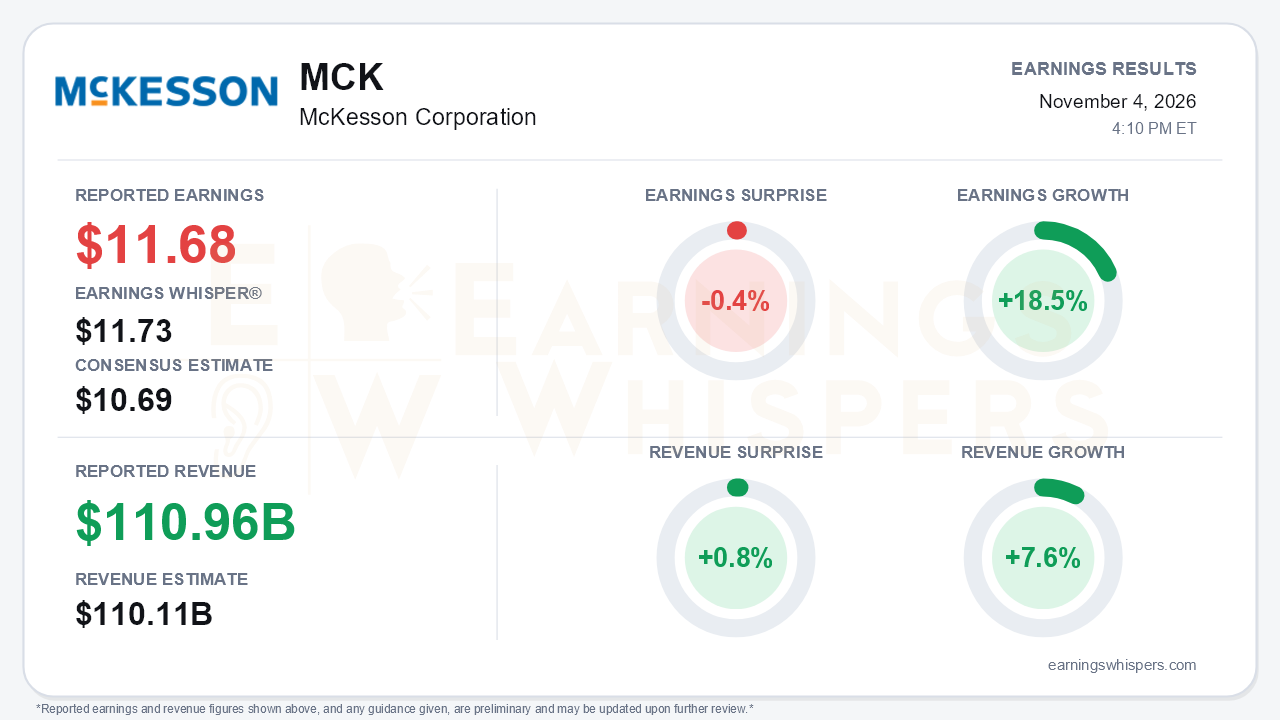
McKesson's fiscal second quarter cleared the bar most of the Street set but not the one investors set. Adjusted EPS of $11.68 rose 18.5% year over year and comfortably topped the $10.69 consensus. It still came in 0.4% below the $11.73 Earnings Whisper number, a technical miss against an elevated expectation. Revenue of $110.96 billion grew 7.6% and beat consensus by 0.8%. The narrow whisper shortfall is the least important part of the report. That is the central tension: a stock priced for a big beat delivered a slightly smaller one, while the underlying business and the full-year outlook improved meaningfully.
The quality of the quarter is better than the headline surprise implies. Management said adjusted EPS grew 24% excluding prior-year items, so the 18.5% reported growth understates the operating trend. Free cash flow swung to $2.9 billion from negative $372 million in the first quarter. That keeps the $4.5 to $4.9 billion full-year target intact and supports roughly $5 billion of buybacks, of which $3.4 billion is already done. The full-year adjusted EPS guide rose to $45.60 to $46.40. That compares with $44.20 to $45.00 after the first quarter and $43.80 to $44.60 at the initial outlook. The raised range implies 19% to 21% growth excluding items, well above the company's 13% to 16% long-term target.
The call showed growth accelerating, not just holding. North American Pharmaceutical operating profit grew about 22%, up from 19% in the first quarter and 11% in the fourth quarter of fiscal 2026. The segment's full-year profit growth guide jumped to 14% to 18% from the high end of 5.5% to 9.5%. GLP-1 distribution revenue climbed to $16 billion, up 26% year over year and from $15 billion and $14 billion in the two prior quarters. Oncology & Multispecialty was equally strong:
- Revenue rose 24%.
- Operating profit rose 23% excluding gains.
- Same-store patient visits were at recent highs.
- The revenue guide was lifted to 20% to 24%.
RxTS operating profit growth accelerated to 18% from 13%. Consolidated operating profit growth guidance now stands at 12% to 16%, versus 9% to 13% a quarter ago.
The soft spots are real but contained. Medical-Surgical operating profit fell 10% on ambulatory product mix, and the full-year guide was cut to a 4% decline to flat from flat to up 4%. Interest and corporate expense are now expected at the high end of their ranges. Management is also accelerating second-half investment in pharma and oncology, which could temper margin leverage. Bears have legitimate ammunition elsewhere too:
- Pharma profit growth is running far above its 5% to 8% long-term target, which raises sustainability questions.
- GLP-1 Bridge Program prior authorization volumes are normalizing after an initial surge.
- A possible January 2027 340B rebate model adds policy uncertainty, though management sees no material impact.
Strategically, McKesson took on more ambition. It closed the roughly $2.25 billion Precision Medicine Group acquisition, its first entry into contract research. Management expects the deal to add $0.10 to $0.20 to fiscal 2027 EPS and $1.60 to $1.80 of accretion by year three, though integration risk comes with it. The company also agreed to take a 49% stake in Option Care Health alongside CD&R for about $1.4 billion. That deal is expected to close in the first half of calendar 2027 and is not in guidance. Separately, McKesson extended its CVS Health distribution contract through June 2032, removing a key customer overhang.
The market setup is more complicated than the fundamentals alone suggest. Investor sentiment turned more negative heading into the report, falling from roughly neutral at -0.01 to -0.15. That is a noticeable cooling even as the stock kept climbing. Shares were up 9.6% since the open after the prior report and sat 15.7% above the 200-day moving average. They traded about 3% below the $1,030.27 52-week high set on October 20, near the top of an inter-earnings range that bottomed at $837.88 in August. The Earnings Whispers trend signals were uniformly positive. That combination of a stretched price, an aggressive whisper number and fading enthusiasm helps explain why a 9% consensus beat could still register as a miss.
The bottom line is that McKesson delivered its second straight beat-and-raise, with accelerating profit growth in its two largest engines and guidance now well above long-term targets. The whisper shortfall reflects how high expectations had climbed, not any break in the story. The open questions are durability: how sustainable the GLP-1-driven pharma growth is, how Med-Surg stabilizes, and how cleanly management executes the move into CRO and home infusion.
Read our earnings preview for McKesson Corporation: https://www.earningswhispers.com/article/MCK/21870
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours |
The Biggest Drug Wholesaler Just Crushed Earnings Views - Here's What To Know
MCK +6.98%
Investor's Business Daily
|
| 5 hours | |
| 6 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 |
CD&R, McKesson to Acquire At-Home Infusion Therapy Provider for $5.8 Billion
MCK
The Wall Street Journal
|
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 |
