Matson's Peak-Season Payoff Is Priced In; The Fourth-Quarter Rate Outlook Is The Real Test
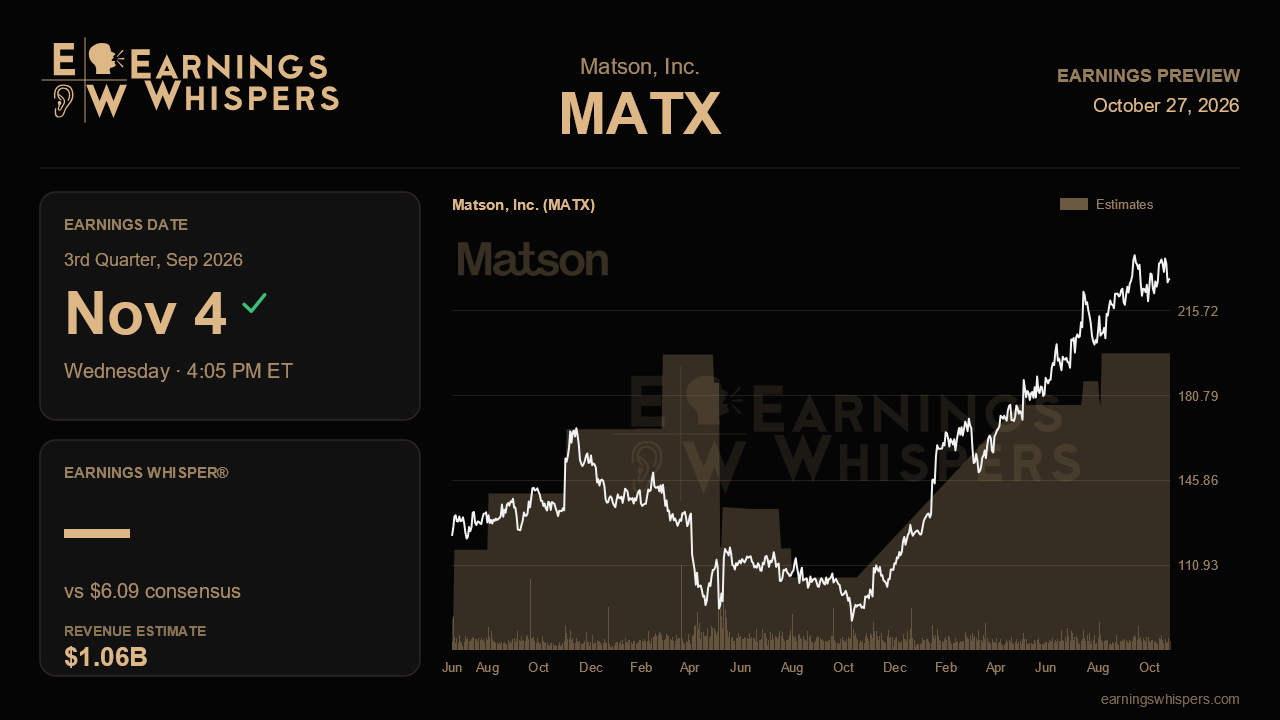
Matson heads into its third-quarter report with an unusual problem: management has already told the market roughly how good the quarter should be. On its August call, the company guided third-quarter ocean transportation operating income up about 45% from a year earlier, on the back of a trans-Pacific market strong enough to surprise even its own executives. With that number effectively on the table, the result itself may matter less than what Matson says about how long the strength lasts once peak season fades.
Wall Street expects earnings of $6.09 per share on revenue of about $1.06 billion when Matson reports after the close on November 4. That works out to growth of roughly 44% in earnings and 20% in revenue from the year-ago quarter, which earned $4.24 a share on $880.1 million in sales. It is also a sharp step up from the $4.27 and $969.4 million posted last quarter. The Street's earnings growth estimate lines up almost exactly with management's ocean guidance. In other words, analysts have taken the company at its word and left little room for error in either direction. A meaningful beat probably requires either China rates holding up better than planned through September or less drag from the domestic businesses.
The narrative behind those numbers has improved steadily all year. In February, management expected 2026 operating income to come close to the $499.8 million earned in 2025. By May, the outlook had moved to modestly exceeding that figure. In August, the tone turned openly upbeat, with China ships running full or nearly full and premium freight rates that management described as very satisfactory. Just as important, the second-quarter rate gains were attributed to market demand rather than fuel surcharges, which makes them higher quality. A third-quarter print that confirms full ships and premium yields would validate that story. A further lift to the full-year operating income outlook would extend the pattern of upward revisions. Holding the line at the prior wording would read as a pause.
The risks are mostly about what comes next. Management has already flagged that rates will step down in the fourth quarter as peak season ends. That is normal seasonality, but the size of that decline will shape 2027 estimates. Matson also still describes the broader trans-Pacific as structurally oversupplied, so any hint that premium pricing is eroding faster than usual would undercut the bull case. The Southeast Asia business, now 20% to 25% of China service volume across Vietnam and Thailand, is a strategic win. However, it carries slightly lower all-in rates and higher costs than direct China cargo, so its growing share bears on margins. At home, Hawaii has been sluggish amid soft tourism, the SSAT terminal joint venture is guided below last year's $32.5 million, and logistics is only approaching prior-year levels. Any further slippage there would weigh on consolidated results even if the ocean side delivers.
The market has not given Matson much credit for the guidance. The stock is up just 0.4% since the last report, slightly trailing the S&P 500, and sentiment has cooled from 41.6% bullish to 19.1% bullish. Shares at $228.85 sit comfortably above the 200-day moving average of $190.66 and in the upper half of the post-earnings range of $201.61 to $240.87. That suggests investors accept the strong quarter but doubt its durability.
That doubt is the crux of the report. Hitting the 45% ocean target is the minimum. The narrative stays intact if Matson pairs it with a measured fourth-quarter rate decline, continued full ships into year-end, and confidence that the first Aloha-class vessel, still on schedule for early 2027, will add profitable capacity rather than land in a softening market.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-12 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-15 | |
| Jul-15 | |
| Jul-08 | |
| Jun-25 | |
| Jun-10 |
