Macerich Must Prove Its NOI Inflection Was No Fluke As Acquisitions Take Center Stage
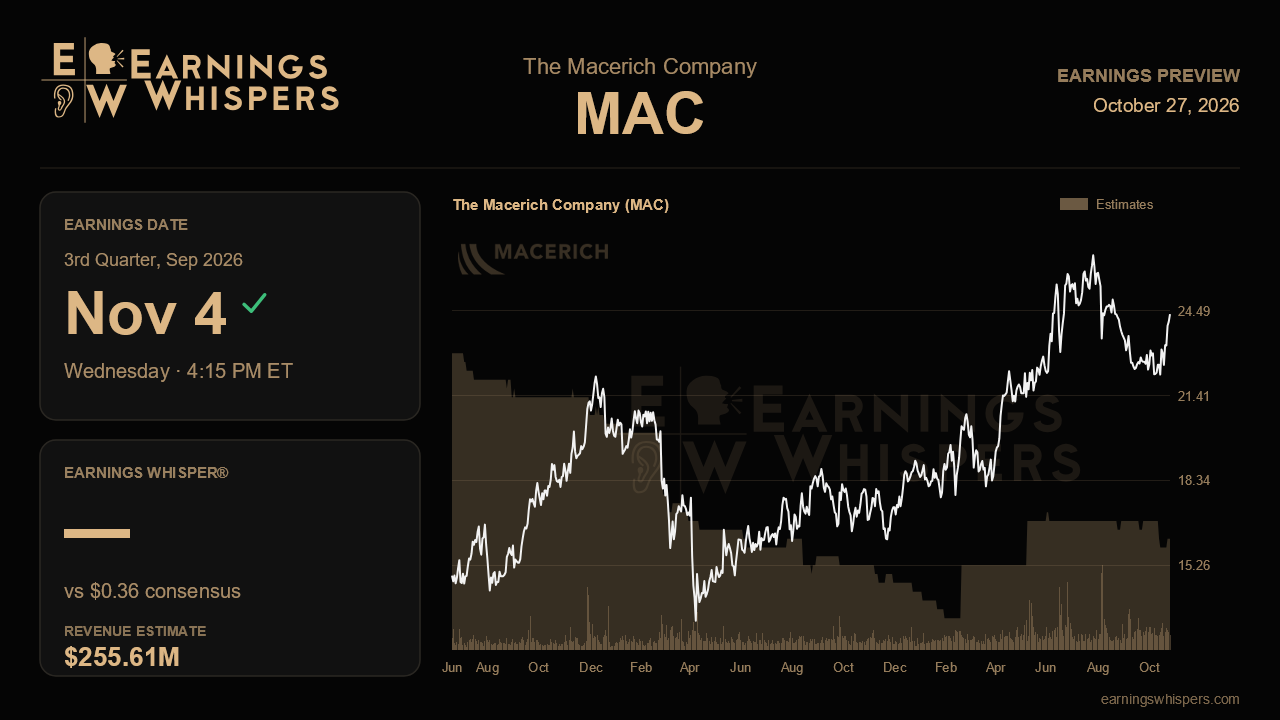
Last quarter Macerich finally gave investors the number they had been waiting for. After hovering in a sleepy 1.2% to 1.8% band for three straight calls, net operating income growth at its go-forward centers jumped to 3.8%. Management paired that with a raised 2028 FFO target of roughly $1.90 and promoted acquisitions from a side project to a named growth engine. The market's response since then has been a shrug. The stock is down 4.9% since the last report, trailing the S&P 500 by 3.5 percentage points. That makes the third-quarter release, due after the close on November 4, a test of whether the inflection was the start of a trend or a single good quarter.
The Street is not asking for much on the headline numbers. Consensus calls for EPS of $0.36, up about 2.9% from $0.35 a year ago, on revenue of $255.6 million, a gain of under 1%. That is essentially flat growth. It reflects an earnings base still weighed down by asset sales, recent share issuance and the cost of lifting transitional properties. With no fresh formal guidance to measure against, the reaffirmed target of at least 3% go-forward NOI growth for 2026 is the real benchmark. A Q3 print near or above the second quarter's 3.8% would back up management's case. A slide back toward 2% would suggest the jump owed something to timing.
The engine behind that growth is the signed-not-opened pipeline, which management calls SNO. It has climbed every quarter, from $99 million to $124 million, against a $140 million target. As the leasing speedometer passed 88%, ahead of its mid-year goal, management said the job was shifting from signing leases to opening stores. The store-openings metric stood at 57% against a 60% year-end target. This quarter should show that conversion moving from the pipeline into rent. Clean evidence would include continued SNO growth, an openings figure at or above 60%, and go-forward occupancy holding at or above 95.5%. Tenant sales, which reached a company record of $919 per square foot, also matter. Rising sales support future rent increases even though portfolio-wide traffic remains roughly flat.
The acquisition story deserves equal attention. Management described its largest deal pipeline since the turnaround plan began, targeting stabilized yields of 9% to 11%. It has $372 million of forward equity to deploy before June 2027 for an estimated $0.02 to $0.04 of FFO accretion. Investors will want either named transactions or a credible timeline. Back-to-back equity raises, a $450 million offering in May and a forward sale at $23.90 in June, drew questions about dilution. Those concerns fade only if the capital is put to work at those yields. Updates on Annapolis and Crabtree also matter, since they underpin about $0.12 of the raised 2028 target. On the risk side, the $76 million 29th Street loan has been in default for four quarters. Asset sales of $300 million to $400 million and land sales keep slipping. Leverage, which fell to 7.3x net debt to EBITDA, should keep moving toward the sub-7x level management cites once the forward equity is counted.
Sentiment has cooled noticeably. Bullish readings fell from 19.9% heading into the last report to just 6.2% now, a muted bar for a company whose tone was the most confident in years. Technically, the stock sits at $24.37. That is comfortably above its 200-day moving average of $22.10 and in the upper half of its post-earnings range of $21.94 to $25.79, though not yet testing the top.
The central question is simple. Did the 3.8% NOI print mark the start of the 6.5% three-year growth path management laid out, or was it an early high point? Steady NOI growth, faster store openings and visible acquisition progress would keep the upgraded narrative intact. A stall on any of those fronts would leave investors' current skepticism looking justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Oct-10 | |
| Oct-08 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Sep-14 | |
| Aug-20 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 |
