Macerich's Modest Beat Undersells A Real Operating Acceleration, But Loan Defaults And Stalled Leverage Temper The Story
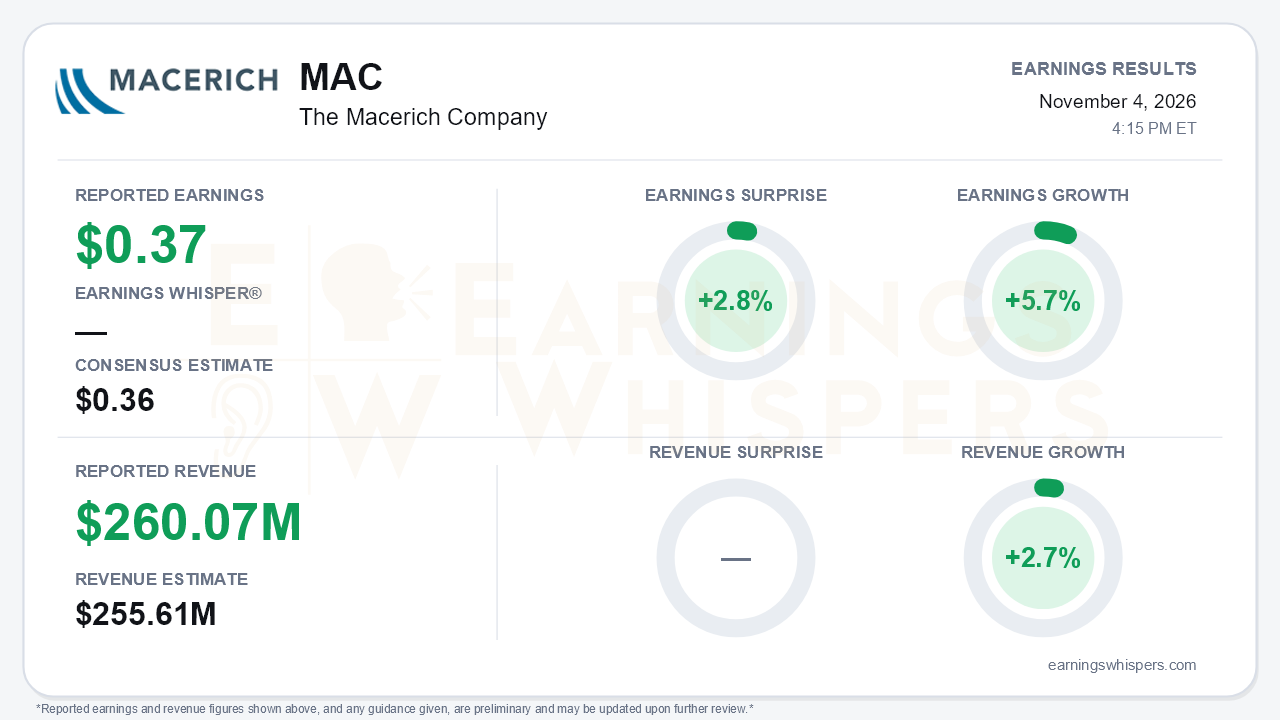
The Macerich Company's third-quarter headline numbers were unremarkable, but the operating detail behind them was not. The mall REIT reported $0.37 per share, ahead of the $0.36 consensus by 2.8%, on revenue of $260.07 million, which topped expectations by 1.7%. Earnings grew 5.7% year over year and revenue rose 2.7%. A one-cent beat rarely moves the narrative. What matters more is that the call showed the multi-year leasing and repositioning plan converting into measurable growth faster than management had been promising. Investors now have to weigh that against a growing list of loan defaults on non-core assets.
The sequential trend is the clearest evidence. FFO as adjusted per share has stepped from $0.34 in the first quarter to $0.35 in the second and $0.37 in the third. Go-forward portfolio NOI growth tells a sharper story. It was 1.7% in the fourth quarter of 2025 and 1.2% in the first quarter, then rose to 3.8% in the second and 4.7% in the third. That lifted the nine-month figure to 3.3% from 2.5% at midyear. Management is no longer simply reaffirming its target of at least 3% NOI growth for 2026. It now says the year is tracking ahead of it. That is a meaningful change in language from the first two quarters.
The leasing metrics underneath support the improvement. Go-forward leased occupancy reached 96.1%, up 60 basis points sequentially and 180 basis points year over year. Total portfolio occupancy improved 90 basis points to 94.9%. Go-forward sales per square foot climbed to $972 from $954 in the second quarter. The signed-not-open pipeline grew to $131 million of the $140 million target. The leasing speedometer reached 91%, and store openings are 62% complete, already past the 60% year-end goal. Roughly 70% of 2027 expirations are committed, compared with 50% last quarter, which reduces a major source of forward uncertainty. Tenant wins included a ninth Dick's House of Sport at Flatiron Crossing and a Zara flagship at Chandler. Management is also negotiating a department store lease for the vacant Sears box at Annapolis. Eight of 30 committed anchors are now open. The CEO said he has "more conviction in this business today than at any point since I joined." The data largely supports that claim.
The capital markets activity may matter as much as the leasing. Macerich has an off-market mall acquisition under contract, expected to close by year end. It carries a 9% to 11% stabilized yield and is fully funded with $372 million of forward equity. Management said the deal is accretive to 2027 and 2028 FFO and reduces leverage by more than 20 basis points. A $775 million offering of 2.25% exchangeable notes due 2031 is retiring a roughly 6.6% Greenacres mortgage. Together with a new, undrawn $550 million acquisition revolver, it marks a deliberate move toward an unsecured capital structure and an eventual investment-grade path. Liquidity rose to about $2.2 billion from $1.2 billion in the second quarter.
Bears still have legitimate ammunition. Loan defaults now extend beyond the $76 million 29th Street mortgage. They include $74 million at Fashion Outlets of Niagara Falls and $325 million at Fresno Fashion Fair. These assets are outside the go-forward portfolio, but the list keeps lengthening. Net debt to EBITDA held at 7.3x, stalling after the half-turn improvement in the second quarter. New-deal approvals are only matching last year's record pace rather than accelerating. Some retailers are signaling slower store openings after weak second-quarter results. Higher long-term rates threaten the 6% refinancing assumption behind the 2028 targets. Those targets, about $1.90 in FFO and roughly 6x leverage, were reaffirmed rather than raised. Formal 2027 guidance will not arrive until February. Macerich is also losing fully marketed mall auctions to stronger bidders, which makes off-market sourcing essential.
The market setup is more complicated than the fundamentals imply. Shares closed at $24.74 before the report. That is down 3.4% from the $25.62 open following the August release and about 4% below the $25.79 inter-earnings high set that same day. The stock bottomed at $21.94 on October 8 and has since recovered nearly 13%. It now sits about 11% above its 200-day moving average. Investor sentiment remained positive but weakened, slipping from 0.199 to 0.109, which suggests some caution entering the print. Sequential growth, momentum and AVWAP trend readings are positive.
The bottom line is that Macerich delivered a quarter where the operating trajectory clearly improved even though the headline beat was small. Rising NOI growth, record go-forward occupancy and a de-risked 2027 lease schedule give the turnaround more substance than a one-cent surprise suggests. Accretive acquisitions and cheaper unsecured financing add a second leg to the story. The offsets are real: non-core defaults, leverage stuck at 7.3x and rate sensitivity in the 2028 plan. Until February guidance shows whether this momentum extends into 2027, investors are being asked to trust a reaffirmed long-term target rather than a raised one.
Read our earnings preview for The Macerich Company: https://www.earningswhispers.com/article/MAC/21867
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Nov-02 | |
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Oct-10 | |
| Oct-08 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Sep-14 | |
| Aug-20 | |
| Aug-07 |
